Stock Analysis · Silvercorp Metals Inc (SVM)
Overview
Silvercorp Metals Inc. is a Canada-based mining company focused on producing silver, along with lead, zinc, and some gold, mainly from underground mines in China. It also has development exposure in Ecuador through the El Domo copper-gold project and the Condor gold project, which broadens the business beyond its established silver operations. In simple terms, Silvercorp digs ore out of the ground, processes it, and sells the metals it recovers.
The company’s revenue is still driven primarily by its Chinese mining operations. Based on recent annual reporting and operating disclosures, the main sources of revenue can be understood as follows:
- Silver: approximately 40% to 50% of revenue in a typical year. This is the company’s core product and the main reason it is followed as a silver stock.
- Lead: approximately 25% to 35%. Lead is produced together with silver from the same ore bodies and is an important by-product that supports economics.
- Zinc: approximately 15% to 25%. Like lead, zinc is sold from polymetallic ore and adds meaningful cash flow.
- Gold and other: usually under 10%. This includes smaller gold output and other minor items.
That mix matters because Silvercorp is not a pure silver-price vehicle. Its financial results depend on several metal prices, mining grades, recovery rates, and the timing of concentrate sales. The business model has historically been relatively straightforward: operate profitable mines with controlled costs, keep the balance sheet conservative, and use internal cash generation plus selective financing to expand the asset base.
Revenue has climbed sharply in the latest period, and operating income remains solid, but the latest annual flow also shows that bottom-line earnings were pressured by much higher interest and tax expense. That combination suggests the core mines are performing well, while corporate expansion and financing have made reported earnings less clean than the revenue trend alone would imply.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Silver | |
| Market Cap ⓘ | $2.22B | |
| Beta ⓘ | 2.04 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 91.27 | 16.90 |
| P/B Ratio ⓘ | 3.07 | 1.65 |
| FCF Yield ⓘ | 1.57% | 5.76% |
| Dividend Yield ⓘ | 0.24% | 2.13% |
| EBIT / EV ⓘ | 5.91% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 70.50% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 13.06% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -1.32% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 5.34% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -4.90% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 45.76% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 0.24% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 7.30% | 9.26% |
| ROA (Latest) ⓘ | 2.15% | 4.91% |
| ROIC (5Y Median) ⓘ | 8.89% | 7.70% |
| ROA (5Y Median) ⓘ | 4.45% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -0.07 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | -2.29 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.05 | 0.95 |
| Net Debt / Assets ⓘ | -0.61% | 13.69% |
| EBITDA / Interest ⓘ | 14.53 | 12.34 |
| Operating Margin (Latest) ⓘ | 27.53% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 26.35% | 11.80% |
| Debt to Equity (Latest) ⓘ | 12.00% | 40.56% |
| Profit Margin (Latest) ⓘ | 6.32% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $34.87M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +300.22% | +68.89% |
| 12M Return (excl. last month) ⓘ | +117.27% | +30.21% |
| 6M Return ⓘ | -23.87% | -4.16% |
| Price vs. 200-Day MA ⓘ | -16.35% | -1.27% |
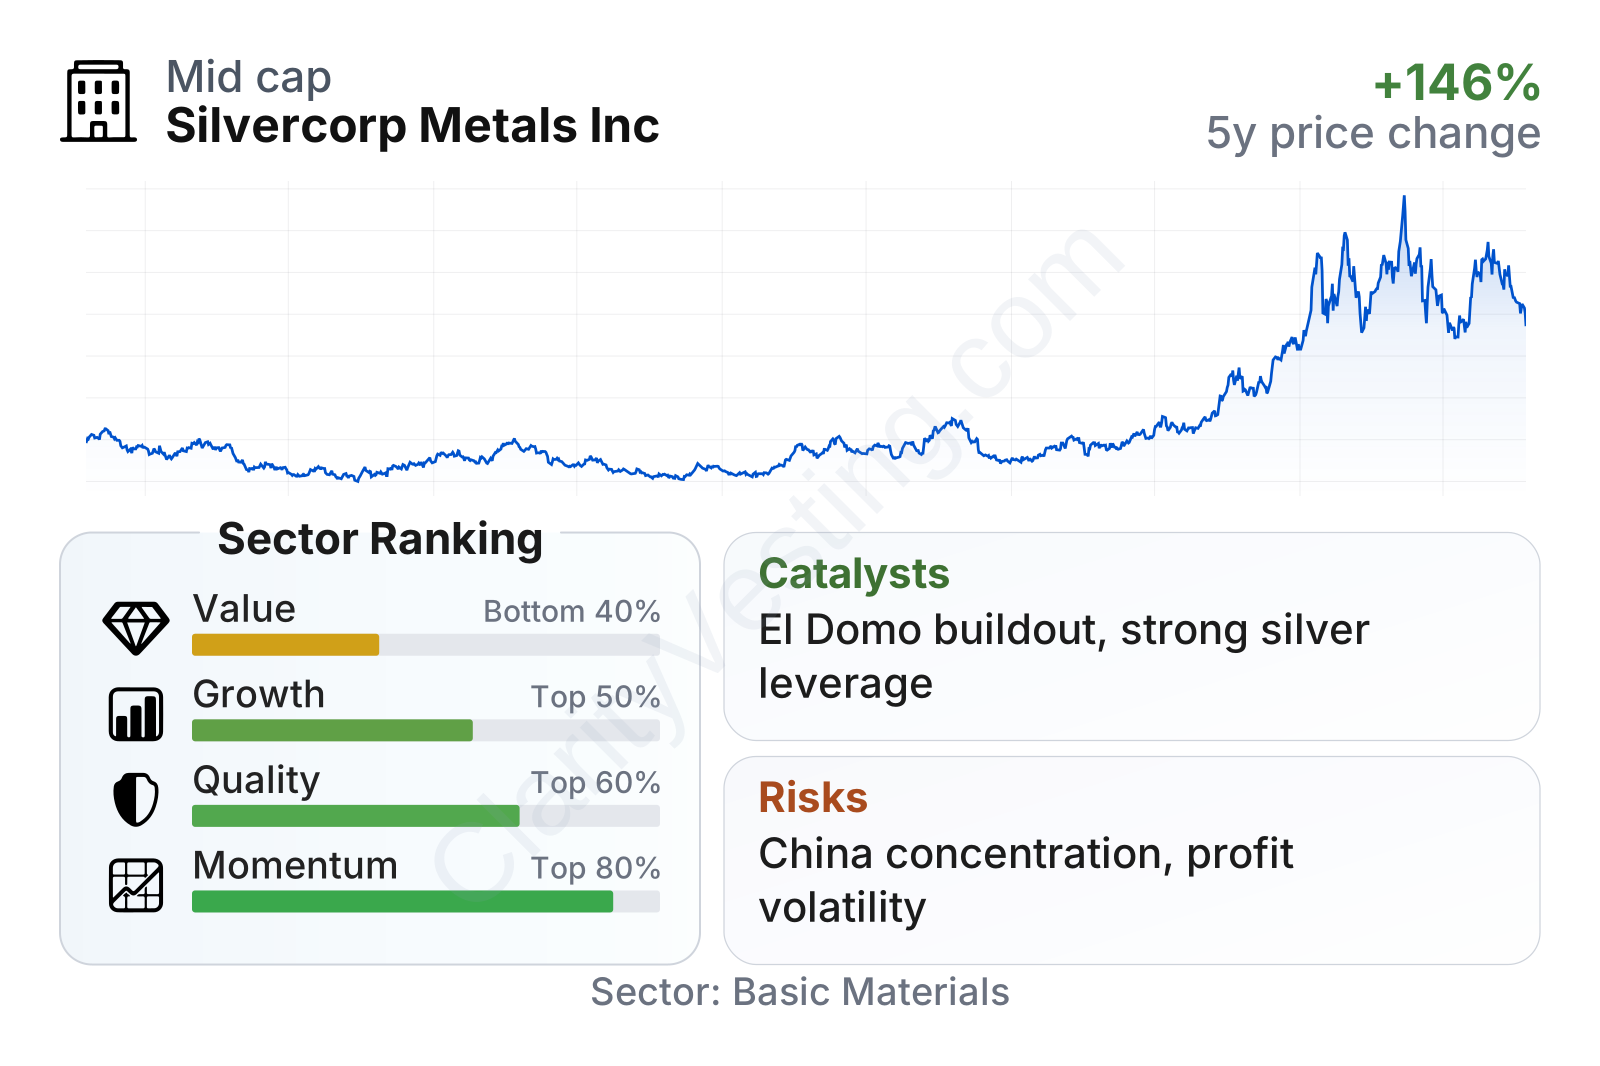
Silvercorp is now a mid-sized mining company with a stock that has been much more volatile than the broader market, which is common for precious-metals names but still notable here. On quality and growth measures, it ranks in the upper half of its sector, helped by strong operating margins, solid long-term cash generation, and a balance sheet that remains lightly leveraged. On valuation, however, it screens weaker than many peers because the current earnings multiple is elevated and free-cash-flow yield is below the sector median. Price performance over the last three years has been very strong, which helps explain why valuation looks less forgiving today than it did earlier in the cycle.
Growth
Silvercorp operates in a sector with long-term structural support, even though it remains cyclical. Silver demand is tied not only to jewelry and investment demand but also to industrial uses such as electronics, solar applications, and electrification. Zinc and lead are more industrial and construction-linked, while gold can provide some defensive support. That means the company sits at the intersection of precious metals and industrial metals, which can be helpful when one end market is softer than the other.
The company’s strategy for future growth is relatively logical. Its established mines in China provide the operating base, while Ecuador offers the clearest path to a larger production profile. The El Domo project is particularly important because it gives Silvercorp exposure to copper as well as precious metals, adding another growth lane and reducing dependence on one country over time. For a miner of this size, adding a second operating region can materially change scale, market perception, and reserve life.
Recent revenue growth has been very strong, with year-over-year gains far above the sector median. That does not mean growth will move in a straight line, since mining businesses often swing with grades, metal prices, and shipment timing. Still, the five-year trend in revenue per share is clearly better than the broader sector, which suggests the company has created real operating momentum rather than relying only on temporary price spikes.
Cash generation has also improved over time, although not smoothly. Free cash flow dipped in some periods and then rebounded sharply, which is common when a miner increases development spending or working capital moves around. Even so, the longer-term pattern is encouraging: free cash flow has expanded far faster than the sector median over five years, indicating that production growth and margin strength have translated into real cash rather than only accounting profits.
A major catalyst in the current phase is the buildout and advancement of the Ecuador assets. If project execution stays on track, Silvercorp could evolve from a China-focused silver producer into a more diversified base and precious metals company. Another catalyst is metal prices themselves. Because Silvercorp already has operating mines and healthy margins at the operating level, stronger silver, lead, zinc, or copper prices can have an outsized effect on reported earnings and cash flow.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


