Stock Analysis · Standard Nuclear Inc (STDN)
Overview
Standard Nuclear Inc is a small public company focused on nuclear fuel-related materials and services. Public company materials describe the business as operating in the nuclear supply chain, an area that sits between uranium mining and electricity generation. In simple terms, the company is trying to serve the growing need for fuel inputs used by nuclear reactors, especially as the United States and other countries look for more secure domestic supply.
At this stage, the business appears to be in an early commercial phase rather than a mature industrial model. That matters for long-term analysis: the strategic theme can be attractive, but current operating scale is still very limited compared with larger listed materials and nuclear supply companies.
Based on available public information, revenue disclosure is not yet detailed enough to provide a precise business-line split with reliable percentages. The company’s current revenue base appears to come primarily from nuclear fuel-cycle related products and services, but recent filings and public materials do not seem to break this down into clearly reported segments large enough to support a dependable ranked list by percentage.
The latest income flow also shows an important constraint: revenue remains low while production and operating costs are still heavy. In the most recent annual picture available, total revenue was roughly $3 million, while cost of revenue exceeded that amount, resulting in negative gross profit. That suggests the company is still building scale, efficiency, or both.
The business mix currently looks less like a fully optimized chemicals company and more like a developing strategic supplier. The key takeaway from the income flow is that expenses are still running well ahead of sales, so the investment case depends much more on future capacity, contract wins, and industry demand than on present-day profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $2.01B | |
| Beta ⓘ | N/A | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.90 |
| P/B Ratio ⓘ | N/A | 1.65 |
| FCF Yield ⓘ | -1.58% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | -0.82% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 756.50% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 5.51% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | N/A | 4.91% |
| ROIC (5Y Median) ⓘ | N/A | 7.70% |
| ROA (5Y Median) ⓘ | N/A | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.34 |
| Operating Margin (Latest) ⓘ | -249.04% | 13.20% |
| Operating Margin (5Y Median) ⓘ | N/A | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | -222.32% | 6.43% |
| Free Cash Flow (Latest) ⓘ | -$31.67M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +68.89% |
| 12M Return (excl. last month) ⓘ | N/A | +30.21% |
| 6M Return ⓘ | N/A | -4.16% |
| Price vs. 200-Day MA ⓘ | N/A | -1.27% |
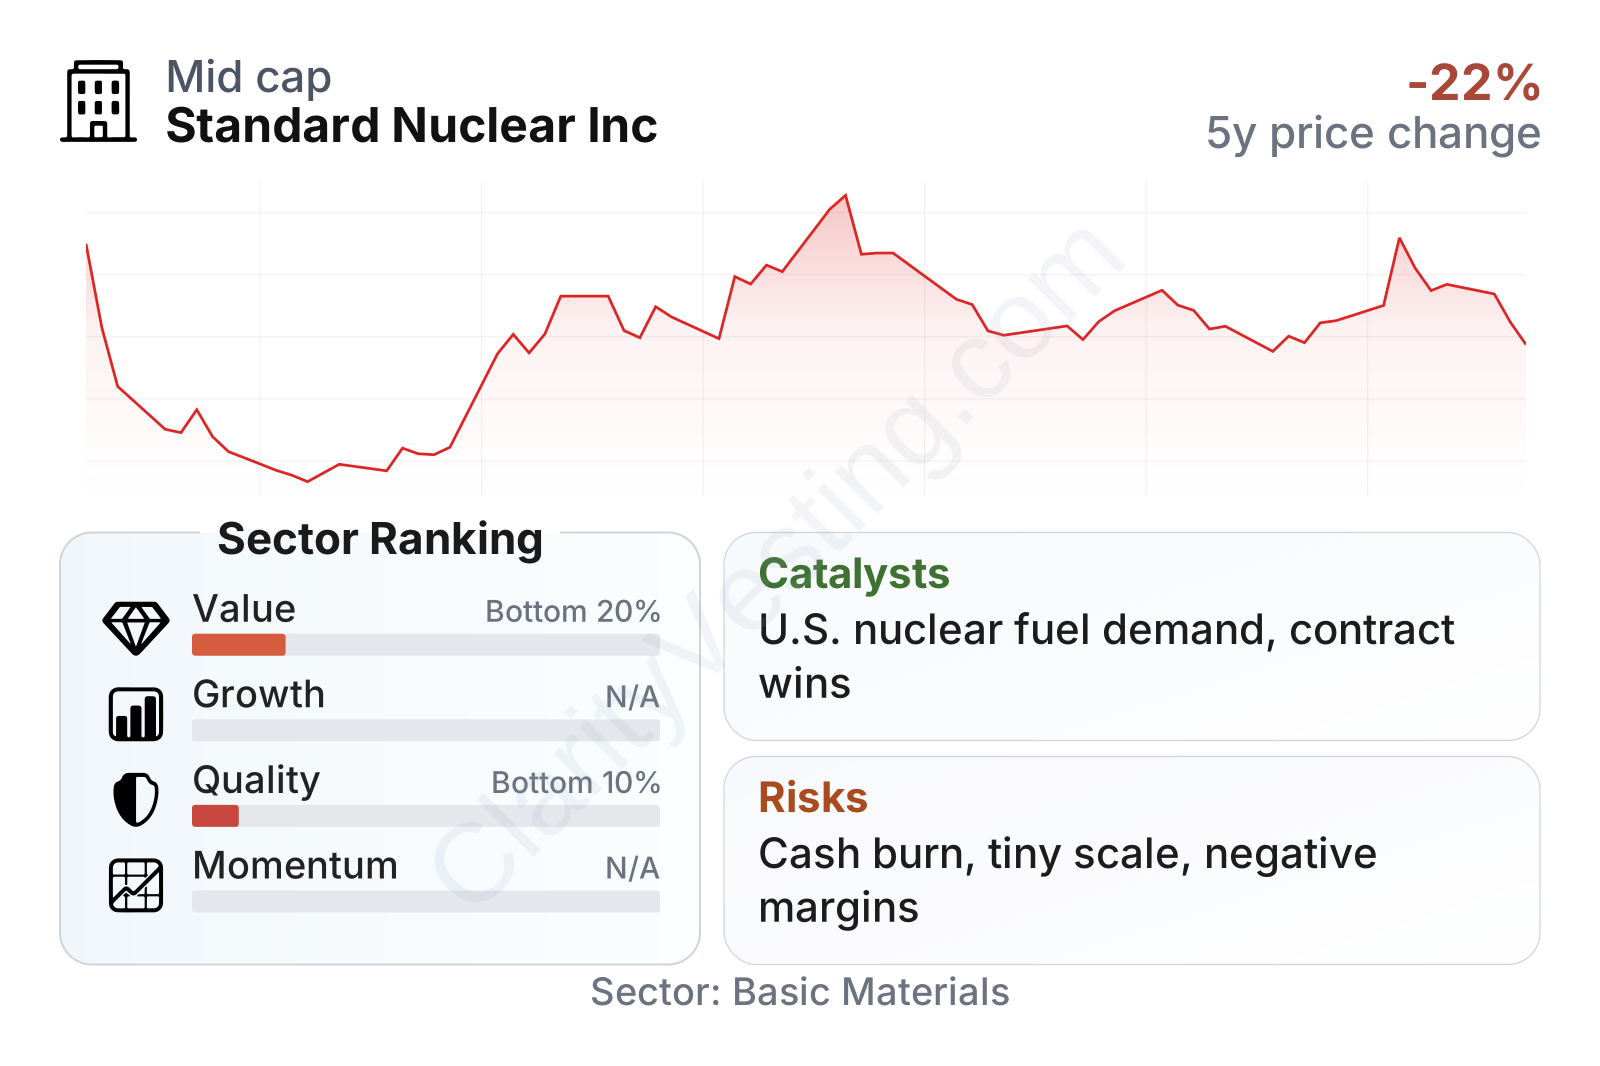
Standard Nuclear is still a relatively small listed company, with an equity value around the lower end of public-market industrial names. The metrics point to a business with strong top-line expansion but weak current fundamentals. Revenue growth is far above the sector median, which shows that activity is ramping quickly, but profitability and cash generation remain meaningfully weaker than most specialty chemicals peers.
Quality metrics are especially soft. Operating margin and profit margin are deeply negative, and free cash flow is also negative. On valuation screens, the stock ranks poorly versus the sector because common measures tied to earnings and cash flow are not yet supported by a profitable base. In short, the market is valuing future potential more than current financial strength.
Growth
The broader sector backdrop is supportive. Nuclear energy has regained strategic importance because it offers reliable low-carbon electricity and helps countries reduce dependence on fragile fuel supply chains. In the United States, policy support for domestic nuclear fuel capabilities has become stronger in recent years, especially around enrichment, conversion, and other parts of the fuel cycle that have historically relied on foreign sources.
That creates a logical growth lane for a company like Standard Nuclear. If it can become a qualified domestic supplier in a part of the nuclear materials chain where Western capacity is tight, even a small current business could expand quickly from a low base. This is one reason the very high year-over-year revenue growth figure matters, even though it comes with weak margins: it suggests the company is moving from concept toward commercial activity.
A potential catalyst is the continued push in North America for localized nuclear fuel infrastructure. Utilities, reactor developers, and government-backed programs are all looking for supply security. If Standard Nuclear participates in that buildout through customer agreements, qualification milestones, or capacity additions, its addressable market could become much larger than its present sales level implies.
Another positive element is timing. Interest in advanced reactors and broader nuclear fleet support has been rising, which can increase demand for specialized fuel-related inputs over time. For a small company, even a handful of meaningful contracts, technical approvals, or strategic partnerships could have an outsized effect on revenue.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


