Stock Analysis · Sinofert Holdings Ltd (SNFRY)
Overview
Sinofert Holdings Ltd is a Chinese agricultural inputs company focused on supplying fertilizers and related farm products. Its role in the value chain is practical and easy to understand: it sources, produces, blends, distributes, and sells crop nutrients and agricultural materials to support farming output. The company is part of the larger Sinochem group, which gives it access to a broad industrial network and a meaningful position in China’s farm supply market.
The business is mainly driven by fertilizer distribution and production. Based on the company’s recent annual reporting structure, revenue is concentrated in a few major categories.
- Fertilizer and raw material trading/distribution: approximately 70% to 80% of revenue. This is the core activity and includes potash, phosphate, nitrogen, compound fertilizer, and related upstream materials sold through a nationwide distribution system.
- Compound fertilizer and other production-related sales: approximately 15% to 25% of revenue. This includes value-added blended or compound products designed for different crops and regions.
- Pesticides, agricultural services, and other agricultural inputs: generally a smaller share below 10% of revenue. These activities support the broader farm-input platform but are not the main earnings driver.
What stands out is that Sinofert operates in a high-volume, low-margin business where scale, sourcing, logistics, and customer reach matter more than brand appeal. The recent income flow also shows a favorable pattern: revenue has stayed broadly stable over several years, while gross profit, operating income, and net income have improved from the weaker 2023 level, suggesting better pricing, product mix, or operating discipline rather than simple top-line expansion.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Agricultural Inputs | |
| Market Cap ⓘ | $1.17B | |
| Beta ⓘ | 0.75 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 7.59 | 16.90 |
| P/B Ratio ⓘ | 0.10 | 1.65 |
| FCF Yield ⓘ | 44.40% | 5.76% |
| Dividend Yield ⓘ | 4.31% | 2.13% |
| EBIT / EV ⓘ | N/A | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.60% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | -0.01% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 5.91% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 2.62% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 65.98% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 28.19% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 14.02% | 4.91% |
| ROIC (5Y Median) ⓘ | 8.48% | 7.70% |
| ROA (5Y Median) ⓘ | 5.01% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -0.24 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.12 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.19 | 0.95 |
| Net Debt / Assets ⓘ | -3.81% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.34 |
| Operating Margin (Latest) ⓘ | 7.69% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 4.34% | 11.80% |
| Debt to Equity (Latest) ⓘ | 15.85% | 40.56% |
| Profit Margin (Latest) ⓘ | 5.37% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $520.89M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +28.39% | +68.89% |
| 12M Return (excl. last month) ⓘ | +5.55% | +30.21% |
| 6M Return ⓘ | +4.54% | -4.16% |
| Price vs. 200-Day MA ⓘ | +2.15% | -1.27% |
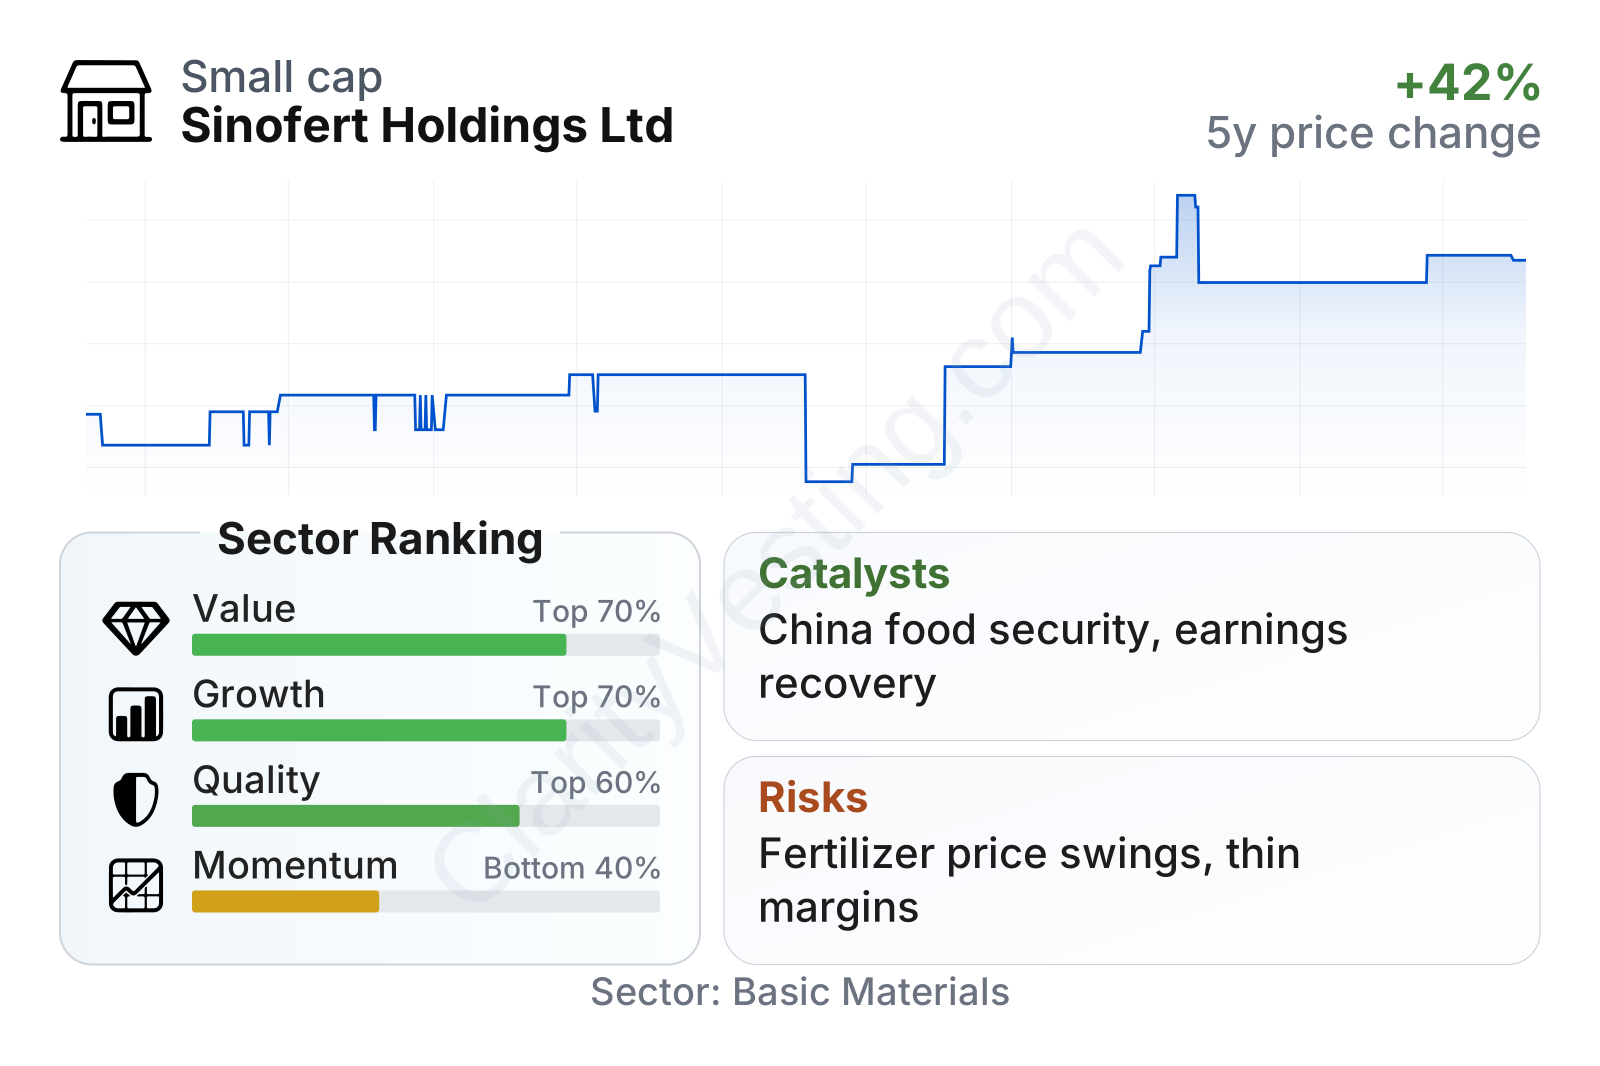
Sinofert looks inexpensive on several traditional valuation measures. Its earnings multiple is well below the sector median, the price-to-book ratio is extremely low, and the dividend yield is above the sector norm. Cash generation is especially notable, with free cash flow yield far ahead of many peers. On quality, the balance sheet appears conservative: debt-to-equity is around 16%, and net debt metrics indicate the company is operating with net cash rather than meaningful leverage.
The picture is more mixed on operating performance. Return on assets is strong relative to the sector, but profit margins and operating margins are still below sector medians, which is common in distribution-heavy agricultural input businesses. Growth indicators also show an uneven pattern. Recent yearly revenue growth is positive and close to the sector median, book value has compounded steadily, and free cash flow growth over five years has been very strong. However, longer-term revenue per share has been roughly flat, and the stock’s market performance has lagged much of the sector over the last three years even though the recent six-month trend has improved.
Growth
Sinofert operates in a sector with durable long-term demand rather than rapid expansion. Fertilizer is tied to food production, crop yields, and arable land efficiency, which gives the business a structural base. In China, the growth case is less about farmland expansion and more about better nutrient efficiency, upgraded crop solutions, and more sophisticated farm services. That kind of environment can favor larger distributors and integrated suppliers that can combine procurement, logistics, product formulation, and agronomic support.
The company’s strategy appears sensible for that landscape. A broad distribution footprint, product coverage across major fertilizer types, and links to large upstream industrial resources can help it protect volume and improve product mix. Compound fertilizer and crop-specific offerings are also more attractive than pure commodity reselling because they can support better margins and closer customer relationships. This matters because commodity fertilizer pricing is volatile, while service depth and formulation capability can create a steadier competitive position.
A visible catalyst is earnings recovery. After weaker profitability in 2023, the business rebounded strongly in 2024 and appears to have carried that improvement forward, with gross profit and net income reaching stronger levels while interest expense moved lower. That combination suggests the company may be benefiting from better operating efficiency, financing discipline, and possibly more favorable procurement conditions. A second catalyst is balance-sheet flexibility: with low leverage and strong cash generation, Sinofert has room to support dividends, working capital needs, and selective business investment without heavy financing pressure.
There is also a broader policy backdrop worth watching. China continues to treat food security and agricultural productivity as strategic priorities. That does not guarantee high growth, but it supports the importance of reliable fertilizer supply chains, which is directly aligned with Sinofert’s core business.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


