Stock Analysis · Scotts Miracle-Gro Company (SMG)
Overview
Scotts Miracle-Gro is a consumer lawn and garden company best known for grass seed, fertilizers, soils, mulch, and plant food sold under brands such as Scotts, Miracle-Gro, Ortho, Tomcat, and Roundup for consumer lawn and garden use in the United States. The business is centered on products used by homeowners to maintain lawns, grow plants, and control weeds and pests. It also has a smaller indoor and hydroponic gardening operation through Hawthorne, which serves growers with lighting, nutrients, and related equipment.
The company’s revenue is mainly generated in North America and is highly seasonal, with the largest sales period typically tied to the spring and early summer lawn and garden season. Based on the latest annual reporting structure, revenue is largely split between its core U.S. Consumer segment and the smaller Hawthorne segment.
Main sources of revenue are approximately:
- U.S. Consumer: about 88% to 92% of revenue. This includes lawn fertilizer, grass seed, soils, mulch, plant food, weed control, insect control, and outdoor pest control products sold mainly through major retailers and home improvement chains.
- Hawthorne: about 8% to 12% of revenue. This includes hydroponic and indoor growing products such as lighting, nutrients, growing media, and environmental controls.
Within the core consumer business, the largest categories typically come from lawn care, soils and growing media, and gardening products, although the exact mix shifts with weather, retailer inventory timing, and consumer demand. The overall business mix has become more concentrated in the consumer segment as Hawthorne has contracted sharply from its earlier peak.
The financial flow over the last few years shows a business that went through a difficult reset and then improved meaningfully. Revenue declined from the 2022 peak, but gross profit and operating income recovered strongly by fiscal 2025 as costs eased and execution improved. Interest expense remains a notable drag, which matters because the company still carries substantial debt.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Agricultural Inputs | |
| Market Cap ⓘ | $3.25B | |
| Beta ⓘ | 1.85 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 19.95 | 16.92 |
| P/B Ratio ⓘ | N/A | 1.66 |
| FCF Yield ⓘ | 10.04% | 5.83% |
| Dividend Yield ⓘ | 4.85% | 2.07% |
| EBIT / EV ⓘ | 6.84% | 6.38% |
| PEG ⓘ | 0.74 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1.10% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | -9.35% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 12.62% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -5.08% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 13.58% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 1.26% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.09% | 9.59% |
| ROA (Latest) ⓘ | 2.50% | 4.92% |
| ROIC (5Y Median) ⓘ | 4.74% | 7.91% |
| ROA (5Y Median) ⓘ | -1.11% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 5.92 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.69 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 4.57 | 0.93 |
| Net Debt / Assets ⓘ | 65.85% | 13.69% |
| EBITDA / Interest ⓘ | 4.03 | 12.38 |
| Operating Margin (Latest) ⓘ | 10.44% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 3.81% | 11.82% |
| Debt to Equity (Latest) ⓘ | -1012.60% | 40.30% |
| Profit Margin (Latest) ⓘ | 2.12% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $326.40M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +36.82% | +73.47% |
| 12M Return (excl. last month) ⓘ | -7.43% | +27.59% |
| 6M Return ⓘ | -11.18% | -4.02% |
| Price vs. 200-Day MA ⓘ | -8.24% | -0.65% |
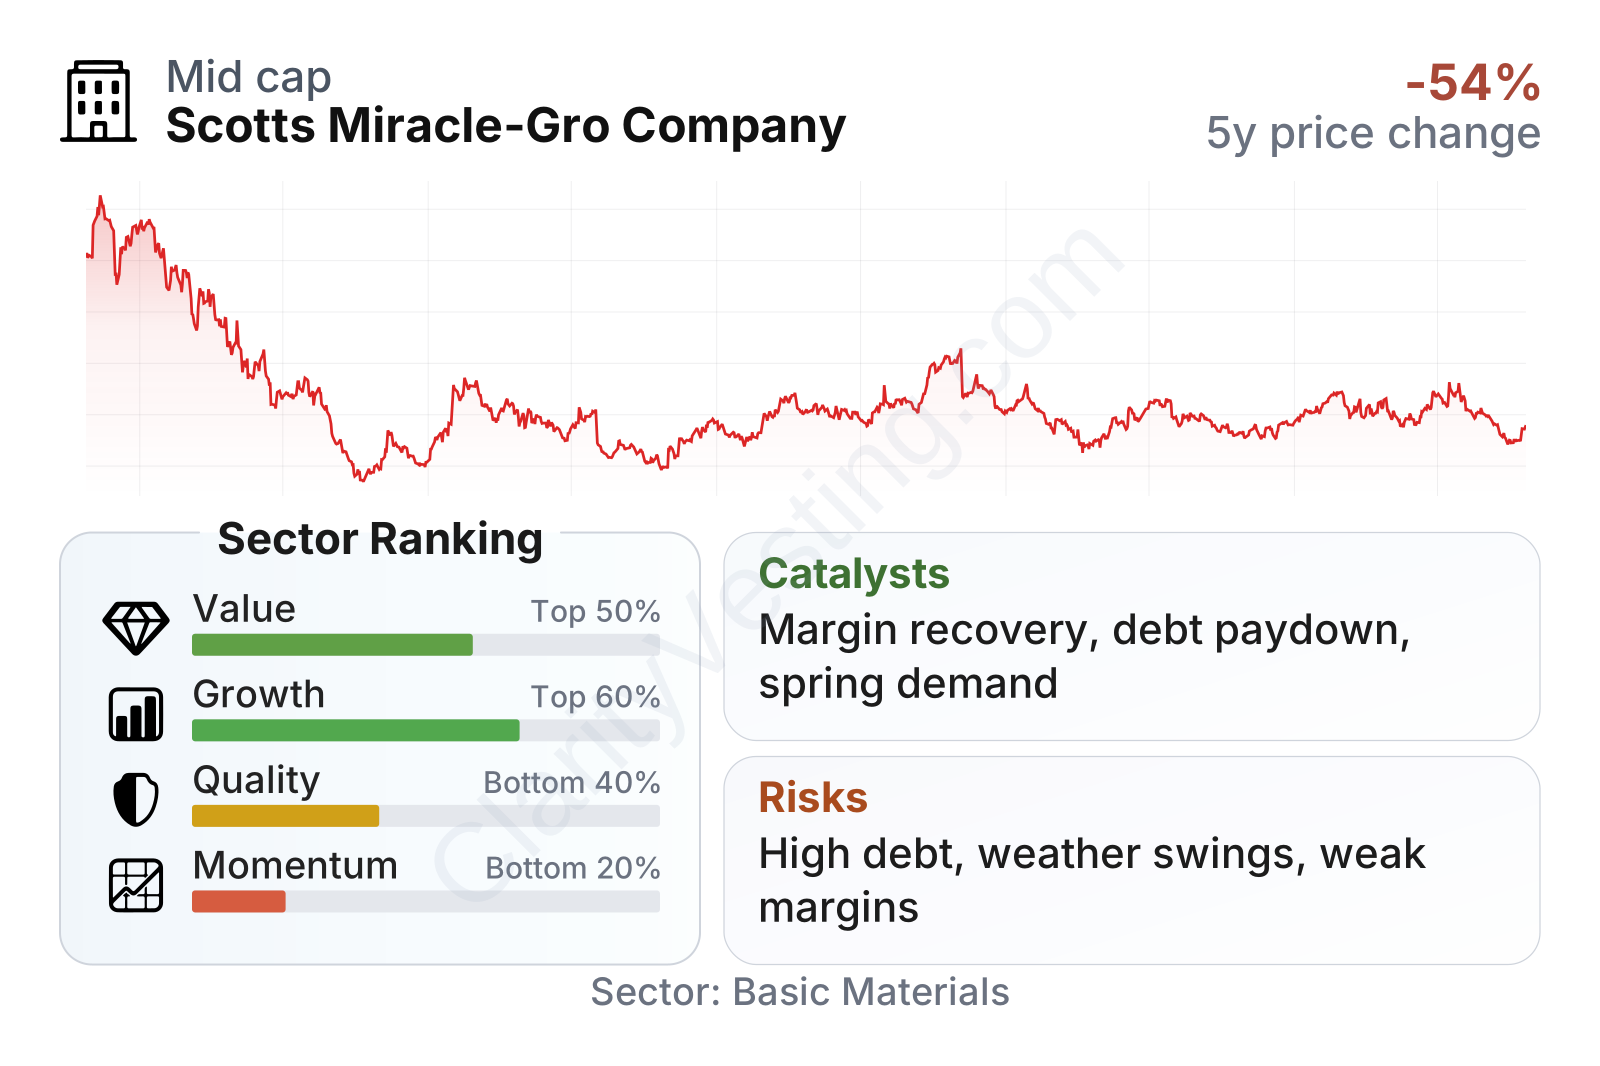
Scotts Miracle-Gro is a mid-sized company with a stock that has been far more volatile than the broader market, reflected in a beta well above 1. The share price is still far below its 2021 high, which matches the company’s uneven operating path over the last several years. In the latest metrics, valuation is mixed rather than clearly cheap or expensive: earnings and enterprise-value-based multiples sit around the sector range, while free cash flow yield and dividend yield stand out as stronger than the sector median. Growth metrics are uneven, quality is held back by leverage, and market momentum remains weak compared with peers.
Growth
Scotts Miracle-Gro operates in a mature but durable category rather than a high-growth industry. Lawn care and home gardening benefit from recurring household spending, brand familiarity, and large retail distribution. That creates resilience, but not rapid expansion. The more interesting long-term question is whether the company can grow through market share, pricing, innovation, and margin recovery rather than through a booming end market.
The current strategy appears more focused and more realistic than during the hydroponics upswing. Management has emphasized strengthening the core consumer business, simplifying operations, improving inventory discipline, and using cash generation to support the balance sheet. That makes strategic sense because the consumer segment is the company’s economic engine, while Hawthorne has become a much smaller contributor after a severe industry downturn.
Revenue trends show how uneven the reset has been. The company moved from steep declines in 2022 and 2023 to a recovery in 2024, then returned to mostly flat or slightly negative year-over-year changes more recently. In other words, the business has stabilized, but it has not yet established a strong, sustained top-line growth pattern. Relative to the broader agricultural inputs group, recent revenue expansion remains modest.
Cash generation is a more constructive part of the picture. Free cash flow rebounded sharply from the negative level seen during the downturn and has remained positive at a meaningful level. Even though it is below the temporary high reached during the recovery phase, it still indicates that the business can produce real cash when operations normalize. That matters for Scotts because cash flow is central to debt reduction, dividends, and flexibility during seasonal swings.
Potential catalysts are tied less to a new market opening and more to execution. A normal or favorable spring season, continued retail support, stable input costs, and further improvements in the Hawthorne business could all help results. There is also a broader opportunity in ongoing consumer interest in outdoor living and home improvement, even if that trend is no longer at its pandemic peak. Recent company communications have also pointed to efforts around margin improvement, cost discipline, and portfolio focus, which are important because earnings recovery does not require dramatic sales growth if profitability improves.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


