Stock Analysis · The J. M. Smucker Company (SJM)
Overview
The J. M. Smucker Company is a U.S. packaged food company focused on products that are bought repeatedly and sold through grocery, club, mass retail, e-commerce, and pet specialty channels. Its portfolio spans coffee, peanut butter, fruit spreads, frozen sandwiches, sweet baked snacks, dog snacks, cat food, and pet food. Well-known brands include Folgers, Dunkin’ retail coffee, Café Bustelo, Jif, Smucker’s, Uncrustables, Hostess, Milk-Bone, Meow Mix, and Kibbles ’n Bits.
Revenue is spread across three main operating segments. Based on the latest annual reporting for fiscal 2026, the mix is approximately:
- U.S. Retail Coffee: about 31% of revenue. This includes mainstream, premium, and espresso-style packaged coffee sold primarily under Folgers, Dunkin’, and Café Bustelo.
- U.S. Retail Frozen Handheld and Spreads: about 25%. This segment includes Uncrustables sandwiches, Jif peanut butter, and Smucker’s fruit spreads.
- Sweet Baked Snacks: about 18%. This is mainly the Hostess business, including snack cakes, donuts, and related convenience-channel products.
- Pet Foods and Snacks: about 17%. This includes dog snacks and selected pet food brands such as Milk-Bone, Meow Mix, and Kibbles ’n Bits.
- International and Away From Home: about 9%. This includes international sales and products sold outside traditional retail, such as foodservice channels.
That mix matters because it shows Smucker is no longer just a jam-and-peanut-butter company. Coffee remains the largest earnings engine, but the company has been reshaped around higher-velocity categories such as frozen convenience foods and pet-related products. At the same time, recent growth has come with more balance-sheet strain and integration complexity.
The multiyear flow of revenue and expenses shows a business that kept expanding sales, but not all of that growth translated smoothly into profit. Gross profit improved over time, yet interest expense rose sharply and bottom-line results were distorted by major charges, especially around the Hostess acquisition and related write-downs. That helps explain why Smucker can look solid on sales and cash flow while appearing weaker on reported earnings.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Packaged Foods | |
| Market Cap ⓘ | $12.82B | |
| Beta ⓘ | 0.27 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 56.08 | 17.88 |
| P/B Ratio ⓘ | 2.26 | 1.29 |
| FCF Yield ⓘ | 12.39% | 12.39% |
| Dividend Yield ⓘ | 3.69% | 2.85% |
| EBIT / EV ⓘ | 3.97% | 6.43% |
| PEG ⓘ | 1.68 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 5.00% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 3.55% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | -26.76% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | -8.80% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | -9.04% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 12.62% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 3.08% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 5.91% | 12.34% |
| ROA (Latest) ⓘ | 1.36% | 6.30% |
| ROIC (5Y Median) ⓘ | 2.53% | 10.49% |
| ROA (5Y Median) ⓘ | -0.59% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 8.73 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 14.39 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 5.14 | 1.38 |
| Net Debt / Assets ⓘ | 42.30% | 21.51% |
| EBITDA / Interest ⓘ | 3.67 | 9.46 |
| Operating Margin (Latest) ⓘ | 8.58% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 3.52% | 9.53% |
| Debt to Equity (Latest) ⓘ | 119.93% | 72.35% |
| Profit Margin (Latest) ⓘ | 2.51% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $1.59B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +20.30% | +20.92% |
| 12M Return (excl. last month) ⓘ | +17.00% | +2.13% |
| 6M Return ⓘ | +38.31% | +1.26% |
| Price vs. 200-Day MA ⓘ | +12.52% | +1.39% |
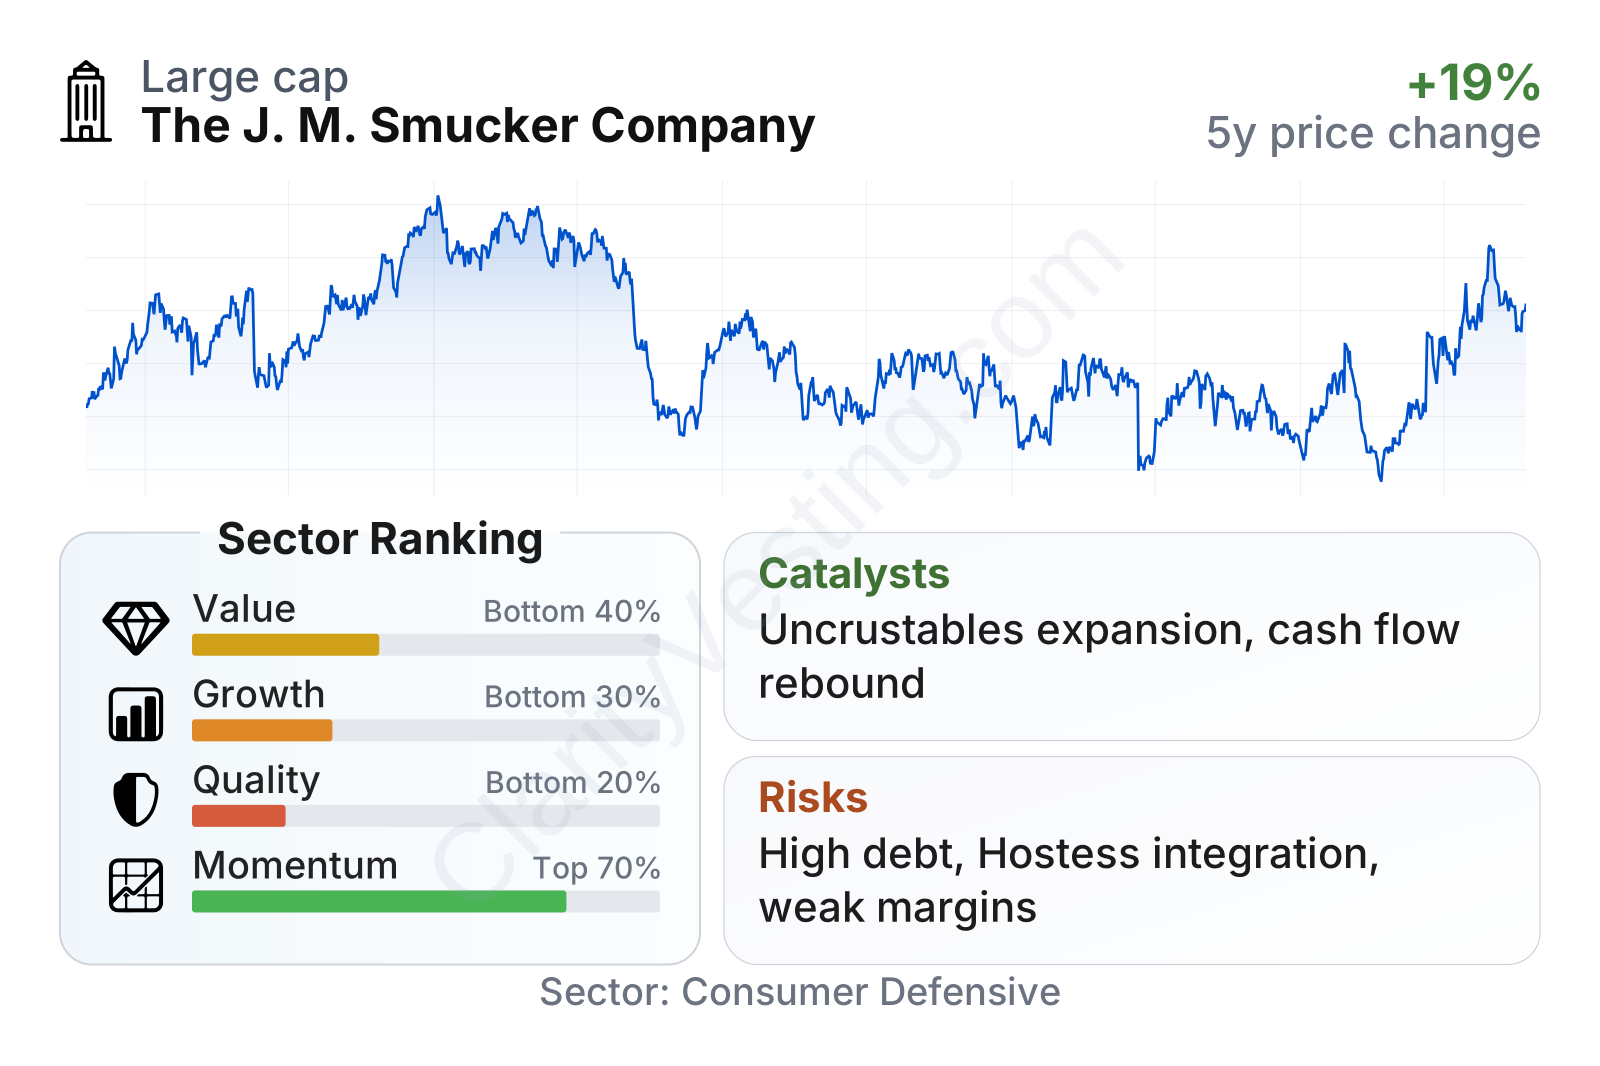
Smucker is a large consumer staples company with unusually low share-price volatility for the market, as shown by its very low beta. The table points to a mixed profile. Revenue growth and free cash flow have been respectable, and the dividend yield is above the sector median. However, profitability, returns on capital, and leverage compare less favorably with peers. The valuation picture is also uneven: cash-flow-based measures look more acceptable than the earnings multiple, which is inflated by weak recent net income.
The stock history reinforces that pattern. Over several years, the shares have moved through long flat periods and then sharp recoveries, reflecting the market’s changing view on inflation, coffee costs, the Hostess deal, and the company’s ability to restore margins.
Growth
Smucker operates in categories that are generally mature rather than high-growth, but some of its niches still offer clear expansion room. Packaged coffee is a stable category with pricing power when brands are strong. Frozen convenience foods are supported by demand for quick meals and lunch solutions. Pet food and pet snacks remain attractive because spending on pets tends to be relatively resilient. Sweet baked snacks are slower-growing structurally, but they can still produce solid sales when backed by strong distribution and convenience-channel execution.
The company’s strategy for future growth is centered on a few identifiable engines rather than broad portfolio expansion. The biggest one is Uncrustables, which management has repeatedly highlighted as a major capacity and distribution opportunity. That brand sits at the intersection of convenience, lunchbox demand, and brand familiarity, giving Smucker room to grow volume instead of relying only on price increases.
Coffee is another pillar. Smucker holds strong shelf presence in at-home coffee, and premiumization can support value growth even in a slow-volume environment. In pet products, the company is trying to focus on categories where brand recognition and repeat purchases are strong, rather than chasing every part of the market.
Recent sales momentum has improved again after a choppy period. Year-over-year revenue growth was negative in parts of 2024 and 2025, but the latest readings show a return to positive mid-single-digit growth. That suggests the company has regained some forward movement, helped by portfolio changes and steadier execution.
Cash generation has been more encouraging than earnings. Free cash flow has trended upward from roughly $0.6 billion to nearly $1.0 billion over the period shown, and the latest metric set points to trailing free cash flow around $1.6 billion. For a consumer staples company dealing with integration work and elevated financing costs, that is an important stabilizing factor.
A meaningful recent catalyst is the company’s ongoing effort to extract benefits from the Hostess acquisition while also investing behind core brands such as Uncrustables and coffee. If Smucker can improve distribution, productivity, and manufacturing efficiency at the same time, modest category growth could translate into better overall business performance than the sector’s headline growth rate might suggest.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


