Stock Analysis · SiteOne Landscape Supply Inc (SITE)
Overview
SiteOne Landscape Supply is a specialized distributor serving the landscape industry in the United States and Canada. Rather than manufacturing products, the company operates a large branch network that supplies professional landscape contractors, golf course operators, municipalities, and other commercial customers with the materials they need to build, maintain, and upgrade outdoor spaces. Its role is similar to a one-stop supply platform for landscaping, irrigation, nursery, agronomic, and outdoor lighting needs.
The business makes money primarily by buying products from manufacturers and growers, then reselling them through its branch footprint and service network. SiteOne also supports customers with product availability, local service, design support in some categories, and delivery logistics. This distribution model matters because customers often value reliability, product breadth, and convenience as much as headline price.
Based on company disclosures, revenue is spread across several major product groups, with the following mix being a useful approximation for understanding the business:
- Irrigation supplies: approximately 30% of revenue. This includes irrigation components, control systems, drip products, and related water-management equipment.
- Nursery products: approximately 25% of revenue. This category includes trees, shrubs, and other live goods used in landscape projects.
- Hardscapes: approximately 20% of revenue. This covers pavers, blocks, stone, and other materials used in patios, retaining walls, and outdoor construction.
- Landscape accessories: approximately 15% of revenue. This generally includes soils, fertilizers, grass seed, edging, drainage products, and other job-site essentials.
- Agronomic and turf care products: approximately 5% to 10% of revenue. These products support turf maintenance for commercial landscapes and golf-related applications.
- Outdoor lighting and other categories: a smaller share of revenue. This includes lighting products and adjacent specialty items.
Over the last several years, SiteOne has grown into one of the largest dedicated landscape supply distributors in its niche. Revenue has continued rising, reaching roughly $4.7 billion in 2025, but earnings have not kept pace because operating costs and margin pressure have weighed on profitability.
The business has clearly expanded its top line since 2021, while gross profit has also increased. The weaker point is that selling, general, and administrative costs have absorbed a larger share of that growth, which helps explain why net income remains below earlier peak levels despite higher revenue.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Industrial Distribution | |
| Market Cap ⓘ | $3.94B | |
| Beta ⓘ | 1.39 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 24.75 | 22.10 |
| P/B Ratio ⓘ | 2.36 | 1.97 |
| FCF Yield ⓘ | 6.57% | 6.38% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 4.91% | 4.79% |
| PEG ⓘ | 2.52 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 4.70% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 8.29% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | -17.43% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 11.95% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -3.96% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 9.16% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | -39.24% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 8.98% | 10.84% |
| ROA (Latest) ⓘ | 4.79% | 5.41% |
| ROIC (5Y Median) ⓘ | 11.07% | 9.38% |
| ROA (5Y Median) ⓘ | 6.47% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 0.07 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.11 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.05 | 1.39 |
| Net Debt / Assets ⓘ | 0.52% | 19.28% |
| EBITDA / Interest ⓘ | 11.14 | 9.58 |
| Operating Margin (Latest) ⓘ | 5.28% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 5.82% | 10.29% |
| Debt to Equity (Latest) ⓘ | 6.26% | 65.48% |
| Profit Margin (Latest) ⓘ | 3.41% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $259.30M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -41.31% | +61.68% |
| 12M Return (excl. last month) ⓘ | -35.99% | +12.58% |
| 6M Return ⓘ | -35.03% | 0.00% |
| Price vs. 200-Day MA ⓘ | -24.49% | +0.02% |
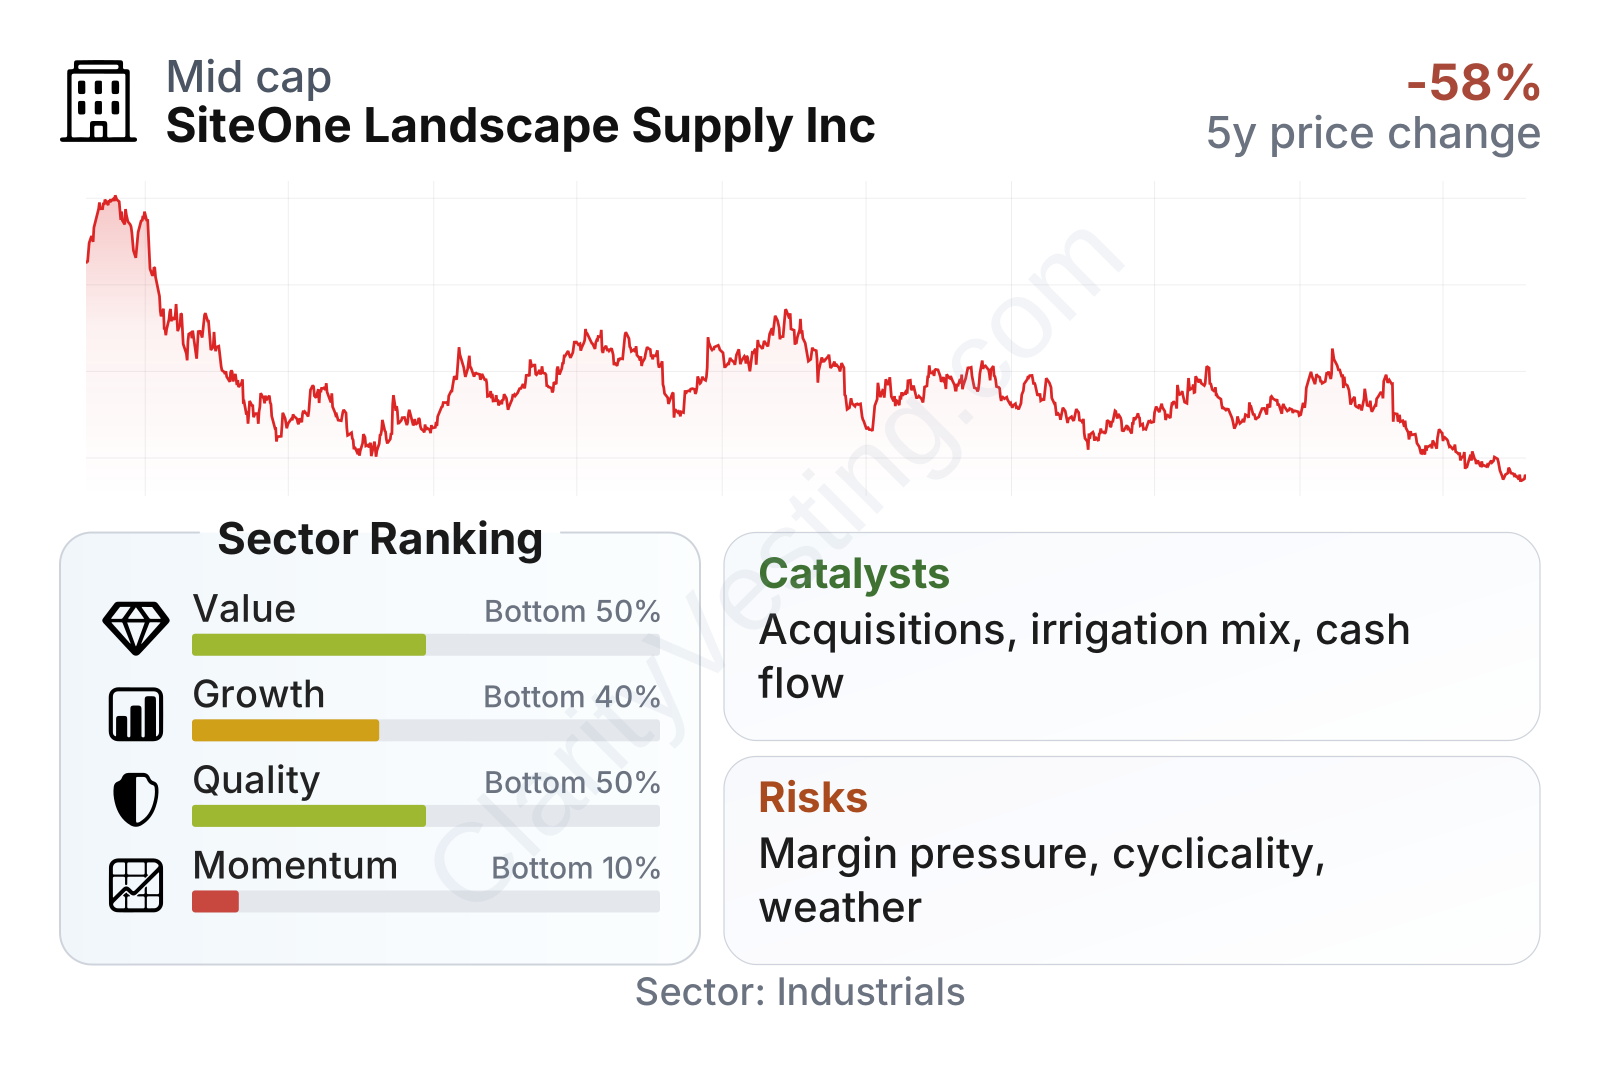
SiteOne is a mid-sized industrial distributor with a stock that has been much more volatile than the broader market, reflected in a beta above 1. On valuation, it sits around the sector middle to slightly above on earnings and book value, while cash flow yield is close to sector norms. The broader picture is more mixed: balance-sheet strength is a real positive, but growth, profitability, and stock-price momentum currently rank in the lower half of the sector, with momentum notably weak.
The share price history shows a stock that surged during the strong landscaping and housing cycle, then gave back much of that premium as earnings softened and the market reassessed growth expectations. That decline has reduced the valuation multiple from very elevated levels, but not to bargain-basement territory.
Growth
SiteOne operates in a market with attractive long-term drivers. Landscaping demand is tied to residential outdoor spending, commercial property maintenance, water-management needs, and repair-and-upkeep activity that tends to be steadier than new construction alone. In addition, population shifts, drought-related irrigation upgrades, and the ongoing preference for outdoor living spaces support a favorable long-run backdrop for many of the company’s product categories.
The company’s strategy also makes sense structurally. It combines organic growth with acquisitions, using its branch network to widen local coverage and add product depth. In fragmented distribution markets, scale can matter: larger buyers often negotiate better sourcing, carry broader inventory, and spread logistics and technology costs over more locations. SiteOne has spent years consolidating independent operators, which remains an important part of its expansion approach.
Recent revenue growth has remained positive, but the pace has slowed materially from the unusually strong post-2021 period. More recently, growth has been running in the low-single-digit range to mid-single-digit range, which suggests demand is still expanding but at a more normalized rate. That is an important distinction for long-term analysis: the company is still growing, yet no longer benefiting from the same powerful cyclical tailwinds that lifted results several years ago.
Cash generation remains one of the more encouraging elements. Free cash flow has stayed positive and has recovered from earlier swings, with trailing twelve-month free cash flow recently around a quarter of a billion dollars. For a distributor, this matters because cash flow supports branch investments, acquisitions, and resilience during weaker demand periods.
A practical catalyst for future growth is continued consolidation in landscape supply distribution. SiteOne’s scale, branch network, and category breadth leave room to keep acquiring smaller players and deepen customer relationships. Another catalyst is product mix: irrigation, hardscapes, and water-efficiency solutions can benefit from both maintenance demand and regulation-driven upgrades in certain geographies. Recent company communications have also emphasized operational initiatives and selective acquisitions, pointing to a business that is still expanding even while near-term end markets remain uneven.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


