Stock Analysis · Sinda Ltd (SIND)
Overview
Sinda Ltd is a small precious-metals mining company listed in the U.S. under the symbol SIND. Based on its public filings, the business is still at an early and highly speculative stage rather than operating as a mature producer with stable sales. The company is positioned in the precious metals and mining space, where value usually depends on securing mineral rights, advancing exploration or development assets, obtaining permits, arranging financing, and eventually bringing a project into production.
At this stage, Sinda does not appear to have meaningful operating revenue. Its recent financial profile suggests that the company is still spending on corporate overhead, project-related work, and financing costs while it develops its business plan and underlying assets.
Main sources of revenue currently appear to be:
- No meaningful reported operating revenue: recent annual figures indicate 0% from ongoing product sales or mining operations.
- Potential future revenue source: if projects are advanced successfully, revenue would likely come from the extraction and sale of precious metals or from monetizing project interests, but that is not yet visible in the latest reported income profile.
This is important for long-term readers: Sinda should currently be viewed more as a development-stage mining vehicle than as an established cash-generating operator.
The financial flow highlights a business with essentially no reported revenue in the last two annual periods, while operating expenses and administrative costs increased noticeably. Losses widened from 2024 to 2025, which means the current equity case depends heavily on future asset progress rather than present operating performance.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Precious Metals & Mining | |
| Market Cap ⓘ | $2.17B | |
| Beta ⓘ | N/A | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.90 |
| P/B Ratio ⓘ | 8.35 | 1.65 |
| FCF Yield ⓘ | -1.14% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | -1.59% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | N/A | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 5.51% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | N/A | 4.91% |
| ROIC (5Y Median) ⓘ | N/A | 7.70% |
| ROA (5Y Median) ⓘ | N/A | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | -92.17% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.34 |
| Operating Margin (Latest) ⓘ | N/A | 13.20% |
| Operating Margin (5Y Median) ⓘ | N/A | 11.80% |
| Debt to Equity (Latest) ⓘ | 0.50% | 40.56% |
| Profit Margin (Latest) ⓘ | N/A | 6.43% |
| Free Cash Flow (Latest) ⓘ | -$24.80M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +68.89% |
| 12M Return (excl. last month) ⓘ | N/A | +30.21% |
| 6M Return ⓘ | N/A | -4.16% |
| Price vs. 200-Day MA ⓘ | N/A | -1.27% |
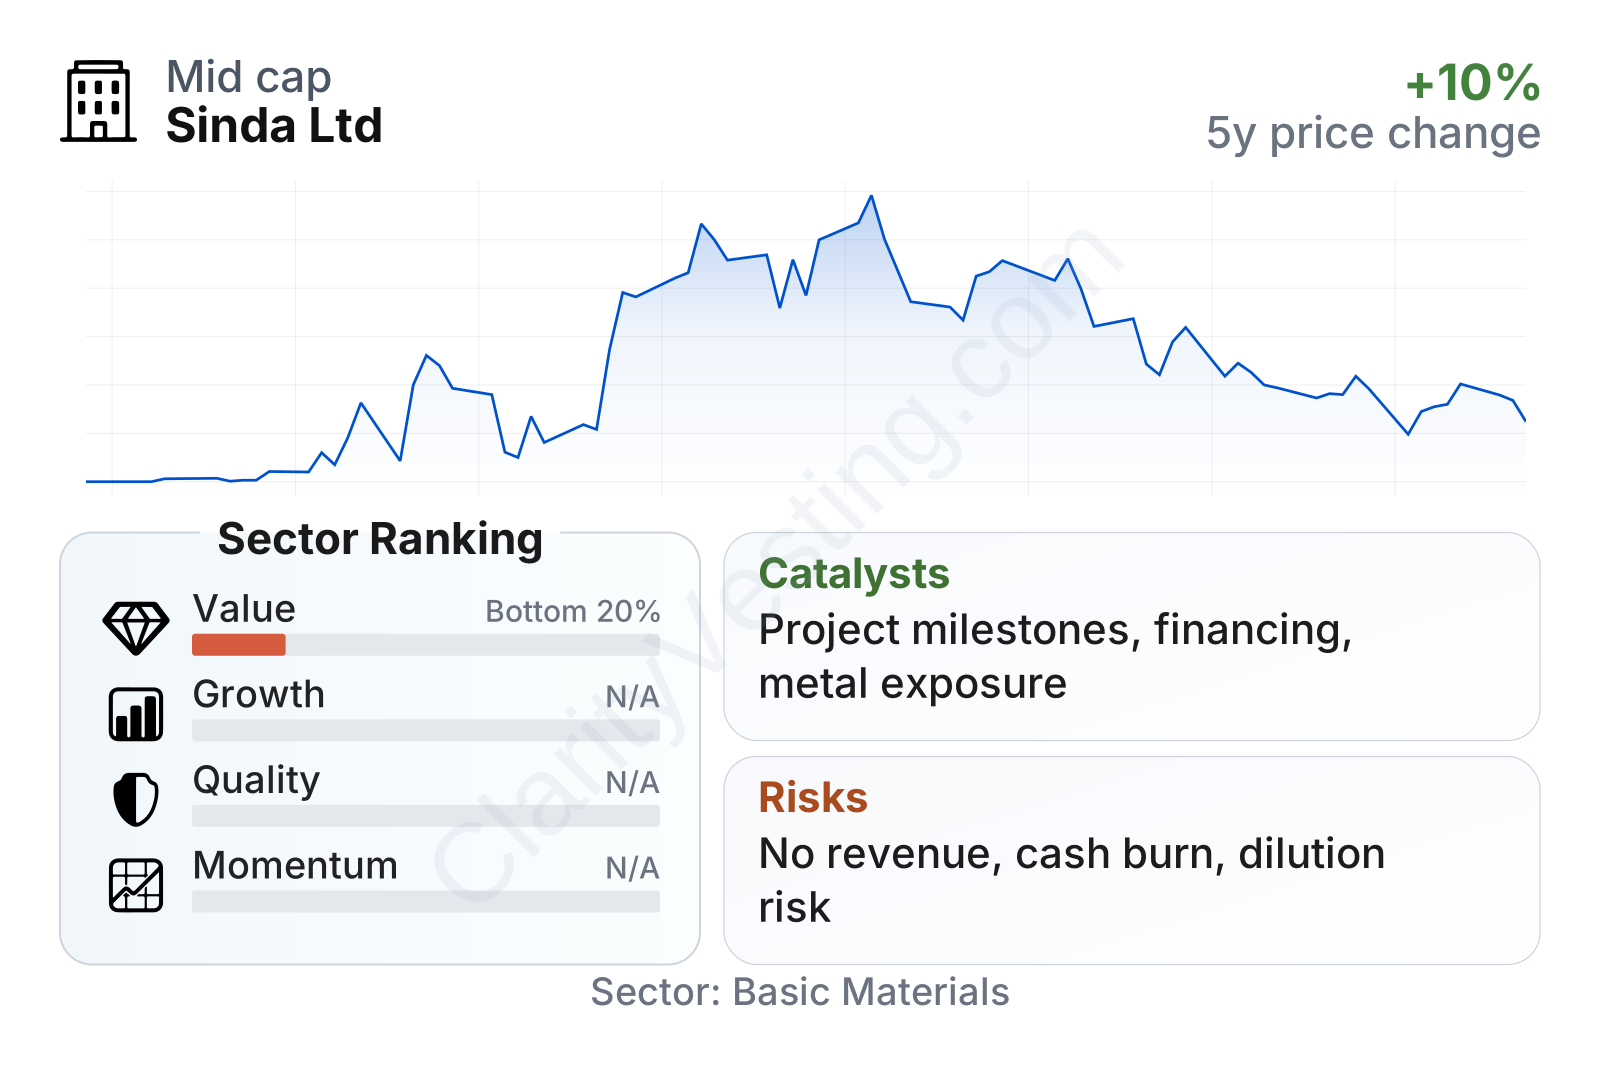
The market value places Sinda in the small-cap range, which often comes with higher volatility and heavier dependence on external financing. The stock has moved up over the most recent months, but the underlying fundamentals remain weak: valuation measures rank in the lower end of the sector, free cash flow is negative, and the company is not currently generating earnings or operating profit. On the other hand, balance-sheet leverage looks very light, with debt to equity close to 0% and net cash standing out versus many mining peers. In simple terms, the company has limited financial debt pressure, but it also lacks the operating results that would normally support a premium valuation.
Growth
The broader precious-metals sector can benefit from several long-term forces: demand for gold and other precious metals as stores of value, central-bank buying, inflation hedging, and periodic investor interest during times of economic uncertainty. For a small company like Sinda, however, sector growth alone is not enough. The real question is whether it can turn its asset base into a producing or otherwise monetizable business.
Sinda’s strategy only makes sense for future growth if it can move from a pre-revenue structure to tangible project advancement. In mining, that usually means proving resource quality, improving technical studies, securing permits, controlling development costs, and funding the next stages without excessive shareholder dilution. Because Sinda currently shows no operating revenue, future upside depends much more on company-specific execution than on commodity prices alone.
A potential catalyst exists if management can announce measurable progress on project development, partnerships, acquisitions, or resource-definition milestones. In this part of the market, even early operational steps can change how the market values a company, especially when the starting base is small. The recent rise in the share price over the last few months suggests that the market may already be anticipating some improvement or speculative interest, although that is not yet supported by reported revenue growth.
No single recent public development from the company appears, from the materials reviewed, to conclusively establish a major commercial breakthrough. That means the growth case remains possible, but still largely dependent on future execution rather than already-demonstrated business traction.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


