Stock Analysis · SEB SA (SEBYY)
Overview
SEB SA is a French small domestic equipment group best known for household appliances and cookware sold around the world. Its portfolio includes kitchen electrics, coffee machines, food preparation products, garment care, home cleaning devices, cookware, and professional coffee equipment. The company operates through a broad brand stable that includes Tefal, Moulinex, Rowenta, Krups, WMF, and several regional brands, which helps it reach different price points and geographies.
Revenue is mainly generated from consumer small domestic equipment, with additional contributions from cookware and from the professional segment. Based on the group’s business mix described in annual reporting, the largest sources of revenue are approximately:
- Consumer small domestic equipment: about 70% to 75% — kitchen appliances, coffee machines, food prep, ironing, garment care, and home cleaning products.
- Cookware and kitchenware: about 15% to 20% — non-stick pans, pots, pressure cookers, and related kitchen items, mainly under brands such as Tefal and WMF.
- Professional and other activities: about 10% to 15% — especially professional coffee equipment and adjacent operations.
Geographically, SEB is highly international, with Europe still important but with sizable exposure to Asia, the Americas, and emerging markets. That diversification matters because demand for small appliances tends to move with consumer confidence, housing activity, replacement cycles, and premiumization trends rather than with a single local economy.
Over the last several years, revenue has stayed broadly stable around the low-single-digit billions of euros, while profit conversion has been less stable. Gross profit has held up relatively well, but operating and net income have been more pressured by higher operating costs and financing costs. That pattern suggests the business still has pricing power and brand relevance, but margin execution has been uneven.
The operating profile shows a company with resilient sales but more volatile earnings. Gross profit has remained relatively solid over time, yet the share of revenue reaching net income has narrowed, reflecting heavier expense pressure and higher interest costs than a few years ago.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Furnishings, Fixtures & Appliances | |
| Market Cap ⓘ | $3.83B | |
| Beta ⓘ | 1.24 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 27.92 | 17.04 |
| P/B Ratio ⓘ | 1.35 | 1.61 |
| FCF Yield ⓘ | 17.95% | 9.02% |
| Dividend Yield ⓘ | 4.65% | 2.75% |
| EBIT / EV ⓘ | N/A | 6.69% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -0.10% | 5.60% |
| RPS Growth (5Y CAGR) ⓘ | 0.02% | 9.04% |
| EPS Growth (5Y CAGR) ⓘ | -39.03% | -17.44% |
| BVPS Growth (5Y CAGR) ⓘ | -0.30% | 5.73% |
| Margin Growth (5Y Trend) ⓘ | -1.75% | -0.26% |
| FCF Growth (5Y CAGR) ⓘ | -50.63% | 4.91% |
| DPS Growth (5Y CAGR) ⓘ | 12.81% | 10.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.00% | 12.38% |
| ROA (Latest) ⓘ | 2.65% | 5.54% |
| ROIC (5Y Median) ⓘ | 6.59% | 10.63% |
| ROA (5Y Median) ⓘ | 3.28% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 2.49 | 2.16 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.07 | 2.31 |
| Net Debt / EBITDA (Latest) ⓘ | 1.61 | 1.52 |
| Net Debt / Assets ⓘ | 27.20% | 21.74% |
| EBITDA / Interest ⓘ | 8.21 | 9.06 |
| Operating Margin (Latest) ⓘ | 6.23% | 9.12% |
| Operating Margin (5Y Median) ⓘ | 6.85% | 9.56% |
| Debt to Equity (Latest) ⓘ | 113.36% | 76.18% |
| Profit Margin (Latest) ⓘ | 1.47% | 5.30% |
| Free Cash Flow (Latest) ⓘ | $687.40M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -31.25% | +11.77% |
| 12M Return (excl. last month) ⓘ | -29.44% | +0.61% |
| 6M Return ⓘ | +35.64% | +1.32% |
| Price vs. 200-Day MA ⓘ | +30.36% | -3.47% |
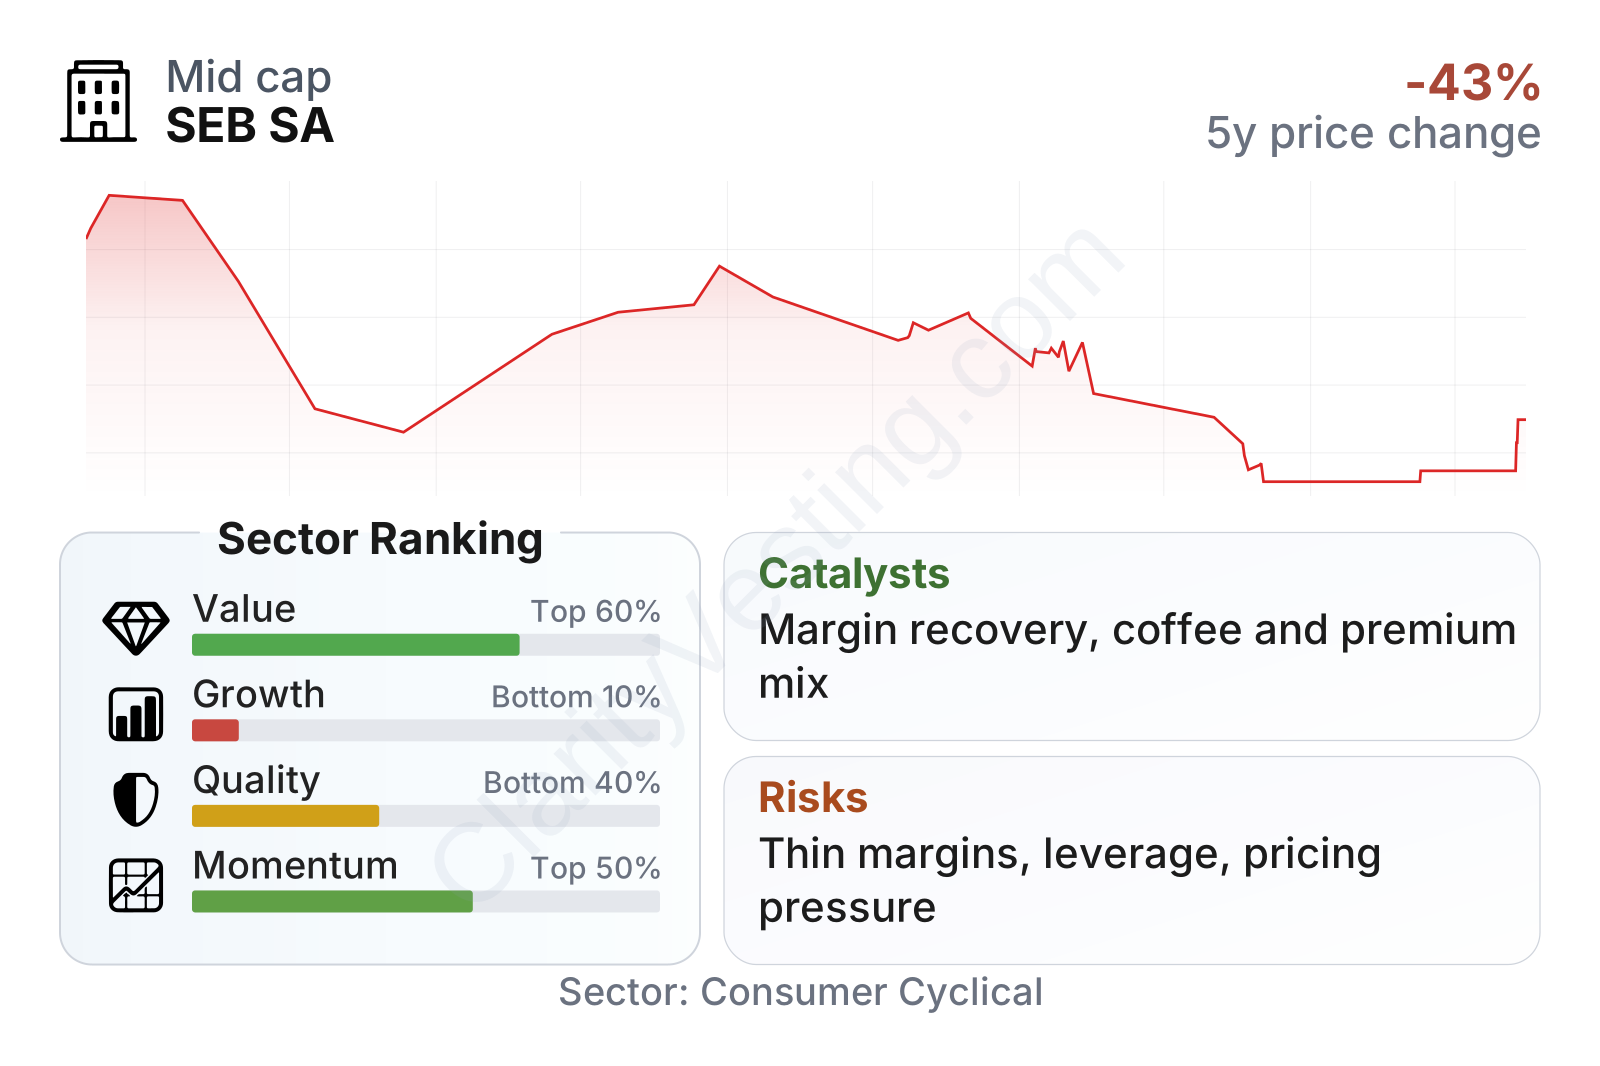
SEB is a mid-sized public company with a dividend yield above much of its sector and a free cash flow yield that looks strong on a trailing basis. At the same time, growth metrics are weak relative to peers, with revenue roughly flat recently and longer-term earnings trends under pressure. Profitability is also below sector medians on several measures, especially profit margin and operating margin, while leverage is somewhat elevated. Market performance has been mixed: the shares remain well below levels seen several years ago, but the more recent six-month rebound indicates sentiment has improved from depressed levels.
Growth
SEB operates in categories that are mature in developed markets but still supported by several long-term demand drivers. Households continue to replace appliances over time, consumers increasingly look for convenience in cooking and cleaning, and coffee remains one of the more attractive appliance ecosystems because it can create recurring accessory and machine replacement demand. Premiumization also matters: branded products with better design, durability, and energy performance tend to defend pricing better than low-end commoditized products.
The company’s strategy broadly makes sense for future growth because it combines global brands, exposure to everyday-use categories, and a mix of consumer and professional channels. Its large installed brand base gives it room to launch product upgrades, connected devices, and higher-value ranges rather than depending only on unit growth. Professional coffee equipment is another useful angle because it adds exposure beyond retail shelves and can benefit from hospitality and office demand.
A meaningful catalyst is the company’s ability to improve margins rather than simply increase sales. Revenue has been relatively steady, so even moderate gains in operating efficiency, sourcing, mix, and pricing could have an outsized effect on earnings. The recent revenue path suggests demand has not collapsed; the bigger question is whether management can convert that demand into more consistent profitability.
Another supportive element is geographic breadth. If some developed markets remain soft, emerging markets and category expansion can still provide pockets of growth. SEB also has a long history of integrating brands and using scale in distribution, manufacturing, and procurement, which can help support future launches and cross-selling.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


