Stock Analysis · Southern Copper Corporation (SCCO)
Overview
Southern Copper Corporation is one of the world’s largest integrated copper producers. The company mines, smelts, refines, and sells copper and also produces several by-products that naturally come out of its ore bodies. Its main operations are in Peru and Mexico, and its controlling shareholder is Grupo México. That structure matters because SCCO is not just a miner extracting raw rock: it controls a large part of the value chain, from mining to processing, which helps it manage costs and capture more value when copper markets are favorable.
Copper is the core of the business by a wide margin, but Southern Copper’s revenue is diversified by valuable by-products. Based on the company’s recent annual reporting, sales are roughly distributed as follows:
- Copper: approximately 78% to 82% of revenue. This includes refined copper, copper cathodes, rods, and other copper products sold to industrial customers.
- Molybdenum: approximately 7% to 10%. Molybdenum is used mainly in steel alloys and tends to provide an additional earnings lever beyond copper prices.
- Silver: approximately 4% to 7%. Silver is an important by-product from several mines and can materially support margins when precious metals prices are firm.
- Zinc and other by-products: approximately 2% to 5%. This smaller category can include zinc, sulfuric acid, and other outputs tied to mining and processing activities.
Geographically, Southern Copper is heavily concentrated in Peru and Mexico. That gives it exposure to large, long-life ore bodies, but it also means operating results are tied to political, environmental, labor, and permitting conditions in those two countries.
One of the most attractive features of the business is its cost structure. Southern Copper has historically reported very strong profitability compared with much of the broader materials sector, supported by high-grade assets, by-product credits, and integrated operations. Over the last few years, revenue and profit have moved up and down with copper prices, but the company has remained strongly profitable through the cycle.
The financial flow over recent years shows a business with unusually strong gross and operating profitability for a miner. Revenue dipped in 2022 and 2023, then recovered sharply in 2024 and 2025, while operating costs stayed relatively contained. That combination points to meaningful operating leverage when copper markets improve.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 04, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Copper | |
| Market Cap ⓘ | $173.55B | |
| Beta ⓘ | 1.15 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 30.86 | 17.61 |
| P/B Ratio ⓘ | 13.57 | 1.78 |
| FCF Yield ⓘ | 3.44% | 5.86% |
| Dividend Yield ⓘ | 1.77% | 2.07% |
| EBIT / EV ⓘ | 5.26% | 6.43% |
| PEG ⓘ | 5.41 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 40.60% | 11.30% |
| RPS Growth (5Y CAGR) ⓘ | 3.15% | 4.46% |
| EPS Growth (5Y CAGR) ⓘ | 5.64% | -13.11% |
| BVPS Growth (5Y CAGR) ⓘ | 5.75% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -2.06% | -1.57% |
| FCF Growth (5Y CAGR) ⓘ | 0.20% | 0.55% |
| DPS Growth (5Y CAGR) ⓘ | -1.89% | 6.02% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 31.28% | 9.31% |
| ROA (Latest) ⓘ | 25.49% | 4.94% |
| ROIC (5Y Median) ⓘ | 24.71% | 7.91% |
| ROA (5Y Median) ⓘ | 19.06% | 3.93% |
| Net Debt / EBIT (Latest) ⓘ | 0.32 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.74 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.29 | 0.91 |
| Net Debt / Assets ⓘ | 11.87% | 13.69% |
| EBITDA / Interest ⓘ | 27.48 | 11.93 |
| Operating Margin (Latest) ⓘ | 57.24% | 13.07% |
| Operating Margin (5Y Median) ⓘ | 49.78% | 11.86% |
| Debt to Equity (Latest) ⓘ | 67.52% | 40.43% |
| Profit Margin (Latest) ⓘ | 35.87% | 6.57% |
| Free Cash Flow (Latest) ⓘ | $5.97B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +220.50% | +65.06% |
| 12M Return (excl. last month) ⓘ | +120.34% | +35.57% |
| 6M Return ⓘ | +18.00% | +1.69% |
| Price vs. 200-Day MA ⓘ | +12.89% | +0.95% |
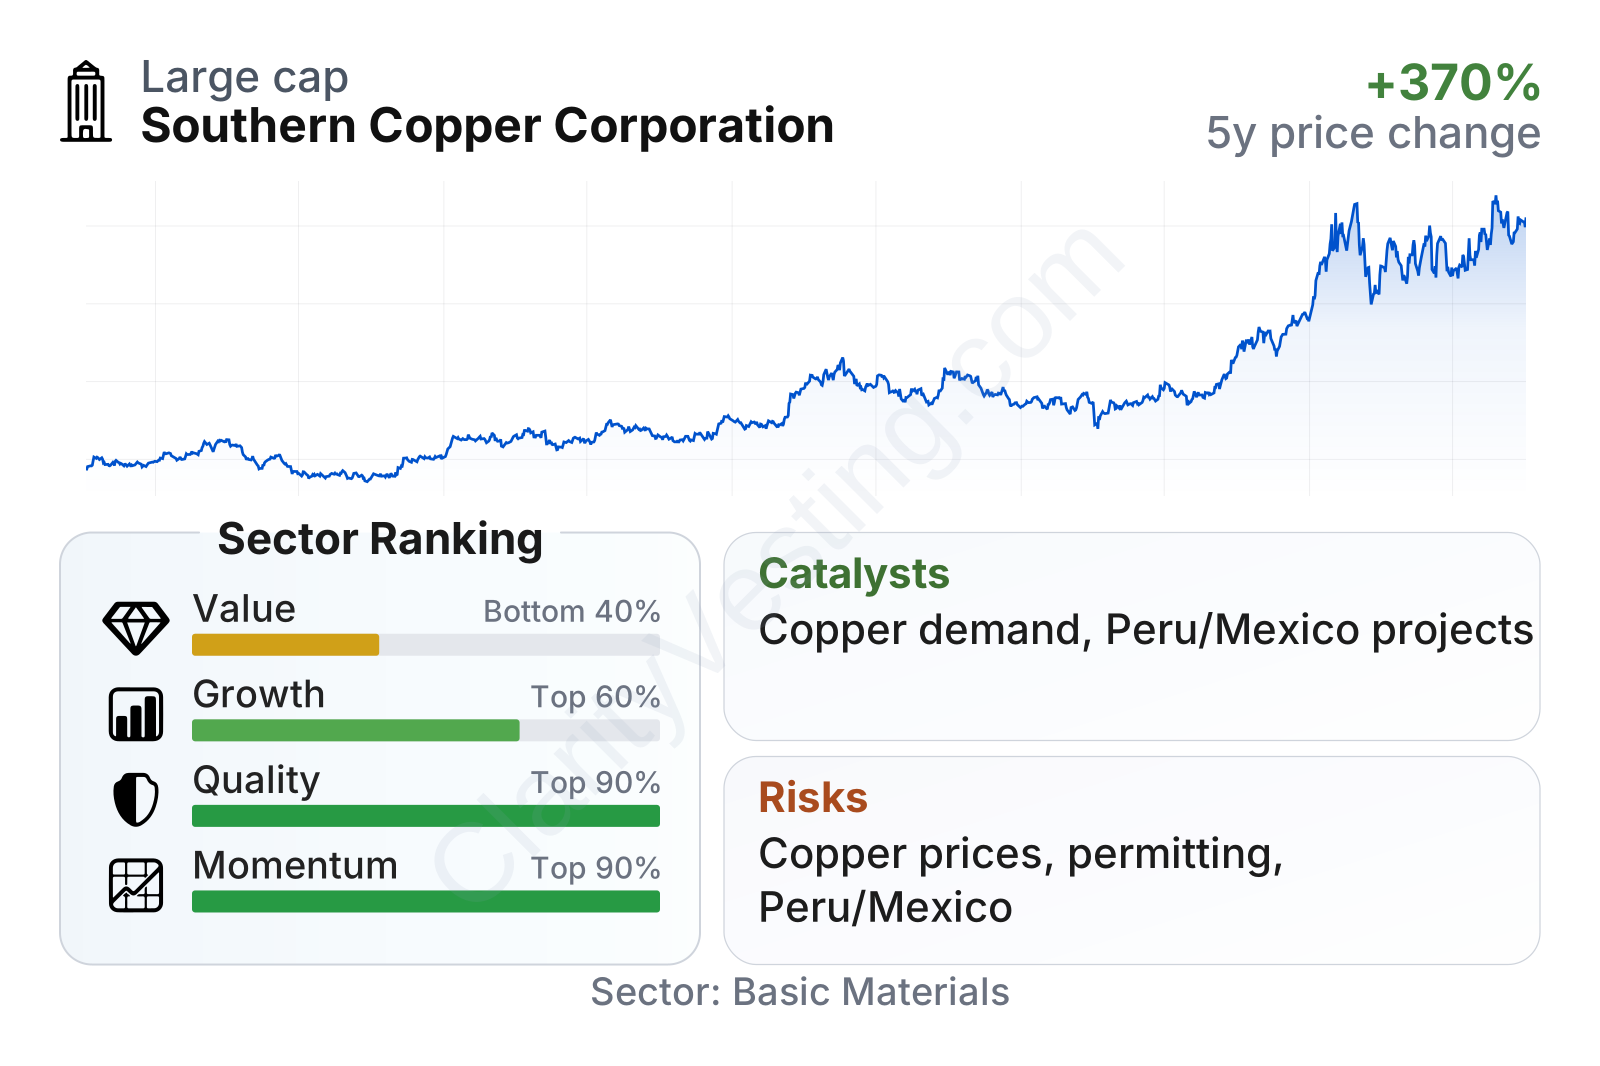
Southern Copper is a very large copper producer with moderate share-price volatility for a mining stock, as shown by a beta a little above 1. The most striking element in the metrics is the gap between quality and valuation. Profitability, returns on capital, and interest coverage rank among the strongest in the sector, while valuation measures sit in the weaker half because the market is already assigning a premium multiple to those strengths.
The stock’s recent price performance has been powerful over one, three, and shorter time frames, which fits the broader rebound in copper expectations and company earnings. At the same time, the dividend yield has compressed as the share price climbed, so the income profile looks less generous than it did a few years ago.
Growth
Southern Copper operates in a sector with a strong long-term demand backdrop. Copper is a foundational metal for power grids, construction, electric vehicles, renewable energy systems, data centers, and industrial equipment. Even though copper demand can be cyclical in the short run, the longer-term case is supported by electrification and the need to expand transmission and energy infrastructure. That makes the sector structurally attractive, especially for producers that already own large reserves and expansion options.
The company’s strategy is straightforward and sensible: protect its low-cost asset base, increase output from existing districts, and advance a pipeline of brownfield and greenfield projects in Peru and Mexico. In mining, future growth often depends less on marketing or product launches and more on ore quality, reserve life, infrastructure, and permits. Southern Copper stands out because it already has scale, processing capacity, and a long inventory of projects linked to established mining regions.
Revenue growth has been volatile, which is normal for a commodity producer, but the latest pattern is clearly stronger. Recent year-over-year growth has accelerated into the mid-30% to low-40% range, well above the sector median. That suggests the current upcycle is being driven not only by favorable pricing but also by solid operating performance.
Cash generation has also improved materially. Free cash flow had fallen closer to the $2 billion range during the softer period, then recovered to above $4 billion, and the latest trailing level is near $6 billion. For a capital-intensive miner, that matters because free cash flow funds expansion, dividends, debt management, and resilience during weaker commodity periods.
A major catalyst is the global copper supply picture. Large new copper projects are difficult to permit and build, and the industry faces declining ore grades in many regions. If demand keeps rising while supply remains tight, established producers with expansion-ready assets could benefit disproportionately. Southern Copper is well placed in that context because it already controls large reserves and has a development pipeline rather than needing to buy growth at high prices.
Recent company communications have also continued to emphasize project development and production expansion in Peru and Mexico. For long-term analysis, that is more important than quarter-to-quarter market noise: the company is trying to convert strong industry conditions into lasting production growth.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


