Stock Analysis · SBM Offshore NV (SBFFY)
Overview
SBM Offshore is a Dutch company that designs, builds, finances, installs, and operates offshore floating production systems for the oil and gas industry. Its best-known products are FPSOs, or floating production, storage and offloading vessels. These are large ships or ship-shaped units used to process oil and gas at sea and store crude before it is transferred to tankers. In practice, SBM Offshore helps energy companies develop offshore fields without needing fixed production platforms in deep water.
The business model is different from many traditional equipment suppliers because SBM Offshore often keeps ownership stakes in the assets it builds and then earns long-term lease and operation income over many years. That makes part of its revenue more recurring and contract-based than a simple one-time construction model.
Based on recent annual reporting, revenue is mainly split between long-duration lease and operate contracts and turnkey construction activities. A simple way to think about the mix is:
- Lease and Operate: approximately 70% to 80% of revenue in recent years. This includes day-rate style income from FPSOs and related offshore units under long-term contracts, plus operation and maintenance services.
- Turnkey / Construction: approximately 20% to 30% of revenue in recent years. This covers engineering, procurement, construction, and installation work for new offshore production systems.
- Other activities: a small share. This can include smaller services, technology work, and emerging low-carbon initiatives.
Geographically, the company is exposed to major deepwater oil regions, especially Brazil, Guyana, and West Africa. This matters because these areas remain among the most active offshore development zones globally, and they are exactly where large floating systems are needed.
Another important point for long-term readers is that SBM Offshore is not trying to compete across every part of oilfield services. It is specialized. The company focuses on a narrow but technically demanding niche where experience, project execution, and customer trust matter a great deal.
The long-term picture shows a business that has lifted revenue from roughly $3.7 billion in 2021 to about $5.9 billion in 2025, while operating profit expanded even faster. The main distortion has been heavy interest expense, which can sharply reduce net income even when operations remain strong. That is a key theme for understanding both the opportunity and the risk.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Equipment & Services | |
| Market Cap ⓘ | $6.60B | |
| Beta ⓘ | 0.65 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 7.50 | 15.40 |
| P/B Ratio ⓘ | 2.92 | 1.71 |
| FCF Yield ⓘ | 70.98% | 8.24% |
| Dividend Yield ⓘ | 2.94% | 3.52% |
| EBIT / EV ⓘ | 23.58% | 7.45% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -1.90% | 26.85% |
| RPS Growth (5Y CAGR) ⓘ | 13.58% | 6.78% |
| EPS Growth (5Y CAGR) ⓘ | 43.48% | -14.41% |
| BVPS Growth (5Y CAGR) ⓘ | -1.15% | 6.08% |
| Margin Growth (5Y Trend) ⓘ | 13.97% | 0.55% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 2.75% |
| DPS Growth (5Y CAGR) ⓘ | 13.09% | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 20.83% | 11.30% |
| ROA (Latest) ⓘ | 7.54% | 6.00% |
| ROIC (5Y Median) ⓘ | 7.83% | 10.35% |
| ROA (5Y Median) ⓘ | 3.09% | 5.46% |
| Net Debt / EBIT (Latest) ⓘ | 1.95 | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | 7.50 | 1.82 |
| Net Debt / EBITDA (Latest) ⓘ | 1.87 | 1.08 |
| Net Debt / Assets ⓘ | 35.32% | 17.29% |
| EBITDA / Interest ⓘ | 2.17 | 9.53 |
| Operating Margin (Latest) ⓘ | 26.98% | 16.21% |
| Operating Margin (5Y Median) ⓘ | 23.01% | 20.55% |
| Debt to Equity (Latest) ⓘ | 159.52% | 52.27% |
| Profit Margin (Latest) ⓘ | 15.82% | 8.79% |
| Free Cash Flow (Latest) ⓘ | $4.69B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +266.65% | +68.93% |
| 12M Return (excl. last month) ⓘ | +70.01% | +42.90% |
| 6M Return ⓘ | -0.62% | +9.18% |
| Price vs. 200-Day MA ⓘ | +29.13% | +9.87% |
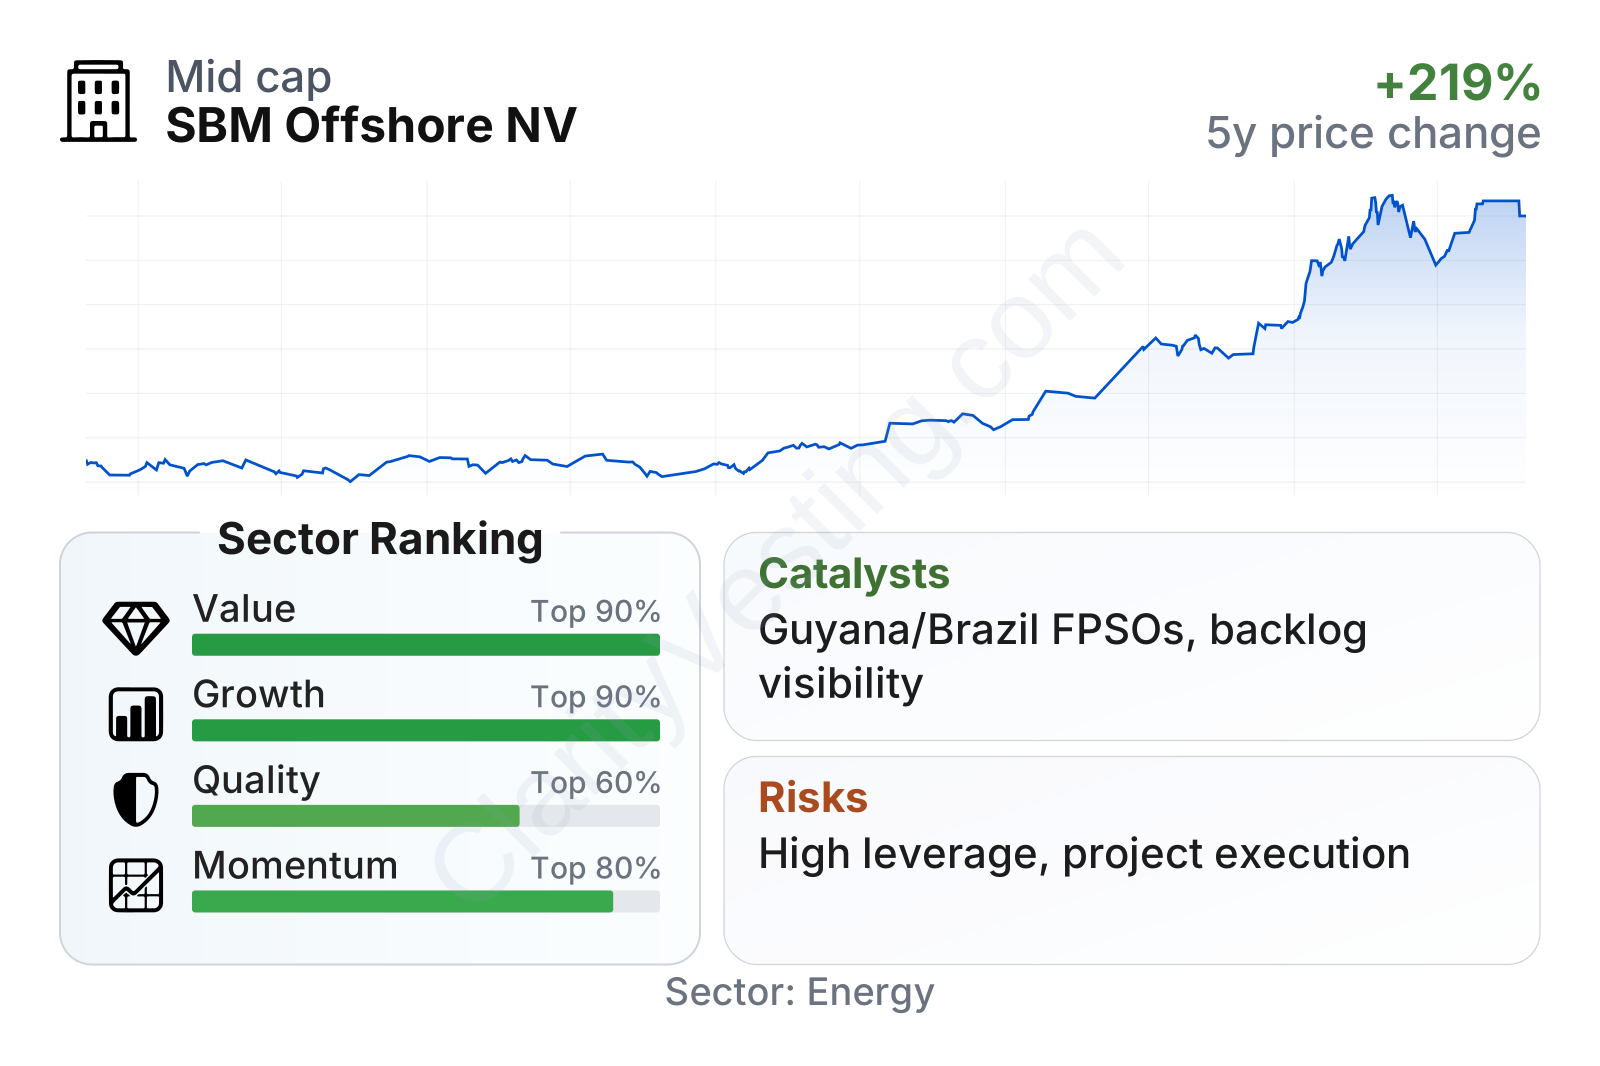
SBM Offshore screens as strong on value, solid on quality, and favorable on growth and momentum versus much of the energy equipment group. The valuation multiples are low compared with sector medians, while operating margins and returns on capital are clearly above average. The main caveat is leverage: debt-related metrics and interest coverage are weaker than the broader sector, so the business looks financially efficient at the operating level but more stretched once financing costs are considered.
The stock performance has also been unusually strong over the last few years, moving from the low teens in late 2021 to above $40 by April 2026. That kind of rerating usually means the market has already recognized a large part of the company’s operational improvement, so future returns are likely to depend more on execution, backlog conversion, and cash generation than on multiple expansion alone.
Growth
SBM Offshore operates in a part of the energy industry that remains active despite the broader push toward decarbonization. Deepwater oil projects are still being sanctioned because large offshore fields can deliver high volumes over long production lives. In several basins, especially Brazil and Guyana, floating production systems remain essential infrastructure rather than optional equipment. That gives SBM Offshore exposure to a segment that can still grow even when other oil and gas spending categories become less predictable.
The company’s strategy also makes sense for future expansion. Instead of depending only on one-off construction revenue, it keeps building a portfolio of long-term lease assets. This approach can create steadier cash flow, better visibility, and a stronger relationship with large customers. It also raises the barrier for competitors because financing, operating know-how, and project management all have to work together.
Near-term growth has not been perfectly smooth. Revenue growth turned negative in parts of 2023 and 2024 before accelerating again in 2025. That pattern is typical for project-driven businesses, where timing of construction milestones can move revenue from one period to another. More important than any single year is the broader trend: over five years, revenue per share grew at a double-digit annual pace, earnings per share increased much faster, and operating margins improved materially.
A major catalyst is the company’s position in the FPSO order cycle. Large offshore developments usually require years of planning, and once a project is awarded, the revenue stream can last for decades through lease and operation agreements. Recent company updates have continued to emphasize a large backlog and strong visibility from existing contracts. In practical terms, that means a meaningful share of future business is already tied to assets that are built, under construction, or contractually committed.
Another growth angle is selective expansion beyond traditional oil production. SBM Offshore has been developing activities in floating offshore energy solutions, including technologies linked to cleaner energy infrastructure. These businesses are still small relative to the core FPSO franchise, so they do not change the investment case today, but they may gradually widen the company’s addressable market over time.
Recent corporate communications also point to ongoing progress on major projects such as FPSOs for ExxonMobil-related developments in Guyana and Petrobras-linked developments in Brazil. Those regions are among the most attractive offshore areas globally, and continued activity there could support new awards, additional lease income, and a longer runway for fleet growth.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


