Stock Analysis · Revvity Inc (RVTY)
Overview
Revvity is a healthcare tools and diagnostics company focused on helping researchers, laboratories, and clinicians detect disease, analyze biological samples, and develop new therapies. The company was renamed from PerkinElmer after separating its applied, food, and enterprise services businesses, which left Revvity more concentrated on life sciences and diagnostics. Today, its business is tied to areas such as reproductive health screening, immunodiagnostics, life science reagents, cellular imaging, and software used in laboratories.
Its revenue mainly comes from two operating segments. Based on the latest annual reporting structure, the mix is approximately as follows:
- Life Sciences and Diagnostics, around 75% to 80% of revenue: instruments, reagents, assays, imaging systems, informatics, and workflow tools used by pharmaceutical companies, biotechnology firms, academic labs, and clinical laboratories.
- Analytical Solutions, around 20% to 25% of revenue: detection, testing, and laboratory instruments used in specialized industrial and scientific applications, although this is now a smaller piece of the company after the portfolio reshaping.
Within the healthcare-focused activities that now define Revvity, recurring revenue from consumables, reagents, assays, and services is especially important because customers need these products repeatedly after instrument placement. That tends to make the business steadier than a pure equipment model. Revenue is also geographically diversified, with meaningful exposure to the United States, Europe, and Asia.
The business mix has changed materially in recent years. Revenue peaked at a much higher level during the pandemic period and then fell back as COVID-related demand normalized and the company streamlined its portfolio. More recently, sales appear to have stabilized and returned to modest growth, while gross profit recovered from the 2023 trough. That makes Revvity look less like a pandemic winner in decline and more like a diagnostics and research platform trying to rebuild a cleaner base.
The broad pattern is a sharp revenue and profit reset after 2021, followed by stabilization. Gross profit improved in 2025 even though net income remained below earlier peak levels, showing that the company has recovered part of its operating strength but has not fully returned to its prior earnings profile.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Diagnostics & Research | |
| Market Cap ⓘ | $17.48B | |
| Beta ⓘ | 1.06 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 74.58 | 25.42 |
| P/B Ratio ⓘ | 2.43 | 3.08 |
| FCF Yield ⓘ | 3.20% | 3.12% |
| Dividend Yield ⓘ | 0.18% | 1.85% |
| EBIT / EV ⓘ | 1.95% | 0.56% |
| PEG ⓘ | 0.73 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1.30% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | -6.36% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -26.77% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | 1.14% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | -21.49% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | -21.09% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | 1.09% | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 3.10% | 3.17% |
| ROA (Latest) ⓘ | 1.96% | 2.98% |
| ROIC (5Y Median) ⓘ | 3.27% | 4.56% |
| ROA (5Y Median) ⓘ | 2.28% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 6.54 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 5.48 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 3.02 | 1.00 |
| Net Debt / Assets ⓘ | 19.25% | 5.06% |
| EBITDA / Interest ⓘ | 8.16 | 9.55 |
| Operating Margin (Latest) ⓘ | 12.18% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 14.97% | 7.33% |
| Debt to Equity (Latest) ⓘ | 46.23% | 26.68% |
| Profit Margin (Latest) ⓘ | 8.16% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $559.34M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +55.00% | +51.61% |
| 12M Return (excl. last month) ⓘ | +66.58% | +19.90% |
| 6M Return ⓘ | +67.01% | +10.10% |
| Price vs. 200-Day MA ⓘ | +42.87% | +6.44% |
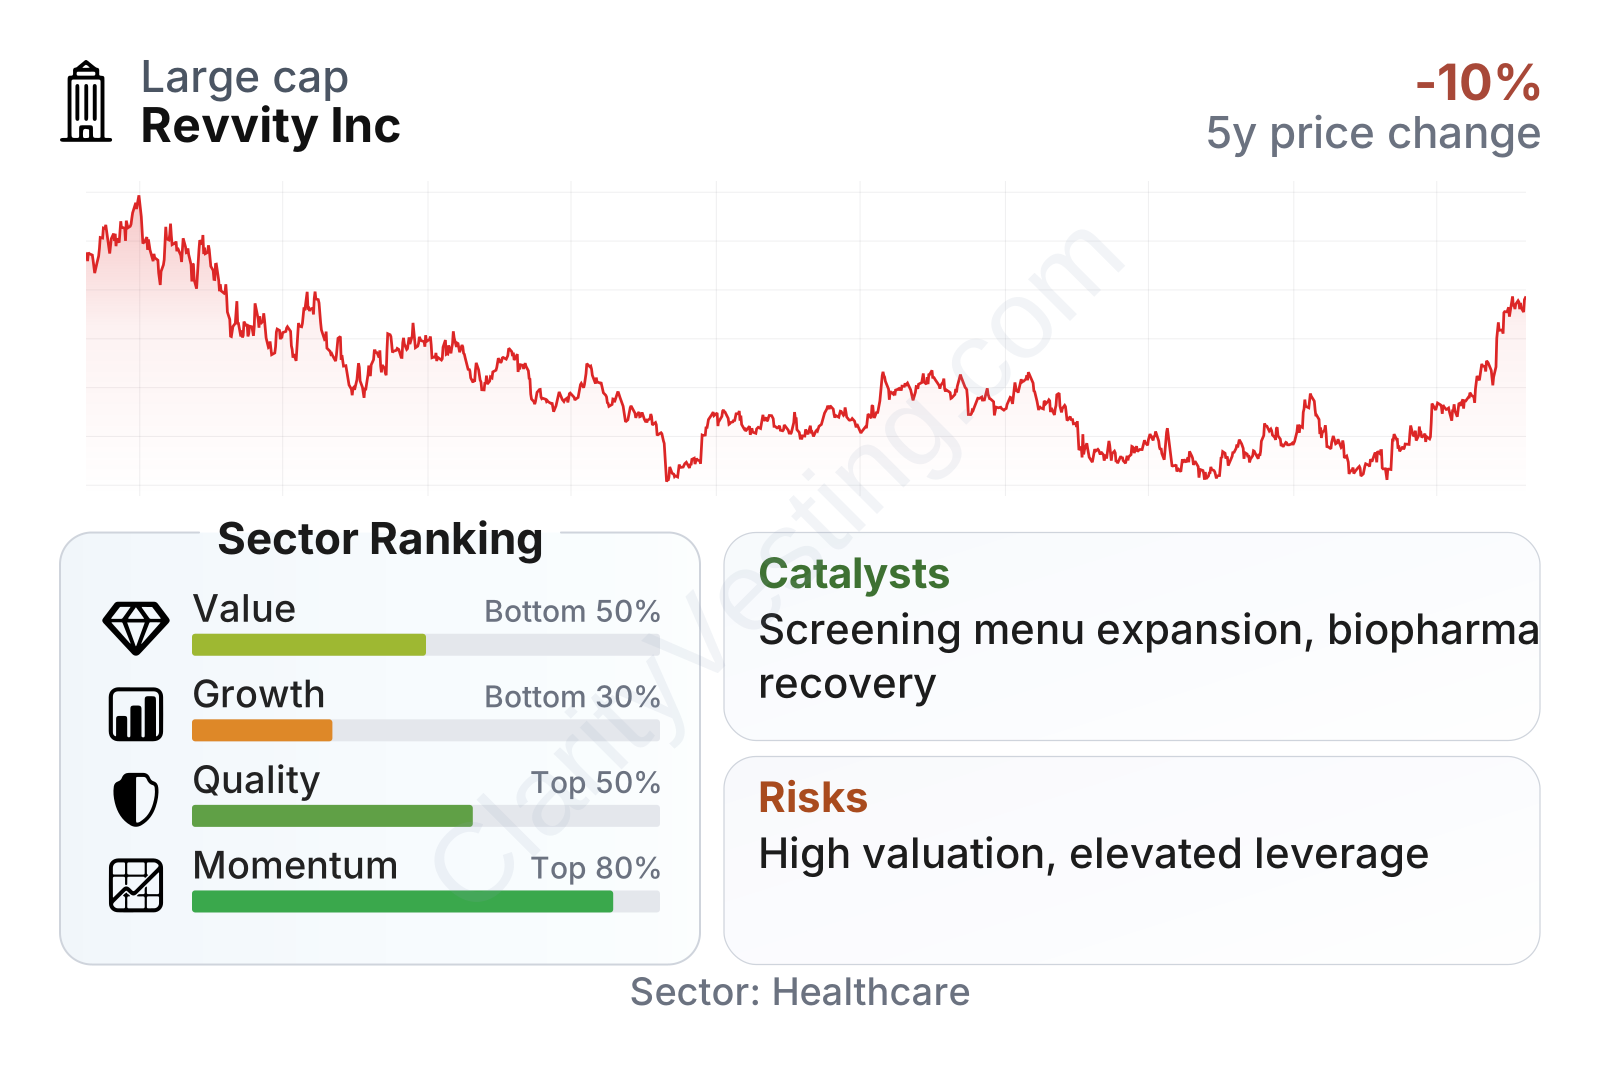
Revvity is a large diagnostics and research tools company with a market value in the mid-sized large-cap range for healthcare. The share price has been volatile over the last several years: it dropped heavily from 2021 through 2024, then rebounded strongly in the most recent period. In the factor breakdown, quality and momentum are stronger than growth and value. Profitability remains above the sector median on margins, but revenue growth, earnings growth, and balance-sheet leverage are less favorable. The valuation picture is mixed: cash flow yield and asset-based valuation are not extreme, but the earnings multiple is well above the sector median.
Growth
Revvity operates in an attractive long-term sector. Diagnostics, life science tools, and bioprocessing-related research benefit from aging populations, broader testing, drug development activity, precision medicine, and the increasing use of automation and data in laboratories. These are durable trends rather than short-lived themes.
The main question is not whether the sector can grow, but whether Revvity can grow faster than it has in the recent past. The company’s recent record is weak on a multi-year basis because it had to work through the post-pandemic reset. Revenue per share and earnings trends over five years still look soft, and that puts Revvity behind many healthcare peers. However, the shorter-term trend is better than the longer-term one. Year-over-year revenue moved from repeated declines in 2022 and 2023 to low single-digit growth in 2024 and 2025, with a stronger start to 2026 before growth slowed again in the latest quarter.
This suggests the business may have already passed its hardest comparison period. For long-term analysis, that matters because a company coming out of a reset can sometimes show cleaner progress than a company still digesting excess pandemic demand.
Strategy also supports that possibility. Revvity has been emphasizing higher-value diagnostics, reproductive health, immunodiagnostics, specialized life science tools, and software-enabled workflows. These tend to be areas where customers care more about performance, reliability, regulation, and installed-base compatibility than simply the lowest price. The company has also been active in acquisitions aimed at expanding its menu of tests and its exposure to faster-growing specialty segments.
One useful sign is cash generation. Free cash flow fell sharply from the unusually strong pandemic period, but it has recovered meaningfully from the 2024 low and remains solid in absolute dollars. That gives Revvity room to keep investing in product development, acquisitions, and debt reduction at the same time.
Among the more important catalysts are continued recovery in biopharma and academic research spending, the expansion of newborn screening and reproductive health testing menus, and further integration of software with instruments and assays. A stronger product cycle in diagnostics and life sciences could also help because recurring consumables revenue tends to rise after new systems are placed with customers.
Recent company updates have also highlighted ongoing portfolio refinement and tuck-in acquisitions in diagnostics and research tools, which fit the strategy of building deeper positions in specialized niches rather than chasing broad volume alone. For a company like Revvity, that can be a sensible path to steadier long-term growth and margin support.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


