Stock Analysis · Resolute Mining Ltd (RMGGY)
Overview
Resolute Mining Ltd is a gold mining company focused on producing and selling gold from large-scale mining operations in Africa. The group’s main producing assets are the Syama Gold Mine in Mali and the Mako Gold Mine in Senegal. It also has development exposure through the Doropo project in Côte d’Ivoire, which is intended to become an additional source of production in the coming years if development continues as planned.
For a company like Resolute, revenue is mostly driven by one product: gold. In practical terms, sales depend on how much gold it produces, the grade of the ore, operating costs, and the market price of gold. Based on the company’s recent reporting, the revenue mix is heavily concentrated in a small number of mines rather than in many business lines.
The main sources of revenue are approximately:
- Syama, Mali: about 55% to 65% of group revenue in recent periods. This is the company’s largest asset and includes sulfide and oxide ore processing.
- Mako, Senegal: about 35% to 45% of group revenue in recent periods. Mako is a simpler, well-established open-pit operation and has been an important cash-generating mine.
- Other sources: generally 0% to 5%, mainly minor by-products or non-core items rather than a meaningful separate business line.
This concentration has a clear implication for long-term analysis: Resolute is relatively easy to understand, but it is also highly dependent on a limited number of assets and on the gold price.
The flow of earnings over the past several years shows a notable improvement. Revenue has risen from the low-to-mid hundreds of millions of dollars into the upper hundreds of millions, while profitability recovered sharply after earlier losses. Cost of sales remains the largest outflow, as expected for a miner, but operating income and net income improved materially by 2025, helped by stronger production economics and a favorable gold market.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $2.58B | |
| Beta ⓘ | 1.38 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.65 | 16.92 |
| P/B Ratio ⓘ | 2.17 | 1.66 |
| FCF Yield ⓘ | 11.43% | 5.83% |
| Dividend Yield ⓘ | N/A | 2.07% |
| EBIT / EV ⓘ | 25.88% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 30.70% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | -2.49% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 4.44% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | -3.59% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 37.55% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -19.19% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.59% |
| ROA (Latest) ⓘ | 18.09% | 4.92% |
| ROIC (5Y Median) ⓘ | 0.70% | 7.91% |
| ROA (5Y Median) ⓘ | -3.38% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | -0.03 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.50 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | -0.02 | 0.93 |
| Net Debt / Assets ⓘ | -0.92% | 13.69% |
| EBITDA / Interest ⓘ | 30.40 | 12.38 |
| Operating Margin (Latest) ⓘ | 23.64% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 3.50% | 11.82% |
| Debt to Equity (Latest) ⓘ | 19.83% | 40.30% |
| Profit Margin (Latest) ⓘ | 19.77% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $295.30M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +244.13% | +73.47% |
| 12M Return (excl. last month) ⓘ | +53.25% | +27.59% |
| 6M Return ⓘ | +4.04% | -4.02% |
| Price vs. 200-Day MA ⓘ | +4.71% | -0.65% |
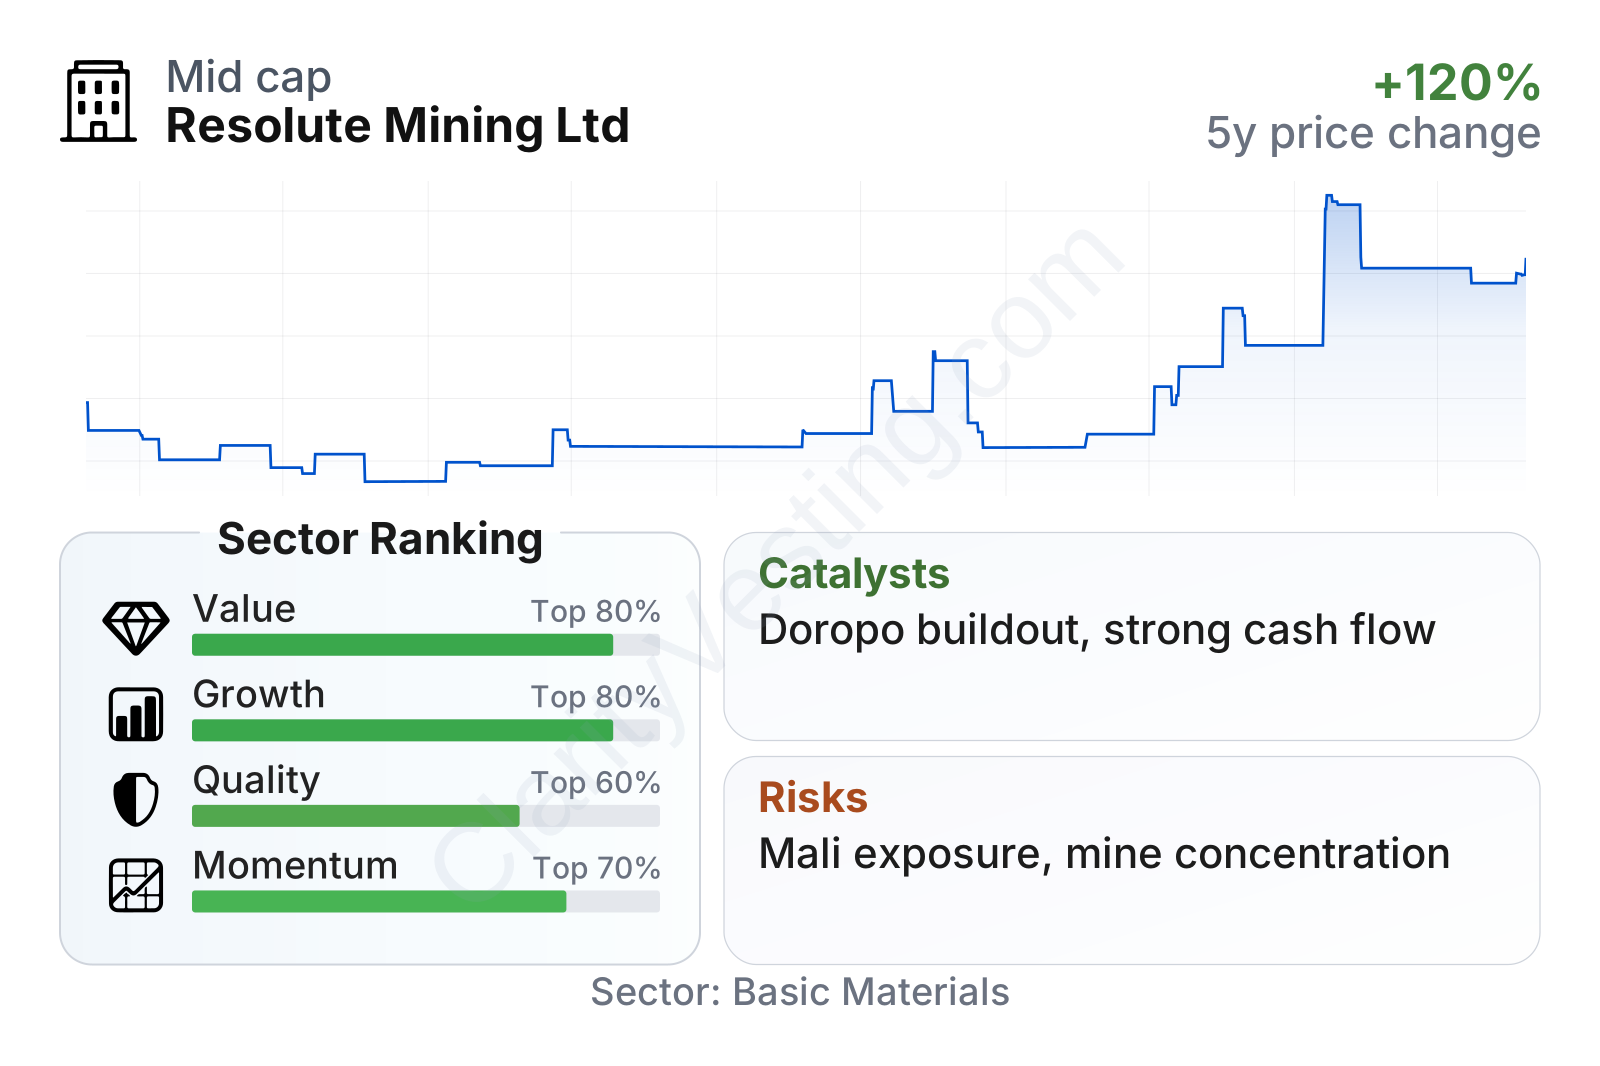
Resolute is a mid-sized gold producer with a share price history that has been volatile, which is typical for miners exposed to both commodity prices and operating execution. Over the last three years, the stock has delivered a much stronger return than the sector median, but recent months have been less smooth, with the shares pulling back from their highs.
The broader fundamental picture is stronger than the mixed short-term trading pattern suggests. On valuation, the company screens well versus much of the sector, with a low earnings multiple and a free cash flow yield that stands well above the sector median. Profitability also looks solid on a trailing basis, with margins and return on assets clearly ahead of many peers.
Growth indicators are more uneven. Recent year-over-year revenue expansion has been strong, and margin progression over the last several years has improved sharply. However, some longer-term per-share trends remain weaker, which reflects the fact that mining businesses often experience uneven production profiles, asset write-downs, and periodic reinvestment cycles.
Balance sheet quality is one of the cleaner parts of the case. Net debt metrics are very low, the company appears to be in a small net cash position on some measures, and interest coverage is strong. That financial flexibility matters in a sector where operating setbacks can emerge quickly.
Growth
Gold mining is not a conventional high-growth sector in the way software or semiconductors can be, but it can still offer attractive long-term expansion when companies add reserves, improve mine plans, or benefit from a supportive commodity cycle. Resolute operates in a sector that remains strategically important because gold is used as a store of value, a central bank reserve asset, and a hedge during periods of geopolitical or macroeconomic uncertainty. That backdrop has been supportive for producers as gold prices have remained elevated.
Resolute’s current strategy is straightforward and makes industrial sense: improve output and cash generation from existing mines while advancing its next development project. Syama is the core asset, and operational consistency there has an outsized impact on group results. Mako provides additional production and cash flow, while Doropo offers the possibility of extending the company’s mine portfolio and reducing reliance on only two producing assets.
A major catalyst is the potential transition from a two-mine producer toward a broader operating base if Doropo moves ahead successfully. For a miner of Resolute’s size, adding a new project can materially reshape future production, reserves, and market perception. Another positive driver is the company’s stronger recent profitability: improved margins and free cash flow give management more room to fund development, strengthen the balance sheet, or absorb volatility.
Recent company communications have also highlighted continued progress on operating performance and project advancement. In simple terms, the opportunity is not based on a new technology or a dramatic business model shift; it is based on executing well at existing mines and turning a development asset into the next producing operation. In mining, that can be enough to create meaningful long-term growth if delivery remains on track.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


