Stock Analysis · Resolute Mining Limited (RMGGF)
Overview
Resolute Mining Limited is a gold mining company focused on discovering, developing, and operating gold mines in Africa. Its business is straightforward: it extracts gold ore, processes it into saleable gold, and sells that production into the global gold market. The company has been listed in Australia for many years and also trades over the counter in the United States under the symbol RMGGF.
As of 2026, the company’s operating base is concentrated in two producing mines: Syama in Mali and Mako in Senegal. That means Resolute is not a diversified mining group with many metals or many regions. It is primarily a gold producer with a relatively focused portfolio, which can help execution when operations run well, but it also increases exposure to site-specific and country-specific disruption.
Revenue is overwhelmingly tied to gold sales. Based on the company’s recent annual reporting, the business mix can be described approximately as follows:
- Gold sales: about 95% to 100% — the core source of revenue, generated from gold produced at the Syama and Mako mines.
- Other operating income: about 0% to 5% — may include by-product, service, or other mine-related items, but these are not the economic driver of the business.
Within gold production itself, the asset contribution is mainly split between:
- Syama mine, Mali — a large and strategically important operation, including sulfide ore processing and underground mining.
- Mako mine, Senegal — a second producing asset that adds operating cash flow and geographic balance within West Africa.
The biggest change in the business over the last few years has been financial rather than structural. Revenue has climbed from roughly $550 million in 2021 to nearly $900 million in 2025, while profitability improved sharply after a difficult 2021. That suggests Resolute has moved from a stressed phase into a stronger cash-generating period, helped by better operations and a supportive gold price backdrop.
The long-term financial picture shows a notable recovery. Earlier results were weighed down by weak operating income and large losses, while the latest year shows much higher revenue, wider gross profit, and materially stronger operating earnings. In simple terms, a much larger share of sales is now flowing through to cash generation than it did a few years ago.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $1.52B | |
| Beta ⓘ | 1.38 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 7.89 | 16.90 |
| P/B Ratio ⓘ | 1.80 | 1.65 |
| FCF Yield ⓘ | 19.42% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | 24.92% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 30.70% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | -1.67% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -3.58% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 82.37% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -15.38% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 18.10% | 4.91% |
| ROIC (5Y Median) ⓘ | 0.70% | 7.70% |
| ROA (5Y Median) ⓘ | -3.38% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -0.03 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.42 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.02 | 0.95 |
| Net Debt / Assets ⓘ | -0.92% | 13.69% |
| EBITDA / Interest ⓘ | 23.53 | 12.34 |
| Operating Margin (Latest) ⓘ | 22.11% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 3.50% | 11.80% |
| Debt to Equity (Latest) ⓘ | 19.83% | 40.56% |
| Profit Margin (Latest) ⓘ | 19.77% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $294.72M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +236.14% | +68.89% |
| 12M Return (excl. last month) ⓘ | +98.18% | +30.21% |
| 6M Return ⓘ | -25.69% | -4.16% |
| Price vs. 200-Day MA ⓘ | -18.96% | -1.27% |
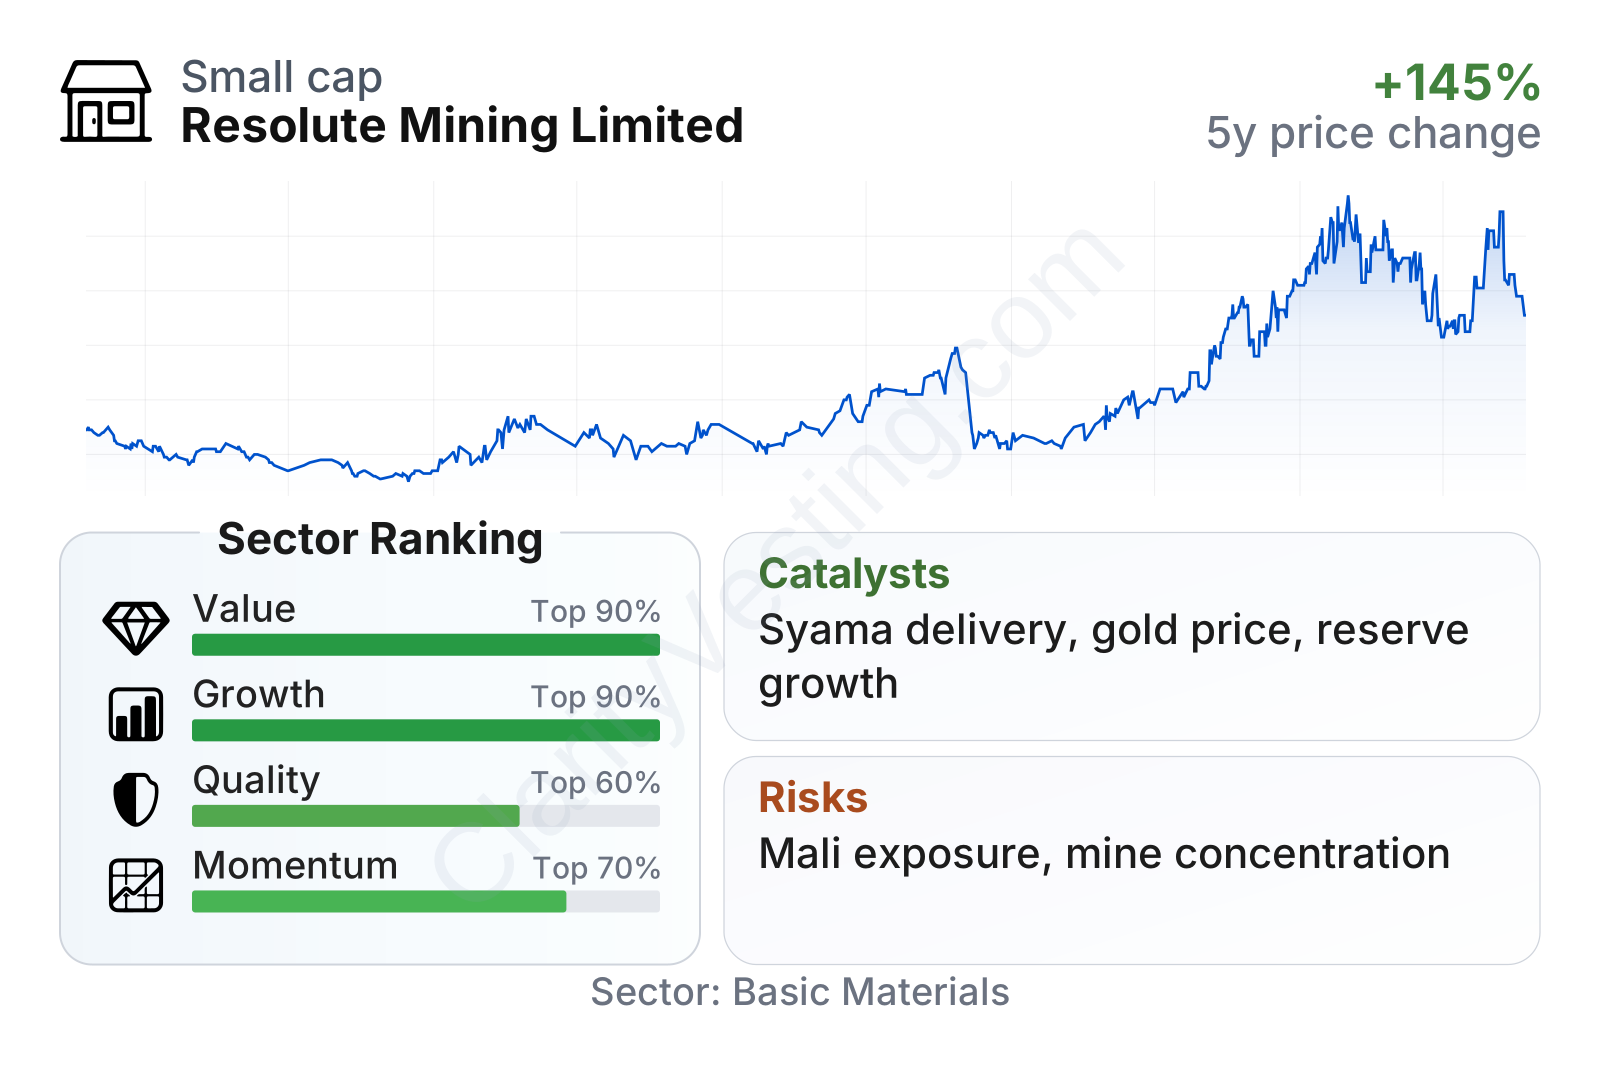
Resolute currently screens well on value and recent growth compared with much of the gold sector. Its earnings multiple is below the sector median, while free cash flow yield and EBIT relative to enterprise value are notably stronger than typical peers. Profitability is also solid in the latest period, with operating and net margins clearly above sector medians.
Balance sheet pressure appears limited at the moment. Net debt is effectively absent on a trailing basis, debt to equity is below the sector median, and interest coverage is strong. That is an important shift for a mining business, where leverage can become a major problem during weaker commodity cycles.
There is, however, a split between recent strength and longer-term consistency. Revenue growth over the last year has been strong, and margin trends over five years have improved sharply, but five-year revenue per share and book value per share trends remain weak. The stock’s price performance has also been strong over three years, although the last six months show more volatility and a flatter trend.
Growth
Resolute operates in the gold industry, which is a mature sector rather than a high-growth one in the way software or biotechnology can be. Still, gold miners can grow meaningfully through higher production, better recovery rates, lower costs, reserve replacement, and acquisitions. The sector also tends to benefit when gold prices are firm, especially during periods of inflation concerns, geopolitical tension, or central bank buying.
For Resolute, the growth case rests less on broad industry expansion and more on execution at a small number of core assets. Syama is central to that picture. It is a long-life asset and has been positioned as a technically important mine for the company, including automated and underground mining elements. If Syama performs reliably and efficiently, it can support production, margins, and mine life visibility for years. Mako adds a second source of production and cash generation, which matters because a two-mine portfolio is still narrow.
The company’s recent financial progress suggests its strategy has begun to translate into better results. Revenue growth of roughly 31% year over year is well above the sector median, and free cash flow is strong for a company of this size. That combination gives Resolute more flexibility to fund mine development, exploration, debt reduction, or shareholder distributions without relying as heavily on external capital.
A meaningful catalyst is continued operational delivery at Syama and Mako combined with sustained gold prices. In mining, a favorable metal price can amplify improvements in cost control and plant performance. Because Resolute’s recent margins are much stronger than its own historical averages, further stable execution could make the current earnings base appear more durable than the market previously assumed.
Another possible catalyst is reserve and resource conversion around existing mines. For smaller gold producers, extending mine life can matter almost as much as near-term production growth because it improves visibility and can justify continued infrastructure investment. Exploration success near current operations is often more valuable than early-stage greenfield projects because the processing and site infrastructure are already in place.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


