Stock Analysis · Repligen Corporation (RGEN)
Overview
Repligen Corporation is a life sciences tools company focused on bioprocessing. In simple terms, it sells the equipment, consumables, and process technologies that drug manufacturers use to make biologic medicines, including monoclonal antibodies, gene therapies, and other large-molecule treatments. Rather than developing drugs itself, Repligen supplies the “picks and shovels” used in the manufacturing process. That position can be attractive because demand is tied to the broader growth of biologic drug production across the industry.
The company organizes its business around several bioprocessing workflows. Based on recent annual reporting, revenue is spread across four main franchises, with a business mix that is fairly diversified rather than dependent on a single product line.
- Filtration: approximately 35% to 40% of revenue. This includes hollow fiber and tangential flow filtration systems used to separate, concentrate, and purify biologic materials during manufacturing.
- Chromatography: approximately 25% to 30% of revenue. This area includes resins, columns, and related systems used in purification steps, where manufacturers isolate the desired product from impurities.
- Process Analytics: approximately 20% to 25% of revenue. These products help customers monitor and control production in real time, including sensors and analytical tools that improve consistency and efficiency.
- Protein: approximately 10% to 15% of revenue. This includes Protein A ligands and related components used in purification, especially in antibody manufacturing.
Geographically, Repligen serves global biopharma customers, with revenue split across North America, Europe, and Asia. Its customer base includes large drug companies, contract development and manufacturing organizations, and smaller biotech firms. That mix matters because it gives the company exposure to both established commercial production and earlier-stage pipelines that can mature over time.
Over the last several years, the business has gone through a sharp cycle. Revenue climbed strongly through the pandemic-era bioprocessing boom, then fell as customers worked through excess inventory and funding conditions in biotech became tighter. More recently, sales growth has turned positive again, suggesting the reset period may be passing, although profitability has not fully returned to earlier peak levels.
The long-term business model is straightforward: recurring consumables, specialized equipment embedded in customer workflows, and a broad installed base that can support repeat purchasing. That usually leads to steadier demand than a one-time equipment model, although it does not eliminate cyclicality.
The multi-year financial flow shows a business that expanded rapidly, then absorbed a meaningful downturn in 2023 and 2024 before recovering in 2025. Revenue and gross profit have improved again, but operating costs remain elevated compared with the earlier peak, which helps explain why earnings recovery has lagged the rebound in sales.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Instruments & Supplies | |
| Market Cap ⓘ | $10.85B | |
| Beta ⓘ | 1.05 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 259.77 | 24.06 |
| P/B Ratio ⓘ | 4.75 | 3.08 |
| FCF Yield ⓘ | 1.02% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | 0.75% | 0.63% |
| PEG ⓘ | 1.84 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 11.90% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 2.75% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | -26.78% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | 5.06% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | -12.99% | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | 15.96% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 3.08% | 3.29% |
| ROA (Latest) ⓘ | 1.41% | 3.02% |
| ROIC (5Y Median) ⓘ | 2.61% | 4.75% |
| ROA (5Y Median) ⓘ | 1.69% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | 1.09 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.58 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 0.69 | 0.99 |
| Net Debt / Assets ⓘ | 2.85% | 5.33% |
| EBITDA / Interest ⓘ | 2.15 | 9.63 |
| Operating Margin (Latest) ⓘ | 9.87% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 11.59% | 7.80% |
| Debt to Equity (Latest) ⓘ | 32.71% | 28.99% |
| Profit Margin (Latest) ⓘ | 5.29% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $110.78M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +14.37% | +37.48% |
| 12M Return (excl. last month) ⓘ | +39.00% | +20.85% |
| 6M Return ⓘ | +49.79% | +9.73% |
| Price vs. 200-Day MA ⓘ | +23.59% | +4.69% |
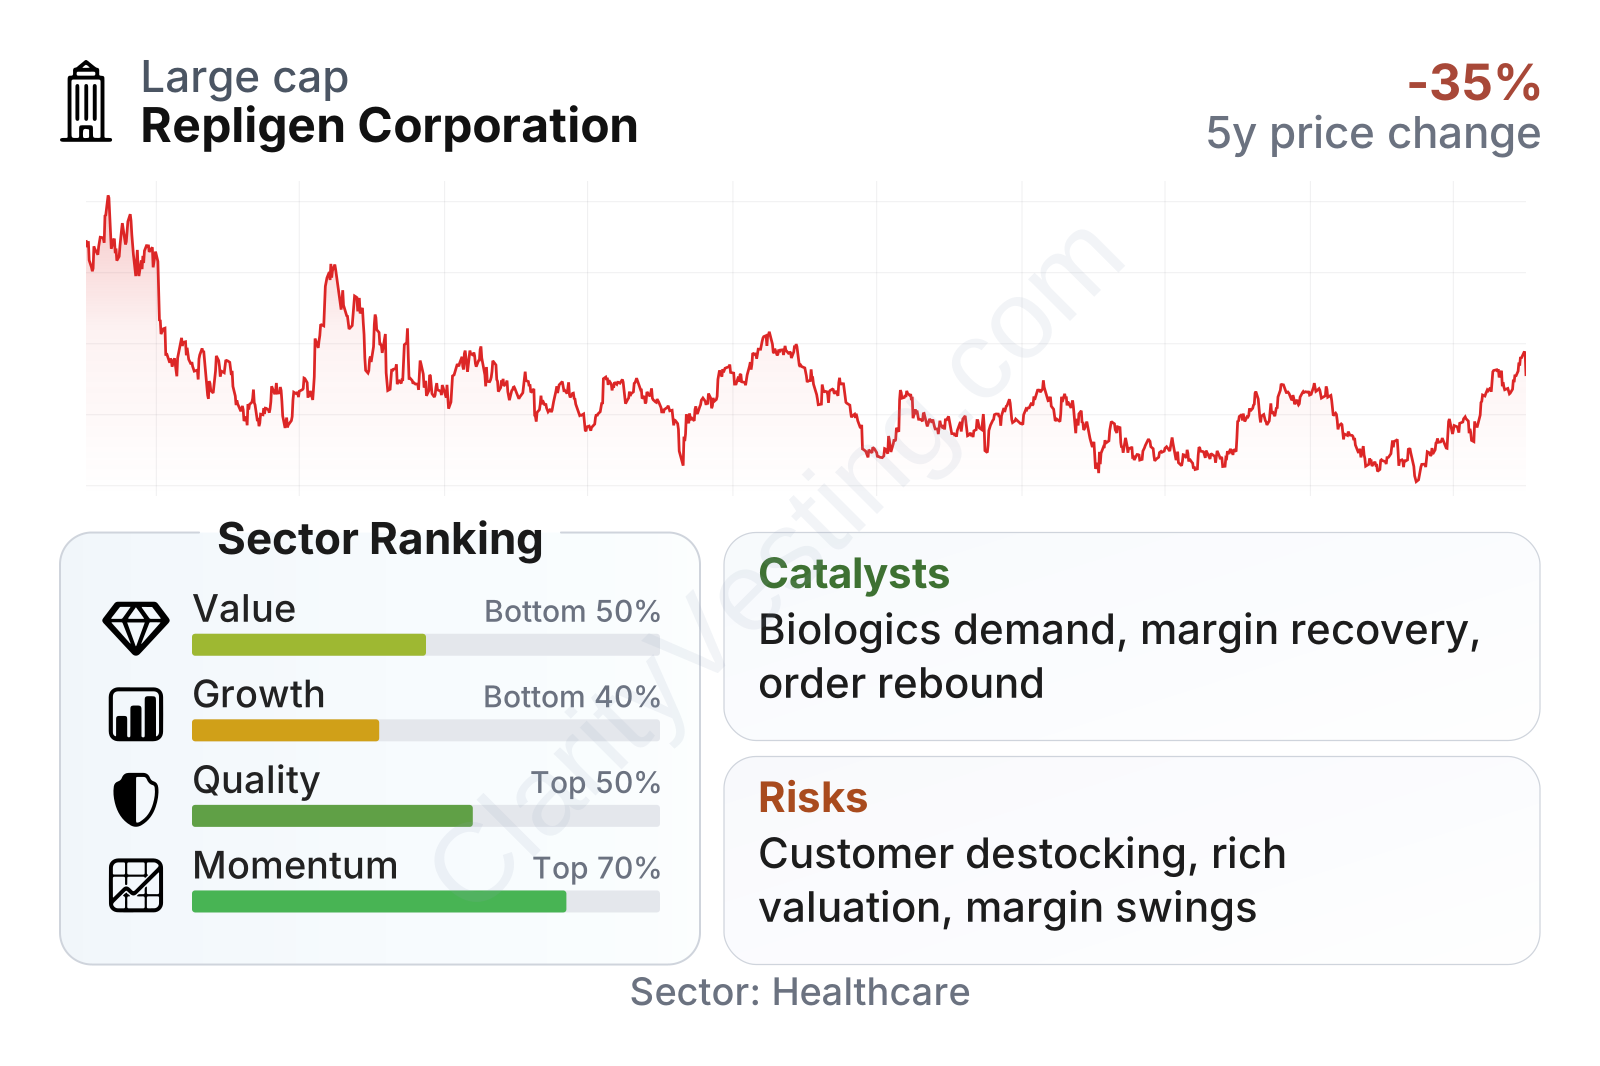
Repligen is a mid-to-large life sciences tools company with a market value around the low double-digit billions and a share price that has been notably volatile over the last several years. The operating profile is mixed. Quality metrics are respectable overall, helped by positive margins and moderate leverage, but returns on capital remain below the sector median. Growth is also mixed: recent revenue growth is ahead of the sector median, yet the longer five-year earnings trend still reflects the post-boom reset. Valuation stands out as the clearest weak point, with earnings and cash flow multiples well above sector norms.
Growth
Repligen operates in a sector with attractive long-term tailwinds. Biologic drugs continue to take a larger share of the pharmaceutical market, and these medicines are usually more complex to manufacture than traditional small-molecule drugs. That complexity increases the need for filtration, purification, analytics, and other process tools. In addition, growth in cell and gene therapy, outsourced manufacturing, and capacity expansion by global biologics producers all support demand for the types of products Repligen sells.
The company’s strategy is logical for that environment. It focuses on specialized products that fit into critical manufacturing steps rather than trying to compete as a broad commodity supplier. That allows it to target niches where reliability, validation history, and process performance matter more than price alone. Repligen has also expanded by acquisition over time, building a broader portfolio that can sell across multiple stages of the bioprocessing workflow.
The revenue trend shows a clear pattern: an exceptional surge in 2021 and early 2022, a painful contraction through 2023, and then a return to positive growth from late 2024 onward. Most recently, year-over-year growth has remained in the low-teens range, which is a healthier level than the industry was seeing during the downturn, even if it is far below the extraordinary pandemic-era spike.
Cash generation has held up better than earnings during the recovery. Free cash flow has stayed positive and fairly solid, which matters because it gives the company flexibility to keep investing in product development, manufacturing capacity, and selective acquisitions without relying heavily on new financing. Over a five-year view, free cash flow growth has been much stronger than the sector median, even though that period includes considerable volatility.
Recent company updates have pointed to improving order patterns, stronger demand in selected product categories, and continued normalization after the inventory correction that hurt the broader bioprocessing tools space. A meaningful catalyst is the continued recovery in biotech funding and customer purchasing activity. Another is the possibility that more commercial biologics production shifts toward intensified and more analytics-heavy processes, areas where Repligen has established offerings. As larger biologics plants ramp and new therapies move from clinical development into commercial manufacturing, the company has room to benefit from both higher volume and a broader product mix.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


