Stock Analysis · Reinsurance Group of America (RGA)
Overview
Reinsurance Group of America is a life and health reinsurer. In simple terms, it helps insurance companies manage risk by taking on part of the policies those insurers have written. Instead of selling most policies directly to consumers, RGA mainly works behind the scenes with insurers around the world. Its business is especially focused on life insurance, health-related protection, longevity risk, and financial solutions that help insurers manage capital and balance-sheet needs.
The company operates globally, with business across the United States, Canada, Europe, Asia Pacific, Latin America, and other international markets. That geographic spread matters because it reduces dependence on any one insurance market and gives RGA access to countries where protection needs, aging populations, and demand for retirement-related risk transfer are still developing.
RGA’s revenue is largely driven by premiums from reinsurance contracts, investment income earned on its asset portfolio, and fees or other income tied to financial solutions and asset-intensive transactions. Based on the company’s recent reporting structure and typical mix, the main sources can be understood as follows:
- Traditional life and health reinsurance premiums and related income: approximately 70% to 80% of total revenue. This includes mortality and morbidity risk protection for life, health, disability, and similar insurance products.
- Investment income: approximately 15% to 25%. Like other insurers and reinsurers, RGA invests premiums and reserves, so bond yields and portfolio performance are important to earnings.
- Asset-intensive, longevity, and financial solutions-related income: approximately 5% to 10%. This includes pension risk transfer, annuity-related transactions, capital-motivated reinsurance, and customized transactions for insurers.
Over the last several years, the business mix has also shown a clear rise in total revenue and operating earnings, although results can move unevenly because reinsurance is naturally sensitive to claims, assumption changes, and investment markets. The company’s scale, broad client relationships, and ability to structure complex transactions are central to how it competes.
The business has expanded meaningfully since 2023, with revenue climbing from the high teens in billions of dollars to the low twenties, while net income has also improved from earlier cyclical lows. That pattern suggests a larger earnings base today, but one that still carries the normal volatility of a global reinsurer.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 09, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Insurance - Reinsurance | |
| Market Cap ⓘ | $17.03B | |
| Beta ⓘ | 0.40 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 10.14 | 12.43 |
| P/B Ratio ⓘ | 1.48 | 1.25 |
| FCF Yield ⓘ | 32.66% | 10.10% |
| Dividend Yield ⓘ | 1.44% | 2.85% |
| EBIT / EV ⓘ | 12.83% | 8.09% |
| PEG ⓘ | 1.14 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 21.70% | 7.40% |
| RPS Growth (5Y CAGR) ⓘ | 8.78% | 12.30% |
| EPS Growth (5Y CAGR) ⓘ | 14.96% | -1.83% |
| BVPS Growth (5Y CAGR) ⓘ | -36.74% | 4.87% |
| Margin Growth (5Y Trend) ⓘ | 4.21% | -4.14% |
| FCF Growth (5Y CAGR) ⓘ | -0.44% | 4.69% |
| DPS Growth (5Y CAGR) ⓘ | 6.08% | 8.86% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 9.57% | 9.35% |
| ROE (Latest) ⓘ | 13.69% | 14.03% |
| ROA (Latest) ⓘ | 1.05% | 1.57% |
| ROIC (5Y Median) ⓘ | 6.46% | 7.83% |
| ROE (5Y Median) ⓘ | 7.27% | 12.10% |
| ROA (5Y Median) ⓘ | 0.70% | 1.28% |
| Net Debt / EBIT (Latest) ⓘ | 0.19 | 0.86 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.14 | 0.74 |
| Net Debt / EBITDA (Latest) ⓘ | 0.26 | 0.75 |
| Operating Margin (Latest) ⓘ | 8.85% | 22.67% |
| Operating Margin (5Y Median) ⓘ | 5.82% | 24.30% |
| Debt to Equity (Latest) ⓘ | 45.63% | 58.11% |
| Profit Margin (Latest) ⓘ | 6.26% | 26.32% |
| Free Cash Flow (Latest) ⓘ | $5.56B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +79.71% | +86.11% |
| 12M Return (excl. last month) ⓘ | +29.54% | +15.45% |
| 6M Return ⓘ | +24.09% | +5.96% |
| Price vs. 200-Day MA ⓘ | +16.18% | +4.61% |
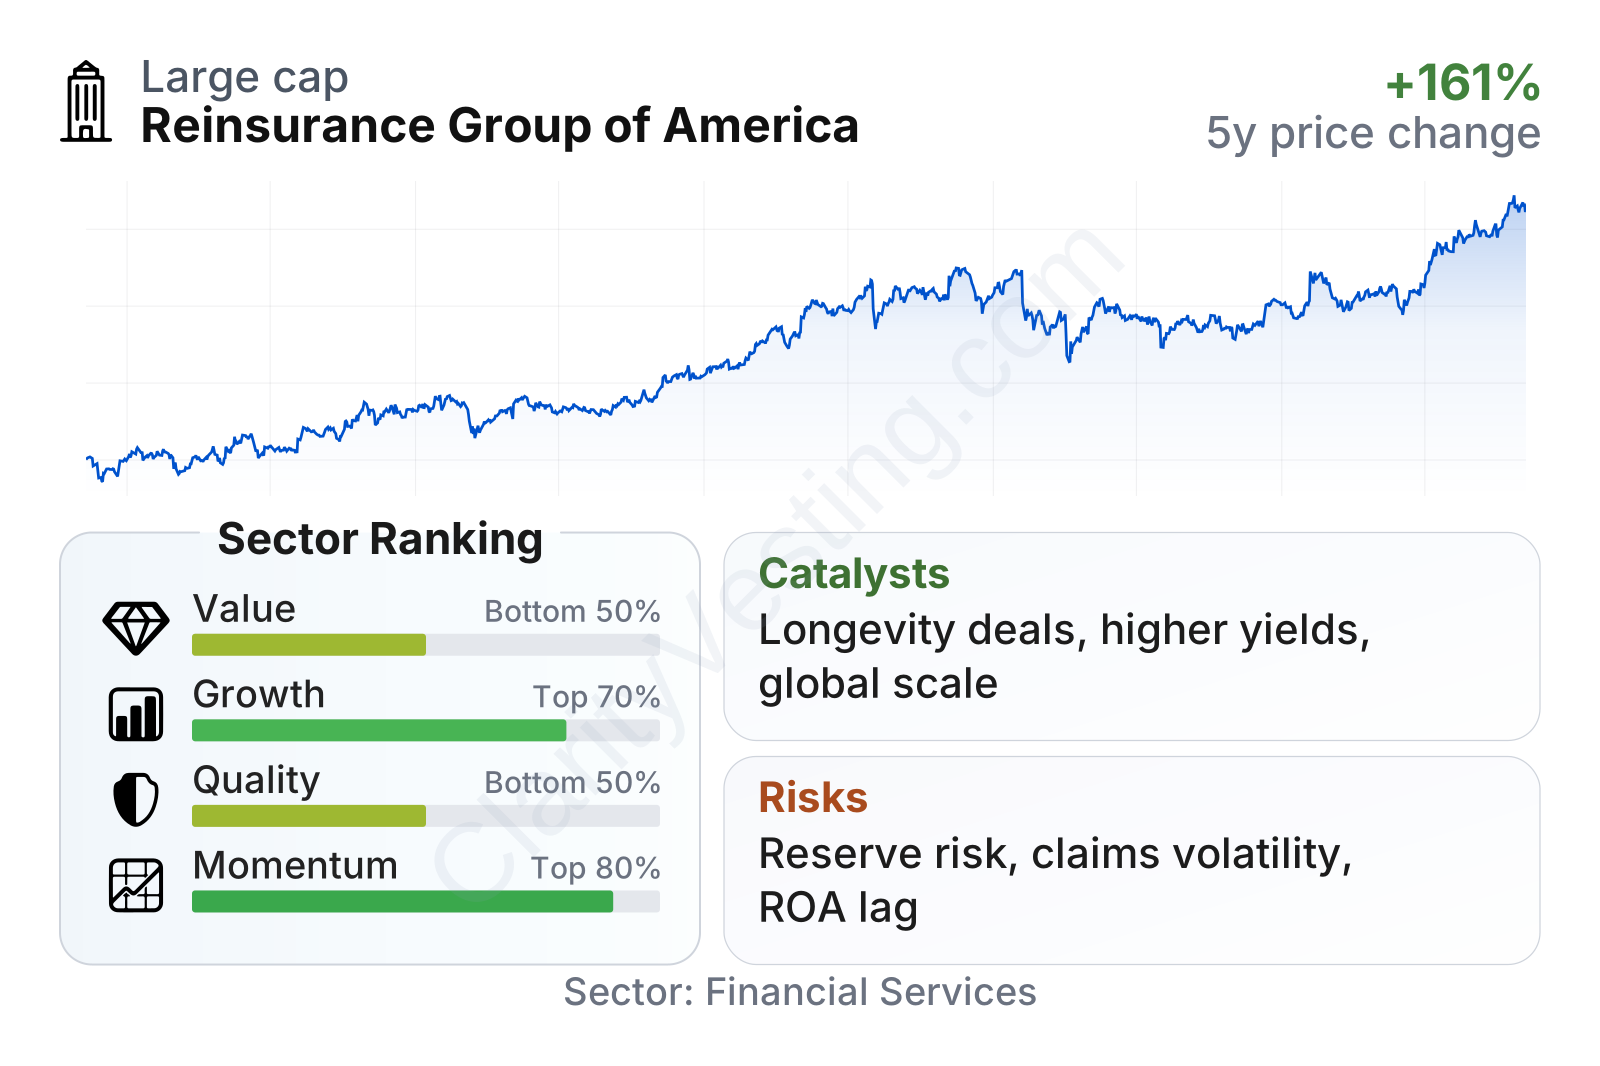
RGA is a large reinsurance company with a relatively low share-price volatility profile, as shown by its beta well below 1. On valuation measures, the picture is mixed: earnings-based multiples are not stretched, but the price-to-book ratio sits somewhat above the sector median. Growth and momentum are stronger than the company’s broader sector ranking, helped by solid earnings expansion and better recent share performance. Quality metrics are more uneven, with profitability ratios still modest versus many financial peers, even though leverage remains fairly contained for the business model.
Growth
RGA operates in a sector that has durable long-term demand drivers. Insurers increasingly use reinsurers not only for classic mortality protection, but also for capital relief, pension and longevity transactions, and support for more complex asset-intensive products. Aging populations, higher protection gaps in many countries, and tighter capital management across the insurance industry all support the need for specialist reinsurers with scale and underwriting expertise.
The company’s strategy appears aligned with those trends. RGA has been emphasizing diversified global operations, financial solutions, pension risk transfer, and asset-intensive opportunities rather than relying only on traditional mortality reinsurance. That matters because these areas can deepen relationships with insurers and create larger, more customized transactions. In recent years, management has also highlighted disciplined underwriting and selective deployment of capital, which is especially important in a business where growth can become risky if pricing weakens.
Earnings per share have moved sharply higher from the low levels seen earlier in the period and have remained at a much stronger run rate since 2023. Even allowing for the fact that insurance earnings can be uneven quarter to quarter, the broader direction points to a business that has rebuilt profitability.
Book value per share has also recovered strongly after an unusual drop in the earlier part of the period. For insurers and reinsurers, book value is one of the most important anchors because it reflects how the balance sheet is compounding over time. The recent progression suggests that capital generation has improved materially.
A notable catalyst is the industry backdrop created by higher interest rates compared with the ultra-low-rate years. Reinsurers invest large pools of assets, so better yields can support future investment income as portfolios are reinvested. Another positive factor is demand for pension and longevity risk transfer, where insurers and pension systems increasingly seek external partners with structuring capability and balance-sheet capacity. RGA’s international reach and specialization make it relevant in these markets.
Recent company updates have also pointed to continued activity in financial solutions and asset-intensive reinsurance, which is important because these businesses can support premium growth without depending entirely on traditional U.S. mortality lines. For a long-term view, that broadening of the platform is one of the more meaningful developments.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer