Stock Analysis · QMMM Holdings Limited (QMMM)
Overview
QMMM Holdings Limited is a small advertising and marketing services company. Based on its public filings, the business has focused on helping clients with branding, creative work, media-related services, and broader marketing support. It operates in the Advertising Agencies segment within the communication services sector, a field that generally depends on client budgets, campaign activity, and the company’s ability to win and retain accounts.
The company’s revenue disclosure is limited, so a precise breakdown by business line is not clearly available from the information reviewed. Public filings indicate that revenue mainly comes from marketing and advertising services provided to customers rather than from a diversified mix of products, subscriptions, or licensing streams. That means the business appears to rely primarily on fee-based service income tied to client projects and ongoing marketing mandates.
- Advertising and marketing services: the core source of revenue, including creative, branding, promotional, and campaign-related work for clients.
- Related support services: may include execution, consulting, and other client-service activities attached to advertising assignments, but public disclosures do not provide a reliable percentage split.
One important point for long-term readers is scale. QMMM is still a relatively small operating business by revenue, even though its market value has recently become much larger. That gap between operating size and stock market value is central to understanding the company’s current profile.
The financial flow over the last three reported fiscal years shows a weakening business model: revenue has trended lower, gross profit has narrowed, and selling and administrative expenses have remained heavy relative to sales. The result has been a move from profitability in 2022 to sizable operating and net losses in 2023 and 2024.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Communication Services | |
| Industry | Advertising Agencies | |
| Market Cap ⓘ | $6.83B | |
| Beta ⓘ | 14.89 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 17.78 |
| FCF Yield ⓘ | N/A | 14.20% |
| Dividend Yield ⓘ | N/A | 2.74% |
| EBIT / EV ⓘ | N/A | 4.52% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -40.10% | 5.50% |
| RPS Growth (5Y CAGR) ⓘ | -9.69% | 4.55% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.24% |
| Margin Growth (5Y Trend) ⓘ | N/A | 1.03% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 5.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.00% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 8.59% |
| ROIC (5Y Median) ⓘ | N/A | 8.24% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.89 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.81 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.14 |
| Net Debt / Assets ⓘ | -2.36% | 18.62% |
| EBITDA / Interest ⓘ | N/A | 8.36 |
| Operating Margin (Latest) ⓘ | N/A | 15.53% |
| Operating Margin (5Y Median) ⓘ | -10.41% | 13.39% |
| Debt to Equity (Latest) ⓘ | 1.61% | 59.53% |
| Profit Margin (Latest) ⓘ | -150.09% | 8.77% |
| Free Cash Flow (Latest) ⓘ | N/A | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +44.75% |
| 12M Return (excl. last month) ⓘ | +5024.46% | +2.72% |
| 6M Return ⓘ | 0.00% | +1.84% |
| Price vs. 200-Day MA ⓘ | 0.00% | +1.21% |
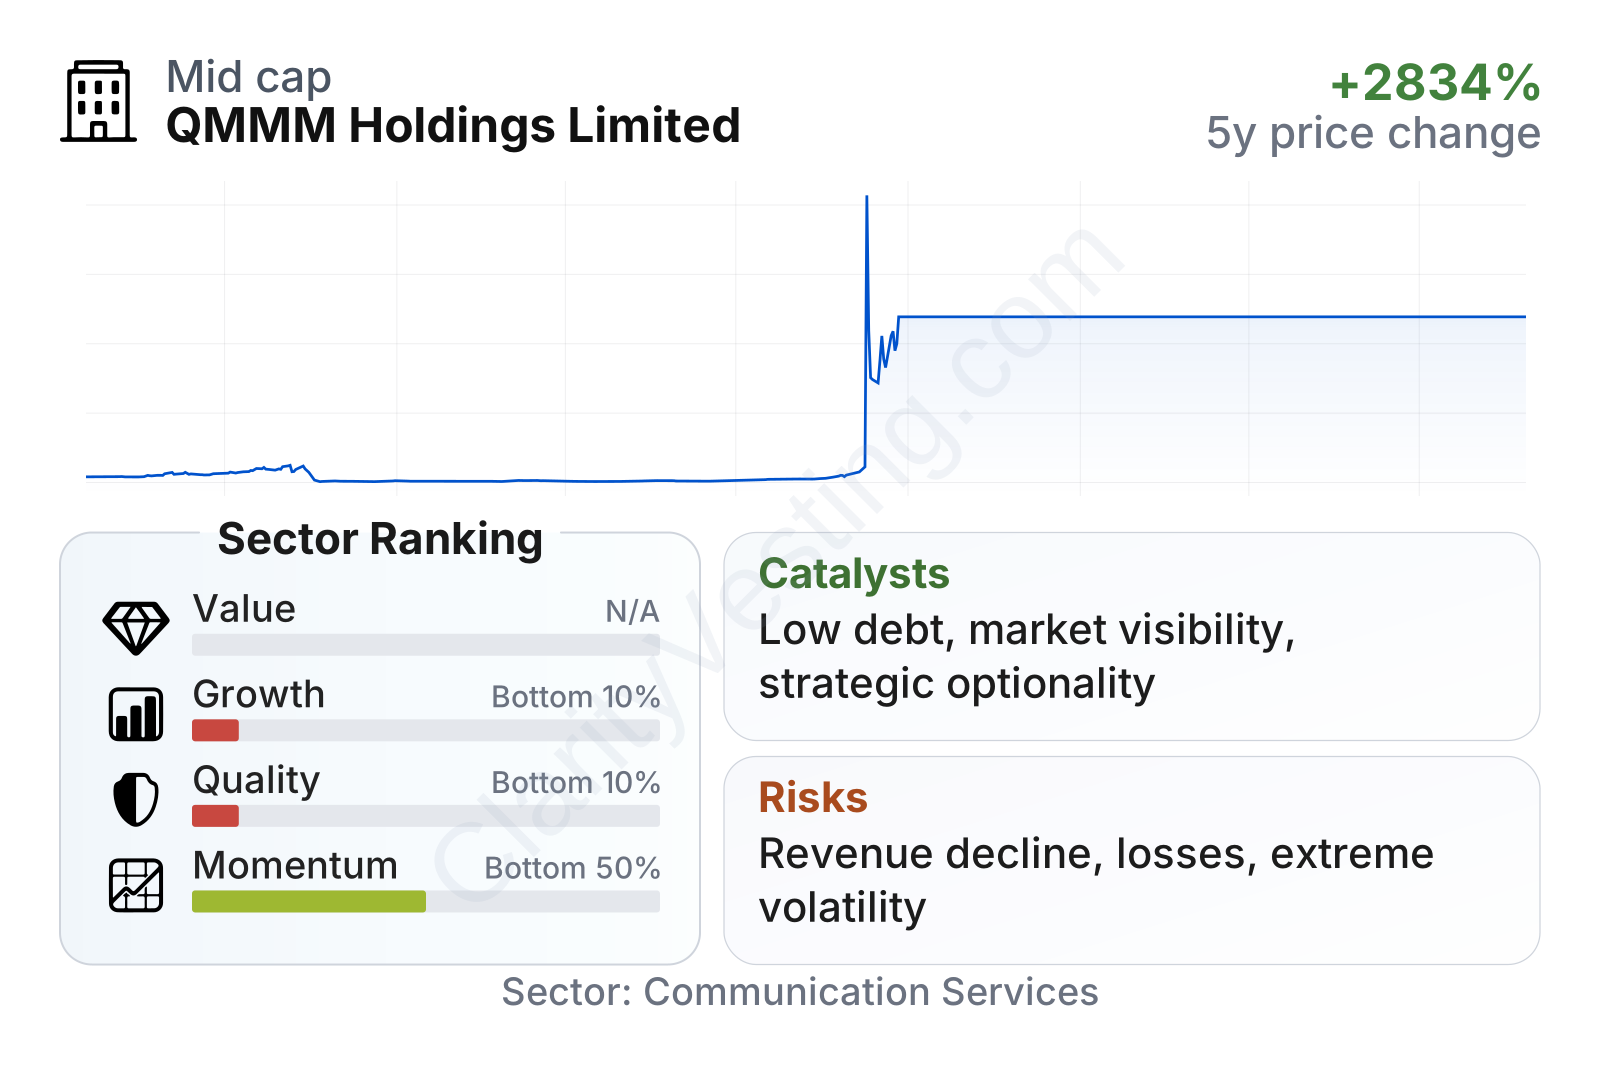
The overall picture is unusual. QMMM has a market capitalization in the mid-single-digit billions of dollars, but its operating business remains very small and currently unprofitable. Growth and quality metrics rank in the bottom 10% of its sector, reflecting contracting revenue, weak margins, and negative profitability. At the same time, momentum screens much better because the stock experienced an extraordinary price surge over the past year. That divergence suggests the share performance has been driven far more by market behavior than by business improvement.
Balance-sheet leverage is not the main issue here. Debt to equity is extremely low at roughly 2%, far below the sector median near 60%, and net debt relative to assets is negative, which points to a net cash position. In other words, QMMM does not appear financially stretched by borrowing. The challenge is operating performance: revenue fell about 40% year over year, and the profit margin is deeply negative, indicating that the company is losing much more than it earns from sales.
The stock-price chart also deserves careful context. The move from well below $1 at one stage to about $119 later on is far too extreme to be explained by the company’s reported revenue base and recent losses alone. When a stock shows this kind of jump while underlying fundamentals remain weak, volatility and price dislocation become major parts of the investment case.
Growth
The broader advertising and marketing industry can offer long-term growth because companies continue to spend on brand building, customer acquisition, and digital engagement. Over time, advertising budgets have shifted toward data-driven and online channels, creating room for agencies and marketing specialists that can prove effectiveness and adapt to changing media habits.
That said, QMMM’s own recent operating record does not currently show that it is capturing this industry growth. Revenue has declined for multiple years, and the business has not demonstrated the margin structure usually associated with a scalable agency platform. A sensible long-term strategy in this sector would normally require stronger client retention, new account wins, better service differentiation, and tighter cost control. Based on recent reported results, those elements still need clearer evidence.
A potential catalyst is the company’s access to public equity markets. With a much larger market valuation than its revenue base would normally suggest, QMMM could theoretically have more strategic flexibility for acquisitions, capital raising, or repositioning if management uses that window effectively. Another possible positive factor is the low debt burden, which gives the company more room to reshape operations than a heavily leveraged peer would have.
Recent market behavior itself is also a catalyst, although not necessarily a fundamental one. The stock’s sharp re-rating has drawn attention and may improve visibility. If that attention is eventually matched by concrete developments such as acquisitions, partnerships, expansion into faster-growing advertising niches, or a measurable improvement in client activity, the current market interest could become more closely tied to operating progress. For now, however, the business case still appears ahead of the financial results rather than fully supported by them.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


