Stock Analysis · Protagonist Therapeutics Inc (PTGX)
Overview
Protagonist Therapeutics is a biotechnology company focused on peptide-based medicines. In simple terms, it designs drug candidates made from short chains of amino acids and aims them at diseases where highly targeted treatment could matter. The company’s pipeline has been centered on hematology and blood-related disorders, as well as inflammatory and immunology indications, with key programs advanced through partnerships with larger pharmaceutical companies.
For a long-term stock analysis, the most important point is that Protagonist is not a typical mature drug company with broad recurring product sales. Its business model has relied heavily on collaboration economics: upfront payments, milestone payments, and other licensing-related revenue tied to the progress of its drug programs. That creates the possibility of large jumps in reported revenue, but it also makes annual results uneven.
The main revenue sources appear to be the following:
- Collaboration and license revenue: approximately 95% to 100% of recent total revenue. This includes upfront consideration, development and regulatory milestones, and revenue recognized under strategic partnerships tied to programs such as rusfertide and other peptide candidates.
- Other revenue: approximately 0% to 5%. This is a small residual category when present and can include items linked to contract-related activity or other minor operating inflows.
- Product sales: 0%. Protagonist is still primarily a development-stage biotech rather than a commercial drug seller with a diversified marketed-product base.
The financial flow over the last several years shows why the stock has attracted attention. Revenue was modest for a long time, then surged in 2024 because of partnership-related income, while research and development spending remained high as the company continued advancing its pipeline. That means profitability can swing sharply depending on deal timing rather than reflecting a stable, repeatable sales engine.
The business has gone from heavy losses to a temporary burst of profitability and then back to more uneven results, which is common in biotech companies driven by licensing events rather than steady product demand.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $9.12B | |
| Beta ⓘ | 1.52 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 136.82 | 24.79 |
| P/B Ratio ⓘ | 11.81 | 2.97 |
| FCF Yield ⓘ | 1.45% | 3.11% |
| Dividend Yield ⓘ | N/A | 2.04% |
| EBIT / EV ⓘ | 1.03% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3749.20% | 7.35% |
| RPS Growth (5Y CAGR) ⓘ | 5.22% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.43% |
| BVPS Growth (5Y CAGR) ⓘ | 10.54% | 3.94% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.61% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.74% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.78% | 3.34% |
| ROA (Latest) ⓘ | 10.45% | 2.95% |
| ROIC (5Y Median) ⓘ | -22.30% | 4.60% |
| ROA (5Y Median) ⓘ | -26.06% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | -4.87 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | -4.78 | 1.02 |
| Net Debt / Assets ⓘ | -46.40% | 5.85% |
| EBITDA / Interest ⓘ | N/A | 9.60 |
| Operating Margin (Latest) ⓘ | 29.91% | 9.19% |
| Operating Margin (5Y Median) ⓘ | -281.01% | 7.53% |
| Debt to Equity (Latest) ⓘ | 1.10% | 29.44% |
| Profit Margin (Latest) ⓘ | 29.40% | 3.52% |
| Free Cash Flow (Latest) ⓘ | $132.17M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +746.91% | +34.80% |
| 12M Return (excl. last month) ⓘ | +159.73% | +19.33% |
| 6M Return ⓘ | +37.05% | +7.18% |
| Price vs. 200-Day MA ⓘ | +24.62% | +3.20% |
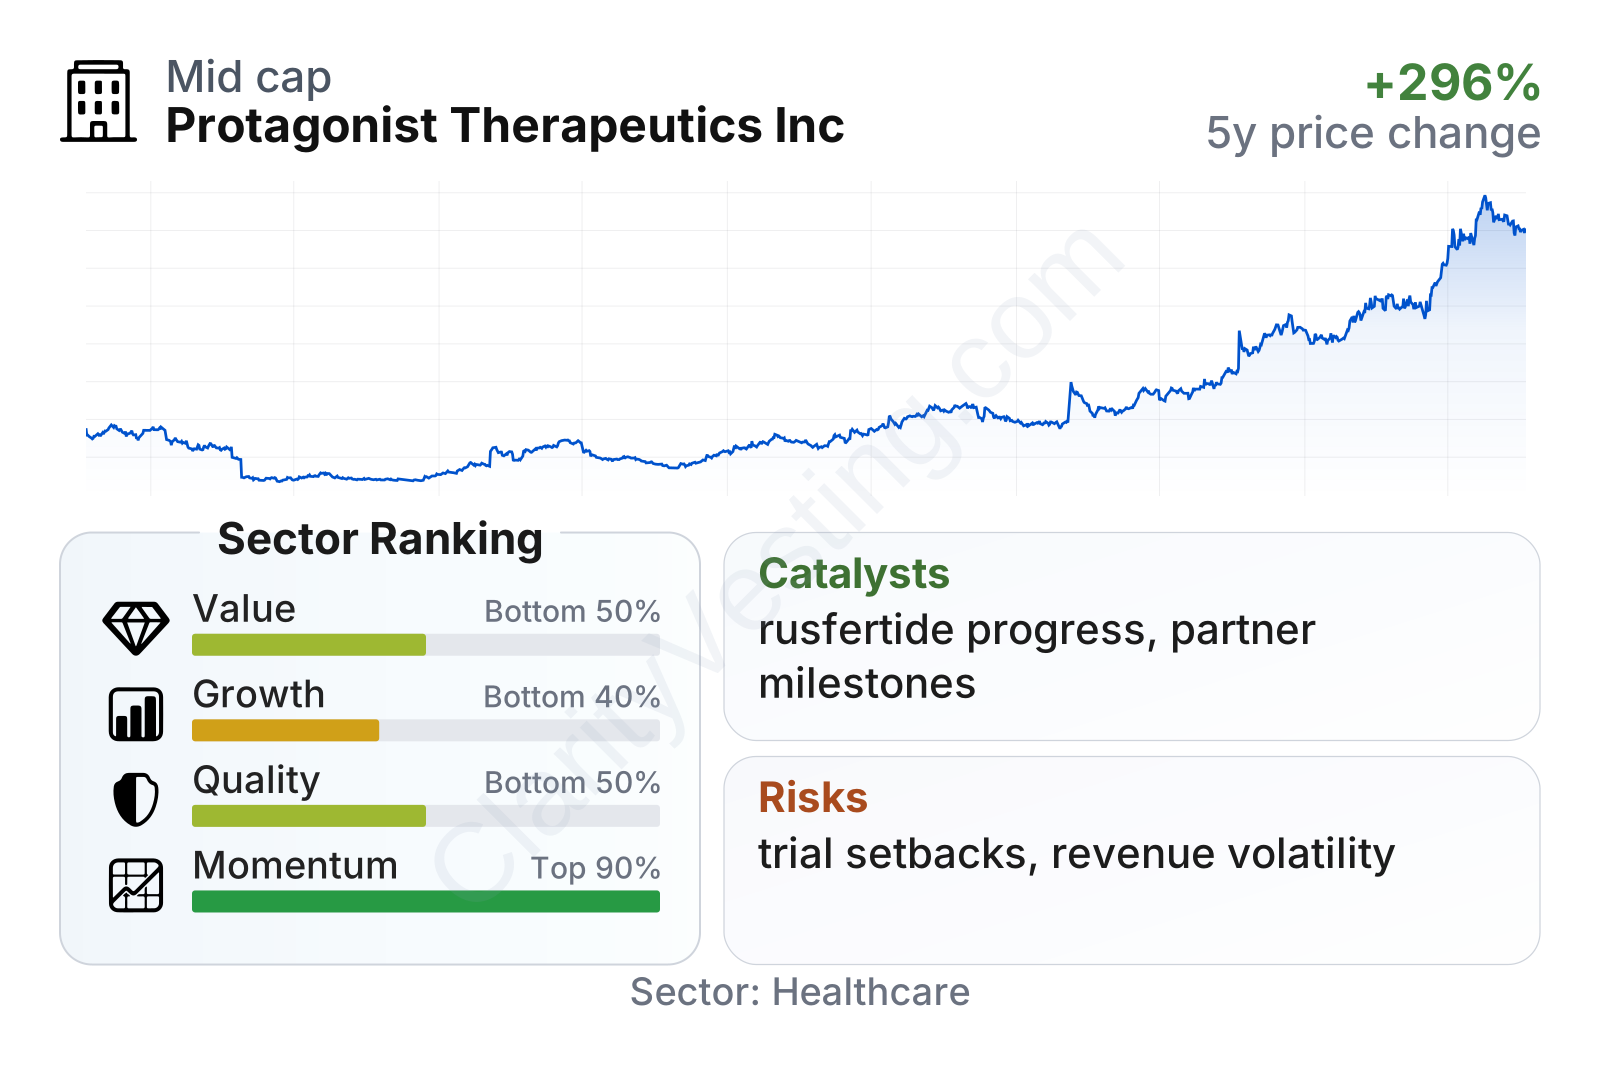
Protagonist is now a large biotech by market value rather than a small speculative micro-cap, but its share price still behaves like a high-volatility growth stock. The stock’s recent momentum has been exceptionally strong versus much of the healthcare sector, reflecting market enthusiasm around its pipeline and partnerships. At the same time, the valuation factors sit in the weaker half of the sector because the market is already assigning a rich multiple to future expectations.
On profitability and balance sheet strength, the picture is more favorable than many biotechnology peers. The company has very low leverage, strong cash relative to debt, and recent returns on capital and assets that compare well with sector medians. The main limitation is that these strengths have not been consistently visible over a full five-year period, which shows how dependent results remain on milestone timing.
Growth
Biotechnology remains a growth sector, especially in areas where novel therapies address diseases with limited treatment options. Protagonist operates in a part of the market where successful clinical data can create major value quickly, particularly when larger pharmaceutical partners are involved. Its strategy makes sense for future growth because it combines internal drug discovery with external partnerships that can provide funding, development support, and commercial reach.
The company’s most important growth driver is its clinical pipeline, especially programs that target clearly defined diseases and could move into later-stage development or commercialization milestones. In this model, a strong study result does not just improve scientific credibility; it can also unlock new milestone payments, broaden partnership economics, and improve negotiating power for future deals.
Revenue growth has been extremely volatile rather than smooth. There have been periods of very large expansion followed by steep declines, which is typical when reported revenue depends on deal events. The latest acceleration is eye-catching, but it should be read as event-driven growth rather than the kind of recurring pattern usually seen in established healthcare businesses.
Cash generation tells a similar story. Free cash flow has improved dramatically at times, but it has not settled into a consistently positive pattern. For long-term analysis, that means the company’s ability to create value still depends much more on pipeline progress and partnership milestones than on self-sustaining operating cash inflows.
A major recent opportunity for Protagonist has been continued advancement of rusfertide, its hepcidin mimetic candidate for polycythemia vera, along with broader validation of its peptide platform through large pharmaceutical collaborations. These developments matter because they support both scientific relevance and commercial optionality. If late-stage development remains successful, the company could move from being viewed mainly as a deal-driven biotech to one with clearer long-duration economics tied to important specialty therapies.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


