Stock Analysis · Proto Labs Inc (PRLB)
Overview
Proto Labs is a digital manufacturing company that helps customers move from product design to physical parts quickly. Its main appeal is speed: customers upload a design file, receive an automated quote, and can order custom parts in relatively small or medium volumes without going through the long setup cycles common in traditional manufacturing. The company serves product developers, engineers, and businesses that need prototypes, bridge production, and certain end-use parts.
Its business is built around several manufacturing processes, with revenue primarily coming from the production of custom parts rather than from software licensing or subscriptions. Based on recent company reporting, revenue is mainly split across the following activities:
- Injection molding: approximately 34% of revenue. This includes custom plastic parts made from molds, often used for prototyping and low-to-mid volume production.
- CNC machining: approximately 33% of revenue. This covers precision-machined metal and plastic parts.
- 3D printing: approximately 18% of revenue. This includes additive manufacturing for prototypes and complex geometries.
- Sheet metal: approximately 15% of revenue. This involves fabricated metal parts for enclosures, brackets, panels, and similar components.
Geographically, the United States remains the largest market, with Europe also contributing a meaningful share. Operationally, Proto Labs combines its own manufacturing network with outside manufacturing partners, giving it a hybrid model that aims to widen capacity and process coverage without relying only on internal factories.
The broad financial flow over recent years shows a business with fairly stable revenue around the $500 million level, but with profitability that has been more uneven. Gross profit has remained substantial, while operating income and net income have fluctuated as the company absorbed cost pressure, mix changes, and the aftereffects of earlier acquisitions. More recently, results have shown recovery rather than a full return to peak profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Metal Fabrication | |
| Market Cap ⓘ | $2.17B | |
| Beta ⓘ | 1.38 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 72.10 | 22.10 |
| P/B Ratio ⓘ | 3.13 | 1.97 |
| FCF Yield ⓘ | 2.85% | 6.38% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 2.16% | 4.79% |
| PEG ⓘ | 0.86 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.60% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 5.65% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | -12.48% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | -1.86% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -2.41% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 29.78% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 4.56% | 10.84% |
| ROA (Latest) ⓘ | 3.94% | 5.41% |
| ROIC (5Y Median) ⓘ | 2.49% | 9.38% |
| ROA (5Y Median) ⓘ | 2.19% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | -2.93 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | -3.11 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | -1.66 | 1.39 |
| Net Debt / Assets ⓘ | -15.88% | 19.28% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | 7.66% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 5.59% | 10.29% |
| Debt to Equity (Latest) ⓘ | 0.32% | 65.48% |
| Profit Margin (Latest) ⓘ | 5.44% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $61.99M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +247.67% | +61.68% |
| 12M Return (excl. last month) ⓘ | +58.34% | +12.58% |
| 6M Return ⓘ | +43.71% | 0.00% |
| Price vs. 200-Day MA ⓘ | +24.82% | +0.02% |
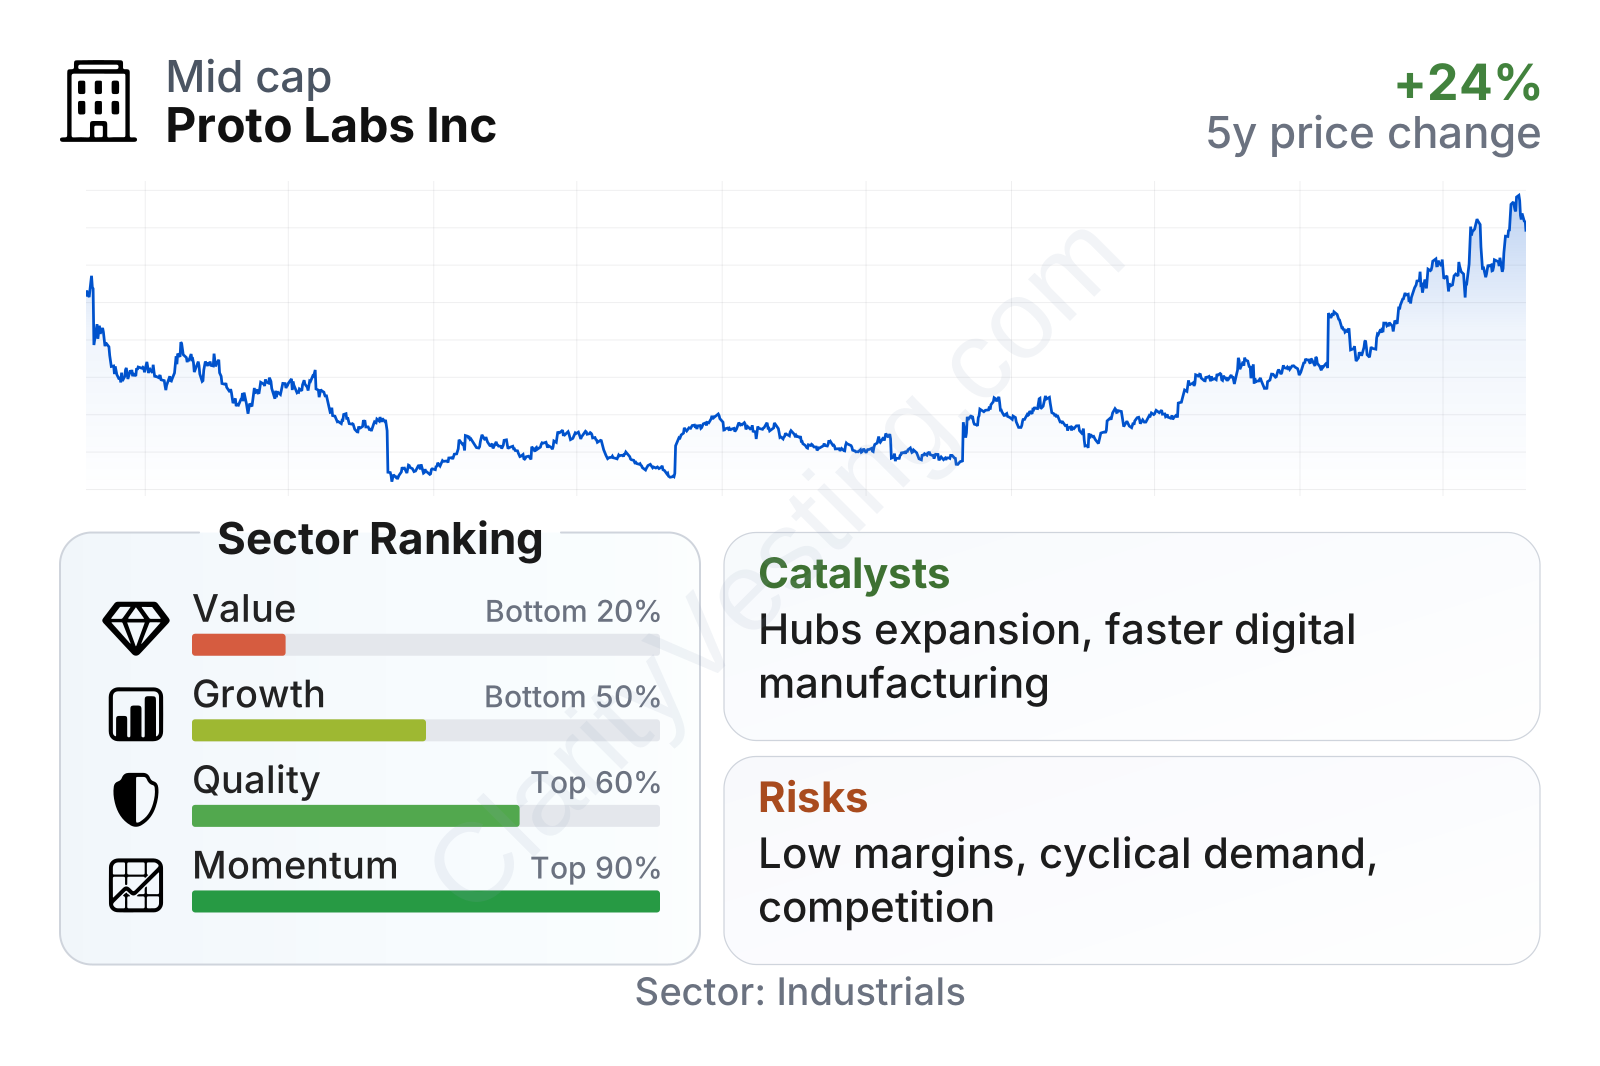
Proto Labs is a mid-sized industrial company with above-average share price momentum, but the table suggests that recent market enthusiasm is running ahead of core fundamentals. Relative to the broader industrial peer group, valuation metrics sit in the weaker part of the range, growth is mixed, and quality is helped mainly by the unusually strong balance sheet rather than by superior profitability. The company’s near-zero leverage stands out clearly, while margins and returns on capital remain below many sector peers.
Growth
Proto Labs operates in a part of manufacturing that benefits from long-term demand for faster product development, shorter design cycles, more customized production, and increasing use of digital workflows. These trends are real and durable. As more companies want to test designs quickly and avoid carrying unnecessary inventory, on-demand manufacturing becomes more relevant. That gives Proto Labs exposure to an attractive niche, even if the broader industrial economy remains cyclical.
Its strategy also makes sense on paper. The company’s automated quoting system reduces friction for customers, while its mix of in-house production and partner capacity gives it a way to serve more job types without building every capability internally. The Hubs platform, which expands access to distributed manufacturing capacity, is particularly important because it broadens Proto Labs beyond the fastest-turn niche and allows it to capture more production-oriented work.
Revenue growth has improved after a choppy period. Recent year-over-year growth has been running around 10%, which is slightly ahead of the sector median, and this is a healthier pattern than the flat-to-declining phases seen earlier. Still, the longer-term picture remains more modest, with five-year revenue-per-share growth trailing the sector median. In other words, the business is growing again, but it has not yet established a consistently strong multi-year expansion profile.
Cash generation is one of the more constructive parts of the picture. Free cash flow has improved meaningfully over the last few years, even though it has moved down somewhat from a stronger recent peak. That matters because it suggests the business can still convert revenue into cash while funding technology, automation, and platform development. A free-cash-flow track record that is improving faster than the sector average provides support for the broader growth thesis, even if accounting earnings have been less impressive.
One recent opportunity to watch is the continued expansion of manufacturing programs tied to production use cases rather than pure prototyping. If Proto Labs can increase the share of jobs that repeat over time and use the Hubs network to win more complex or larger orders, growth could become more durable and less dependent on one-off prototype demand. Management has also continued to emphasize operational efficiency and customer experience, both of which are critical in a business where speed and ease of ordering are central to the value proposition.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


