Stock Analysis · Perdoceo Education Corp (PRDO)
Overview
Perdoceo Education Corp is a U.S. higher education company focused on career-oriented learning. It operates mainly through two accredited universities: Colorado Technical University and the American InterContinental University System. The company offers online and campus-based programs, with online delivery representing the core of the business model. Its students are typically working adults seeking degrees or credentials in areas such as business, technology, healthcare, and criminal justice.
Revenue comes primarily from tuition and fees paid for academic programs, with most of that funding indirectly tied to federal financial aid programs. Based on company filings, the business is highly concentrated in its two main institutions.
- Colorado Technical University: approximately 65% to 70% of revenue. This is the larger platform and is centered on career-focused undergraduate and graduate programs, largely delivered online.
- American InterContinental University System: approximately 25% to 30% of revenue. It also focuses on online higher education, serving students across business, technology, and related fields.
- Other activities: generally below 10% of revenue. This includes smaller academic and corporate-related activities, but these are not the main earnings engine.
The business model is notable for very high gross profitability and relatively light capital needs. Over the last several years, operating income and net income have held up well even when enrollment and revenue growth were uneven. More recently, revenue has moved higher while profitability has remained strong, showing that scale and cost control still matter in this business.
The long-term pattern is encouraging: revenue was fairly stable for several years, then stepped up materially in 2025, while operating earnings improved faster than sales over time. Even with some fluctuations in expenses, the company has preserved a wide earnings cushion.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 04, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Education & Training Services | |
| Market Cap ⓘ | $2.00B | |
| Beta ⓘ | 0.72 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.60 | 18.17 |
| P/B Ratio ⓘ | 1.96 | 1.27 |
| FCF Yield ⓘ | 10.92% | 12.39% |
| Dividend Yield ⓘ | 1.95% | 2.83% |
| EBIT / EV ⓘ | 17.60% | 6.38% |
| PEG ⓘ | 0.63 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1.80% | 3.80% |
| RPS Growth (5Y CAGR) ⓘ | 6.94% | 6.20% |
| EPS Growth (5Y CAGR) ⓘ | 1.29% | -14.56% |
| BVPS Growth (5Y CAGR) ⓘ | 12.51% | 3.26% |
| Margin Growth (5Y Trend) ⓘ | 4.75% | -0.25% |
| FCF Growth (5Y CAGR) ⓘ | 4.65% | 4.65% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.86% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 18.05% | 12.58% |
| ROA (Latest) ⓘ | 13.45% | 6.32% |
| ROIC (5Y Median) ⓘ | 16.56% | 10.36% |
| ROA (5Y Median) ⓘ | 13.15% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | -3.55 | 1.91 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.47 | 2.32 |
| Net Debt / EBITDA (Latest) ⓘ | -3.05 | 1.36 |
| Net Debt / Assets ⓘ | -63.03% | 21.25% |
| EBITDA / Interest ⓘ | 44.49 | 9.61 |
| Operating Margin (Latest) ⓘ | 27.61% | 8.91% |
| Operating Margin (5Y Median) ⓘ | 26.39% | 9.53% |
| Debt to Equity (Latest) ⓘ | 5.48% | 71.66% |
| Profit Margin (Latest) ⓘ | 20.63% | 5.39% |
| Free Cash Flow (Latest) ⓘ | $217.98M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +94.76% | +15.25% |
| 12M Return (excl. last month) ⓘ | +2.86% | +2.49% |
| 6M Return ⓘ | -14.14% | +2.26% |
| Price vs. 200-Day MA ⓘ | -2.84% | +0.43% |
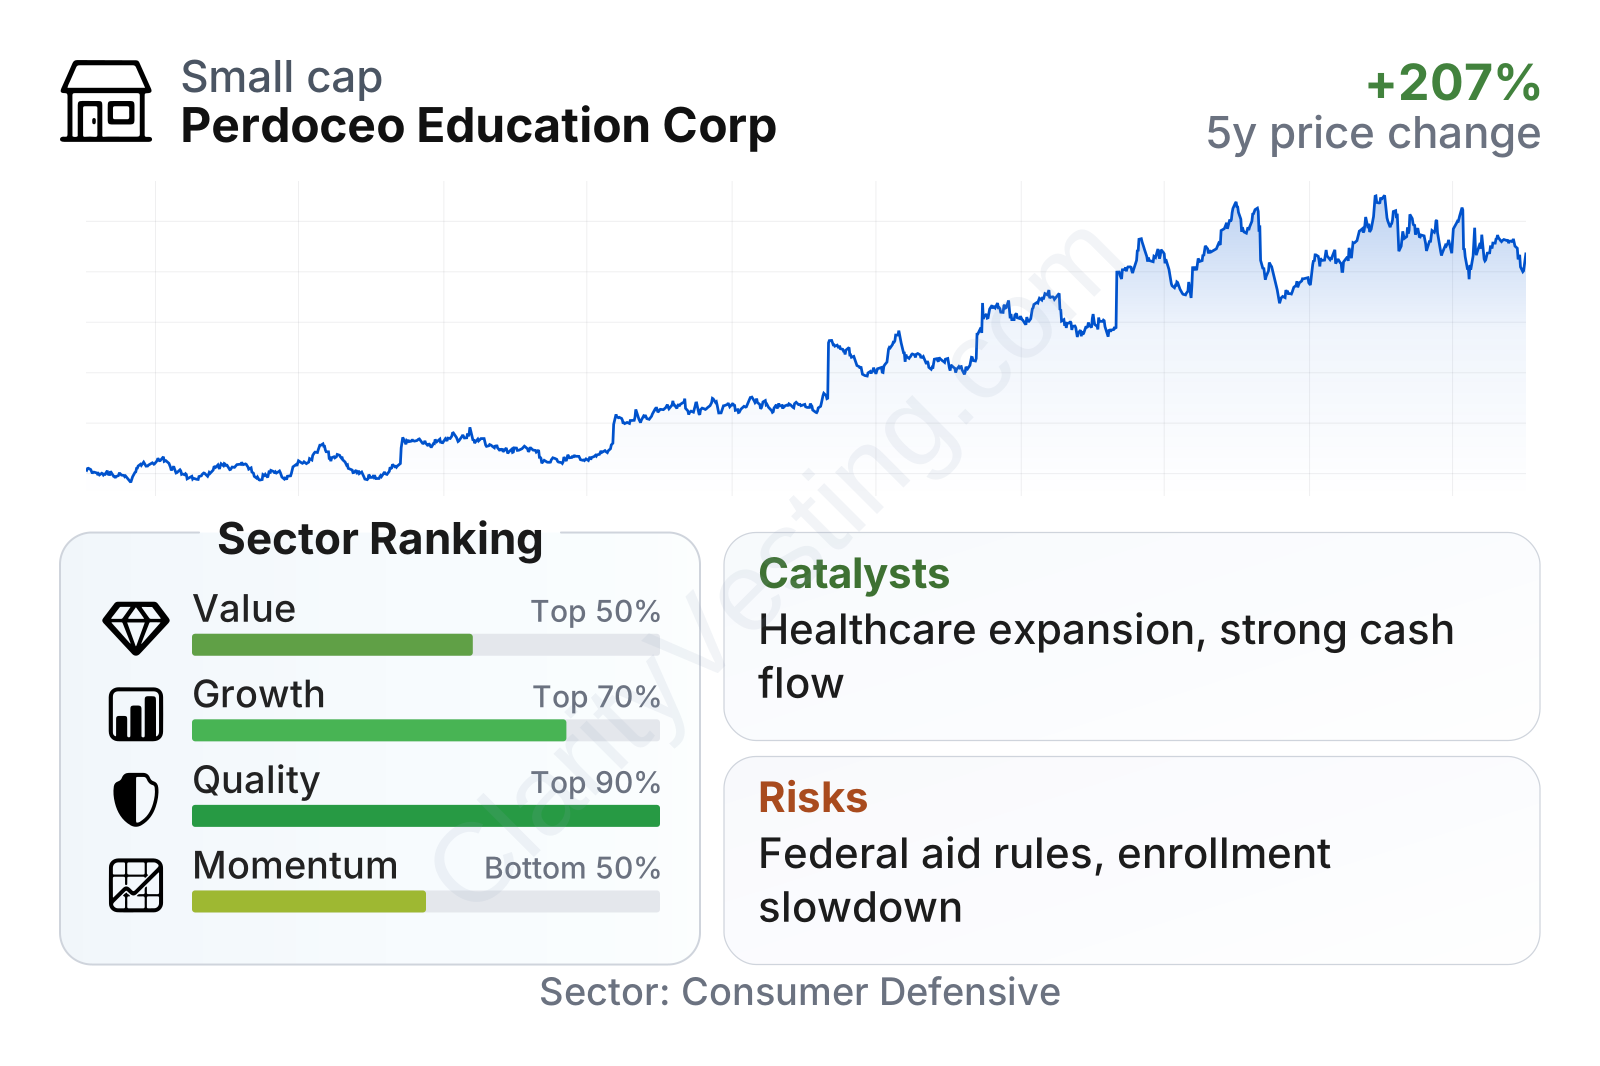
Perdoceo stands out more for quality and balance sheet strength than for rapid top-line expansion. The company ranks very well on profitability and capital efficiency, with returns on capital and assets clearly above sector medians. It also carries very little financial leverage and holds a net cash position, which is unusual in many education and training businesses. On valuation measures, earnings-based multiples remain below sector norms, while growth metrics are more mixed: recent revenue growth has cooled, but five-year trends in revenue per share, margins, and free cash flow remain solid. Share price performance over the last three years has been strong, although the shorter-term trend has softened.
Growth
The education and training market remains structurally relevant because demand for reskilling, career mobility, and flexible learning has not disappeared. Online higher education has a clear long-term role, especially for adult learners who need convenience and employer-relevant programs. That said, the sector is not a pure high-growth market. It is shaped by regulation, student affordability, labor market conditions, and competition from public universities, nonprofit institutions, and alternative credential providers.
Perdoceo’s strategy is relatively straightforward and generally coherent for this environment. It focuses on online delivery, career-oriented programs, student retention, and selective capital deployment. The company has also used acquisitions to expand beyond its core university assets, including efforts tied to healthcare education, which can open additional pathways in areas with durable workforce demand. This matters because healthcare and allied professional fields tend to be supported by labor shortages and continuing education needs.
Revenue growth has been uneven rather than linear. After a strong acceleration through much of 2025, the pace slowed sharply in early 2026 to low single digits. For long-term analysis, that matters in two ways: it shows the company can still produce bursts of expansion, but it also suggests growth may depend on enrollment cycles, marketing efficiency, and acquisition integration rather than on a consistently rising market tide.
Cash generation is a more convincing part of the growth picture. Free cash flow has trended upward over the last several years and recently moved above $200 million on a trailing basis. That gives Perdoceo flexibility to fund dividends, repurchase shares, pursue acquisitions, and absorb regulatory or operating shocks without straining the balance sheet. A recent catalyst is the company’s continued push into healthcare-oriented education assets and adjacent offerings, which could broaden its revenue base beyond the traditional university model if execution remains disciplined.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


