Stock Analysis · Pentair PLC (PNR)
Overview
Pentair is an industrial company focused on water. Its products are used to move, improve, heat, filter, and manage water in residential, commercial, industrial, and municipal settings. In simpler terms, Pentair sells equipment that helps homeowners maintain pools, helps businesses and factories treat and move water, and supports water quality systems used in homes and infrastructure.
The company has become much more focused than it was years ago. Today, water is the central theme of the business, which makes Pentair easier to understand than many diversified industrial groups. That focus also ties the company to long-term needs such as water efficiency, water quality, pool maintenance, and replacement demand for installed equipment.
Based on recent annual reporting, Pentair’s revenue mainly comes from two operating segments.
- Flow: approximately 58% of revenue. This segment includes pool equipment, pumps, filtration, flow control, and products tied to residential and commercial water movement and management.
- Water Solutions: approximately 42% of revenue. This segment includes filtration, water treatment, pressure tanks, and products aimed at improving water quality and supporting residential, commercial, and certain industrial applications.
Within those categories, pool-related products are especially important because they support a large installed base that creates recurring replacement and aftermarket demand. That matters because a company with replacement-driven sales can be more resilient than one that depends only on new construction.
The business mix has also been improving at the profit level. Over the last several years, revenue has stayed around the same broad range, but gross profit and operating income have moved higher, which suggests better pricing, improved product mix, and tighter cost control rather than simple volume expansion alone.
Pentair’s financial profile has become more efficient over time: sales have been fairly steady, while profitability has expanded. That is usually a constructive sign for a mature industrial business, especially one with a meaningful aftermarket component.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Industrial Machinery | |
| Market Cap ⓘ | $8.44B | |
| Beta ⓘ | 1.03 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 13.63 | 22.29 |
| P/B Ratio ⓘ | 2.29 | 1.98 |
| FCF Yield ⓘ | 7.97% | 6.26% |
| Dividend Yield ⓘ | 1.97% | 1.92% |
| EBIT / EV ⓘ | 7.71% | 4.83% |
| PEG ⓘ | 0.88 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -17.00% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 2.93% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -11.18% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 12.76% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 2.80% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 7.77% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 5.74% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.69% | 10.75% |
| ROA (Latest) ⓘ | 9.67% | 5.41% |
| ROIC (5Y Median) ⓘ | 19.78% | 9.37% |
| ROA (5Y Median) ⓘ | 9.61% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 2.07 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.04 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 1.80 | 1.39 |
| Net Debt / Assets ⓘ | 24.92% | 19.27% |
| EBITDA / Interest ⓘ | 13.03 | 9.58 |
| Operating Margin (Latest) ⓘ | 20.16% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 18.01% | 10.30% |
| Debt to Equity (Latest) ⓘ | 47.07% | 64.82% |
| Profit Margin (Latest) ⓘ | 16.24% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $673.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -12.32% | +67.77% |
| 12M Return (excl. last month) ⓘ | -48.81% | +12.05% |
| 6M Return ⓘ | -41.00% | 0.00% |
| Price vs. 200-Day MA ⓘ | -31.60% | +0.67% |
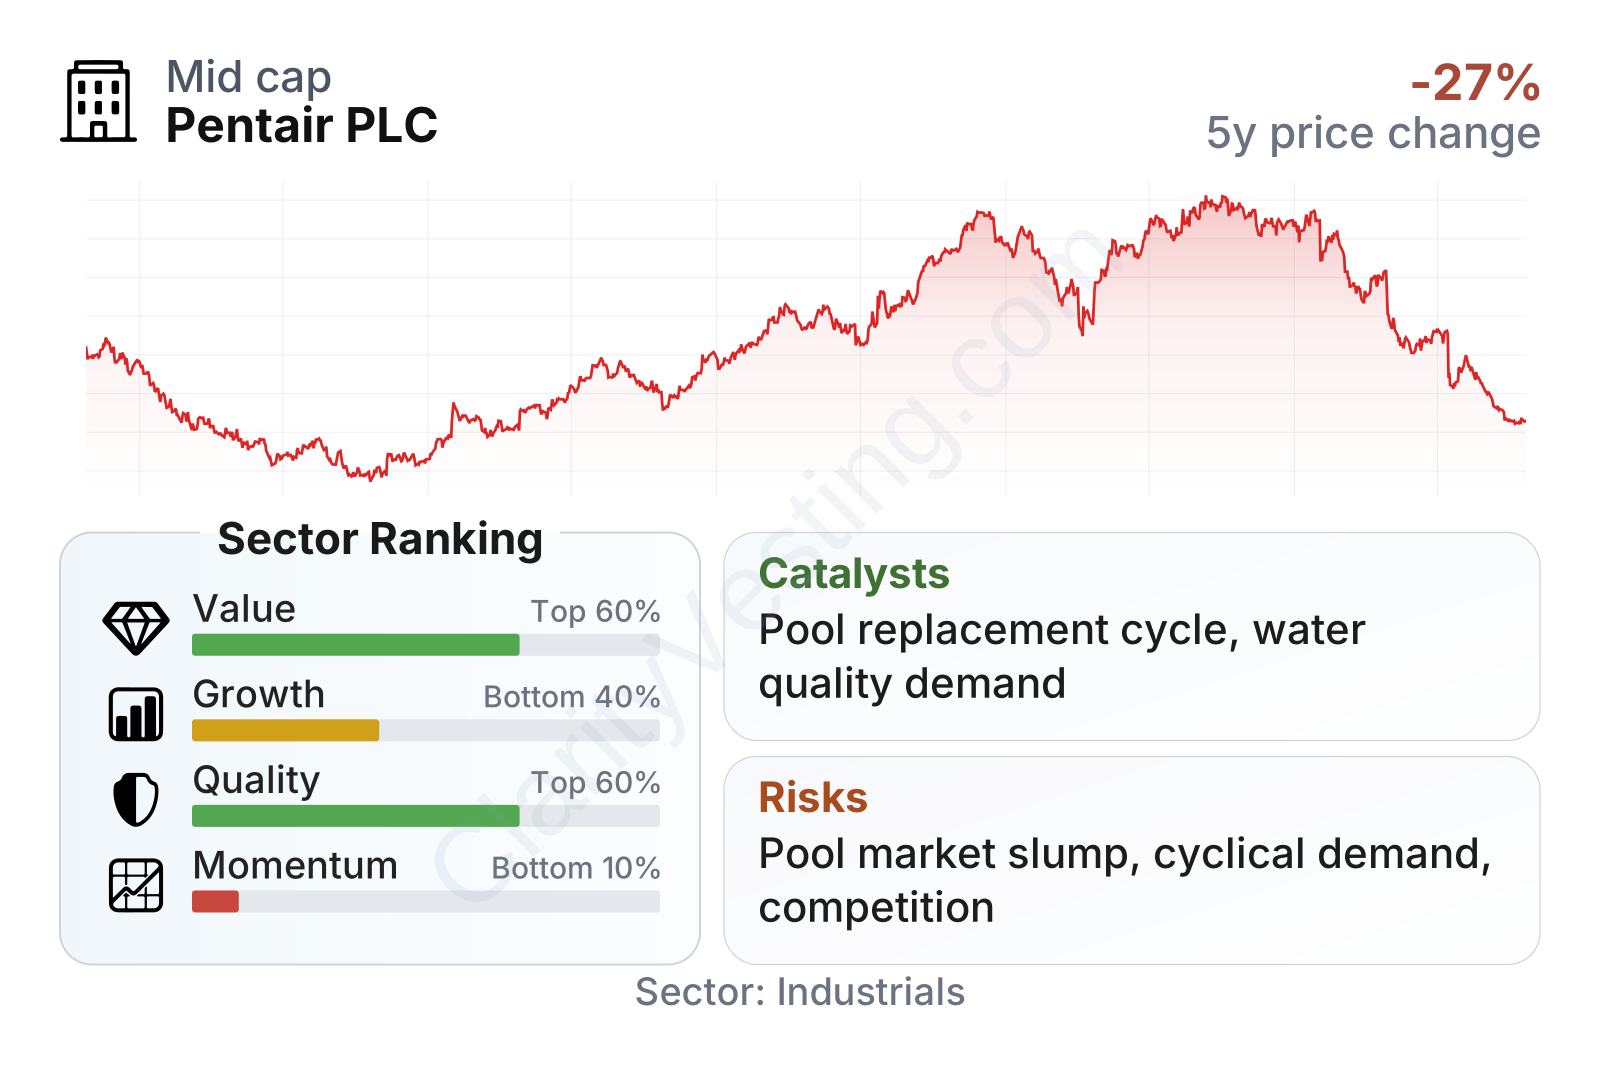
Pentair is a mid-sized industrial company with market value in the multi-billion-dollar range and share-price volatility close to the broader market. The overall picture from the latest metrics is mixed but understandable: value and quality look solid relative to the sector, while growth and especially momentum look weaker. Profitability stands out, with returns on assets and invested capital above sector medians and operating margin around 20%, which is strong for this part of the industrial universe. At the same time, recent revenue growth has been soft and the stock has materially underperformed over the last year.
Growth
Pentair operates in a sector with favorable long-term demand drivers. Water quality, water scarcity, efficiency standards, aging infrastructure, and residential pool maintenance are not short-lived themes. Even when economic conditions weaken, many water-related products remain necessary rather than optional. That gives the company exposure to a market with structural support, although not every part of the business grows at the same speed.
The company’s strategy also makes sense for future growth because it is built around a focused water portfolio instead of a broad collection of unrelated industrial assets. Pentair has emphasized higher-margin categories, operational discipline, and product innovation in connected pool systems, filtration, and water treatment. A focused strategy can help management allocate capital more clearly and improve margins even in periods when revenue growth is modest.
Recent growth has been uneven. Pentair had strong expansion in 2021 and early 2022, then growth slowed and turned negative in several later periods. More recently, there was some recovery before a sharp decline in the latest year-over-year reading. That pattern suggests the business is dealing with cyclical pressure, likely tied to housing-related demand, distributor inventory movements, or weaker pool equipment activity, rather than a broken long-term business model.
Cash generation remains an important positive. Free cash flow has risen substantially compared with earlier periods and remains strong even after coming off its recent high. For long-term analysis, this matters because cash flow gives a company flexibility to pay dividends, reduce debt, repurchase shares, and invest in product development or acquisitions without depending too heavily on outside financing.
A meaningful catalyst is the replacement cycle in pools and water systems. Pentair has a large installed base, and equipment such as pumps, filters, heaters, and treatment systems eventually needs maintenance or replacement. Another catalyst is regulation and consumer interest in cleaner and more efficient water systems, which can support premium products. If housing-related markets stabilize, Pentair could benefit from both replacement demand and a healthier new-equipment environment.
Recent company communications have also highlighted continued attention to productivity, portfolio simplification, and margin expansion. That does not guarantee fast top-line growth, but it can improve earnings power if demand normalizes.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


