Stock Analysis · PT Merdeka Copper Gold Tbk (PMCGF)
Overview
PT Merdeka Copper Gold Tbk is an Indonesian mining and metals company focused on copper, gold, nickel, and related mineral processing. Its asset base is centered in Indonesia, and the business has evolved from a precious-metals producer into a broader platform tied to both traditional mining demand and the electric-vehicle supply chain. That makes the company more than a simple gold miner: it now has exposure to battery materials, industrial metals, and downstream processing.
The company’s revenue mix has shifted meaningfully as nickel-related operations expanded. Based on recent annual reporting and company disclosures, the main sources of revenue appear to be:
- Nickel products and nickel-related processing: approximately 70% to 85%. This includes nickel pig iron, nickel matte, and other nickel materials produced through subsidiaries and associated processing assets.
- Copper and gold from mining operations: approximately 10% to 20%. This mainly comes from the Tujuh Bukit mining complex, where copper and gold are core underlying resources.
- Other mining and support activities: approximately 5% to 10%. This can include silver by-products, services, and smaller operating contributions across the group.
The broad pattern is clear even if exact percentages vary by year: Merdeka is increasingly a nickel-and-copper growth company, with gold still important but no longer the dominant economic driver. That matters for long-term analysis because the company is positioning itself around metals linked to electrification and industrial development, not only precious metals.
Over the last several years, revenue has expanded sharply, but costs have also risen quickly. The business has therefore become much larger without yet converting that scale into steady net profit or free cash flow. This is typical of a company in a heavy investment phase, but it raises the importance of execution and balance-sheet discipline.
The business has grown from a few hundred million dollars in annual revenue to well above $1 billion, which shows how rapidly the operating footprint has expanded. At the same time, cost of revenue and interest expense have increased substantially, which helps explain why accounting profit has remained under pressure despite higher sales.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Industrial Metals & Mining | |
| Market Cap ⓘ | $2.44B | |
| Beta ⓘ | 0.92 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.92 |
| P/B Ratio ⓘ | 2.87 | 1.66 |
| FCF Yield ⓘ | -5.46% | 5.83% |
| Dividend Yield ⓘ | 1.00% | 2.07% |
| EBIT / EV ⓘ | 5.29% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 121.90% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 47.88% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | -0.59% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -8.54% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 8.70% | 9.59% |
| ROA (Latest) ⓘ | -0.02% | 4.92% |
| ROIC (5Y Median) ⓘ | N/A | 7.91% |
| ROA (5Y Median) ⓘ | -0.47% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 5.32 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 8.98 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 5.25 | 0.93 |
| Net Debt / Assets ⓘ | 27.74% | 13.69% |
| EBITDA / Interest ⓘ | 2.20 | 12.38 |
| Operating Margin (Latest) ⓘ | 15.62% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 7.77% | 11.82% |
| Debt to Equity (Latest) ⓘ | N/A | 40.30% |
| Profit Margin (Latest) ⓘ | 2.26% | 6.38% |
| Free Cash Flow (Latest) ⓘ | -$133.27M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -48.35% | +73.47% |
| 12M Return (excl. last month) ⓘ | +0.70% | +27.59% |
| 6M Return ⓘ | +0.70% | -4.02% |
| Price vs. 200-Day MA ⓘ | +0.44% | -0.65% |
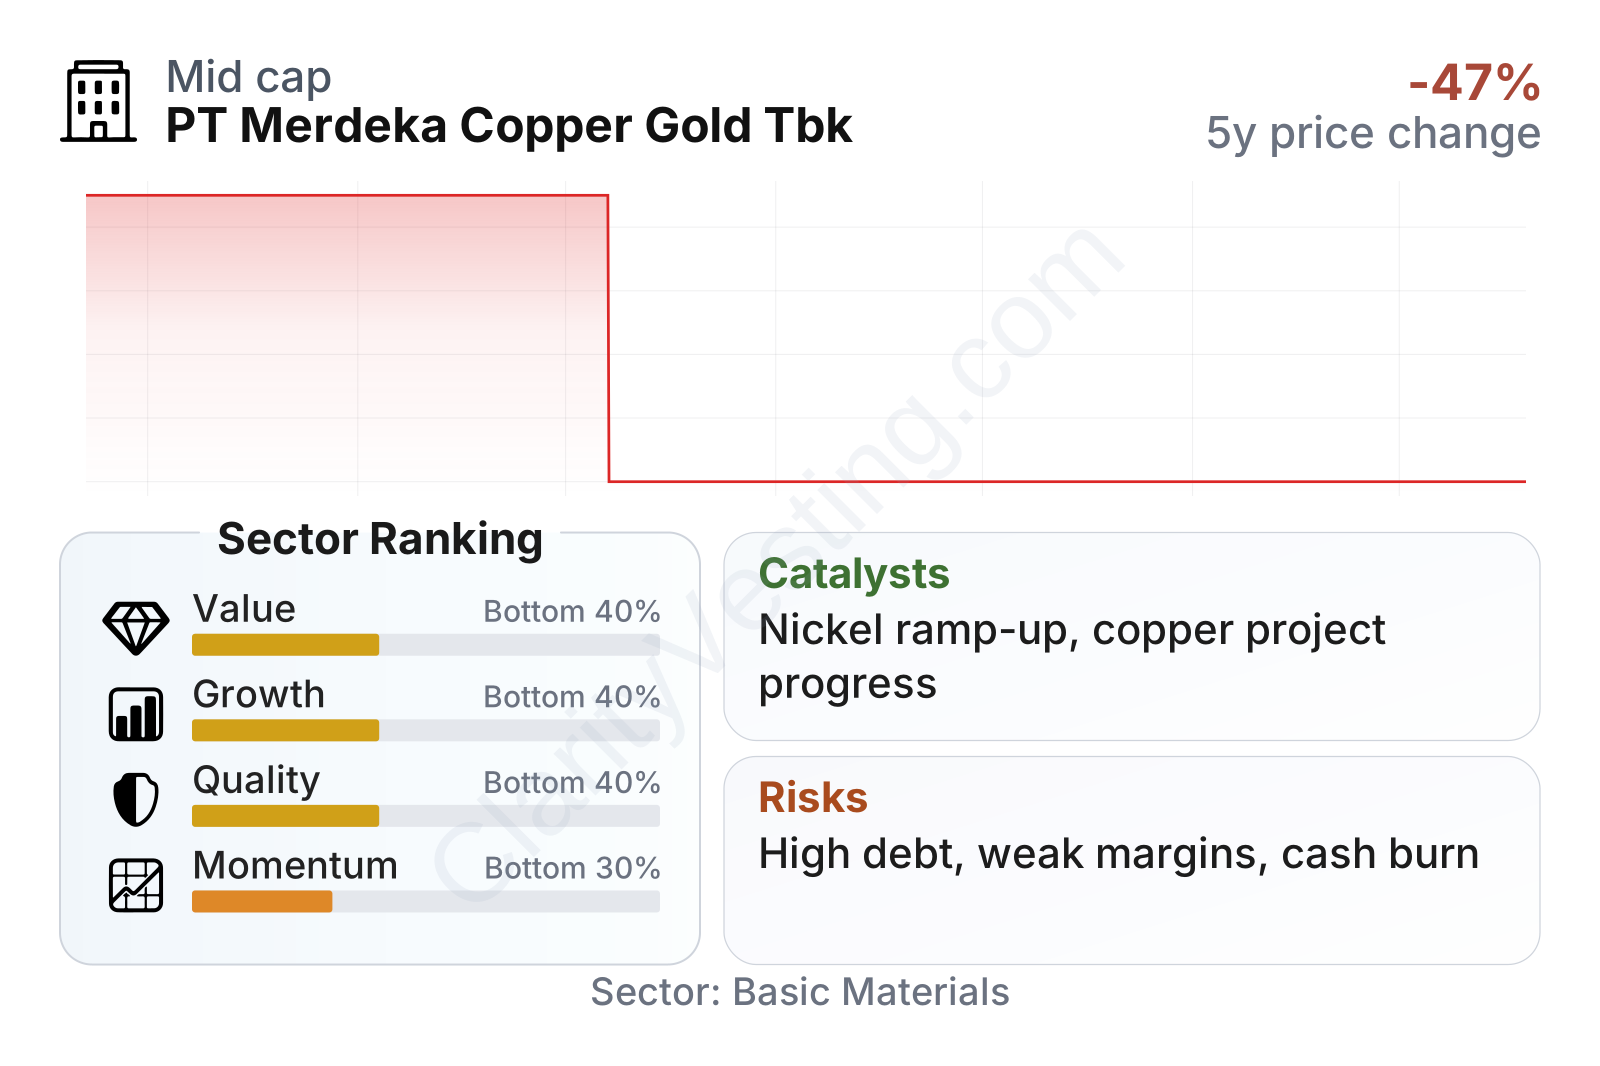
The overall picture is mixed. Merdeka is a mid-sized mining company with market behavior that has been less volatile than some commodity names, but its current factor profile is weak relative to much of the sector. Value metrics do not look especially attractive on a cash-flow basis, quality is held back by high leverage and thin profitability, and momentum has been notably weak. The strongest operating signal is top-line expansion over recent years, but that growth has not yet translated into consistently strong returns on assets or dependable cash generation.
The stock-price history also reflects that tension. The shares have been broadly flat at a low level after a significant drop, suggesting that the market is waiting for clearer proof that expansion projects can produce durable earnings rather than just larger revenue.
Growth
Merdeka operates in segments that should remain strategically important over the long run. Copper is essential for power grids, construction, and electrification. Nickel remains a key material for stainless steel and, depending on battery chemistry trends, an important input for parts of the EV battery chain. Gold adds a different economic exposure and can help diversify commodity risk inside the portfolio of assets.
The company’s strategy broadly makes industrial sense. Rather than staying concentrated in one mine or one metal, it has built a more diversified minerals platform and moved further into processing. In Indonesia, that approach fits a national policy trend that favors more domestic value-added production rather than simply exporting raw ore. If executed well, that can improve margins over time and make the company more relevant in regional supply chains.
Recent revenue growth has been volatile, which is normal in mining and processing businesses where production timing, grade, and commodity prices can all move results sharply from one period to another. Even so, the broader trend still points to a company that has become materially larger than it was a few years ago. The latest year-over-year reading shows a return to growth after several uneven quarters, which may indicate that newer operations are starting to contribute more consistently.
Free cash flow remains negative, but the losses have narrowed considerably from earlier levels. That improvement is important. It suggests the company may be moving through the heaviest part of its investment cycle, although it has not yet reached a point where the business is clearly self-funding. For a long-term view, this is one of the most important metrics to watch because mining expansions often look attractive in revenue terms long before they prove themselves in cash terms.
As for catalysts, the most important ones are operational rather than speculative. Higher production from nickel and copper assets, a smoother ramp-up of downstream processing, and stronger metal prices could all meaningfully improve earnings power. Public company updates in 2026 also indicate continued progress across strategic projects tied to Indonesian battery materials and copper development. If those projects keep moving on schedule, Merdeka’s future revenue base could become more diversified and potentially more resilient.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


