Stock Analysis · PLGO (PLGO)
Overview
PLGO is a diversified insurance company in the Financial Services sector. In practical terms, that means it collects premiums from policyholders, invests part of that float, and aims to earn a profit from underwriting discipline, fee-based activities, and investment income. For a long-term reader, the business is easier to think about as a balance between two engines: insurance operations and capital allocation.
Public financial disclosures indicate that revenue is primarily tied to insurance-related activities, with additional support from investment returns and other operating income. The exact mix can shift meaningfully from year to year because insurers can be affected by policy growth, claims experience, reserve movements, and mark-to-market or realized investment results.
The broad revenue sources can be framed as follows:
- Insurance premiums and related underwriting revenue: the core activity, incorporating policy sales across the company’s insurance lines, renewal premiums, and other insurance operating revenue. This appears to be the dominant source of sales.
- Investment income: income generated from investing the company’s asset base, an important secondary earnings contributor for most insurers.
- Other operating and fee-related income: smaller items that can include service fees, ancillary business revenue, or gains connected to operations.
One important point for PLGO is that reported revenue and profit have shown unusually large swings over the past several years. Total revenue moved from about $1.2 billion in 2021 to $1.5 billion in 2022, spiked above $3.3 billion in 2023, then moved back closer to $2.1 billion in 2024 and 2025. Net income followed a similar pattern, with an outsized jump in 2023 before returning to more normal levels afterward. That suggests readers should be cautious about treating a single strong year as the steady baseline for the business.
Even so, the recent picture is not weak. By 2025, the company was still producing more than $2.1 billion of revenue, more than $225 million of net income, and solid operating profitability, while free cash flow remained strong. For a long-term assessment, that combination matters more than any one unusual year.
The long-term pattern shows a business that remains profitable but not perfectly smooth. After the unusual 2023 surge, the company’s 2024 and 2025 results look more grounded, with operating income and net income still well above 2021 and 2022 levels. That points to a company with earnings power, but also with accounting and operating variability that needs close monitoring.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Insurance - Diversified | |
| Market Cap ⓘ | $2.05B | |
| Beta ⓘ | 0.29 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 6.08 | 12.26 |
| P/B Ratio ⓘ | 0.95 | 1.23 |
| FCF Yield ⓘ | 30.77% | 10.40% |
| Dividend Yield ⓘ | 2.43% | 3.02% |
| EBIT / EV ⓘ | 22.92% | 8.14% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.30% | 9.35% |
| RPS Growth (5Y CAGR) ⓘ | 19.12% | 12.19% |
| EPS Growth (5Y CAGR) ⓘ | -30.21% | -9.53% |
| BVPS Growth (5Y CAGR) ⓘ | 6.79% | 4.99% |
| Margin Growth (5Y Trend) ⓘ | 5.19% | -3.86% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.81% |
| DPS Growth (5Y CAGR) ⓘ | 128.33% | 8.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.38% | 9.49% |
| ROE (Latest) ⓘ | 17.28% | 13.90% |
| ROA (Latest) ⓘ | 3.45% | 1.55% |
| ROIC (5Y Median) ⓘ | N/A | 7.86% |
| ROE (5Y Median) ⓘ | 6.96% | 12.17% |
| ROA (5Y Median) ⓘ | 1.45% | 1.30% |
| Net Debt / EBIT (Latest) ⓘ | 0.53 | 0.96 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.10 | 0.73 |
| Net Debt / EBITDA (Latest) ⓘ | 0.54 | 0.92 |
| Operating Margin (Latest) ⓘ | 23.90% | 22.30% |
| Operating Margin (5Y Median) ⓘ | 9.69% | 24.63% |
| Debt to Equity (Latest) ⓘ | 32.45% | 58.56% |
| Profit Margin (Latest) ⓘ | 15.94% | 26.57% |
| Free Cash Flow (Latest) ⓘ | $630.10M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +87.41% | +88.33% |
| 12M Return (excl. last month) ⓘ | +45.87% | +19.38% |
| 6M Return ⓘ | +24.52% | +4.75% |
| Price vs. 200-Day MA ⓘ | +13.71% | +3.50% |
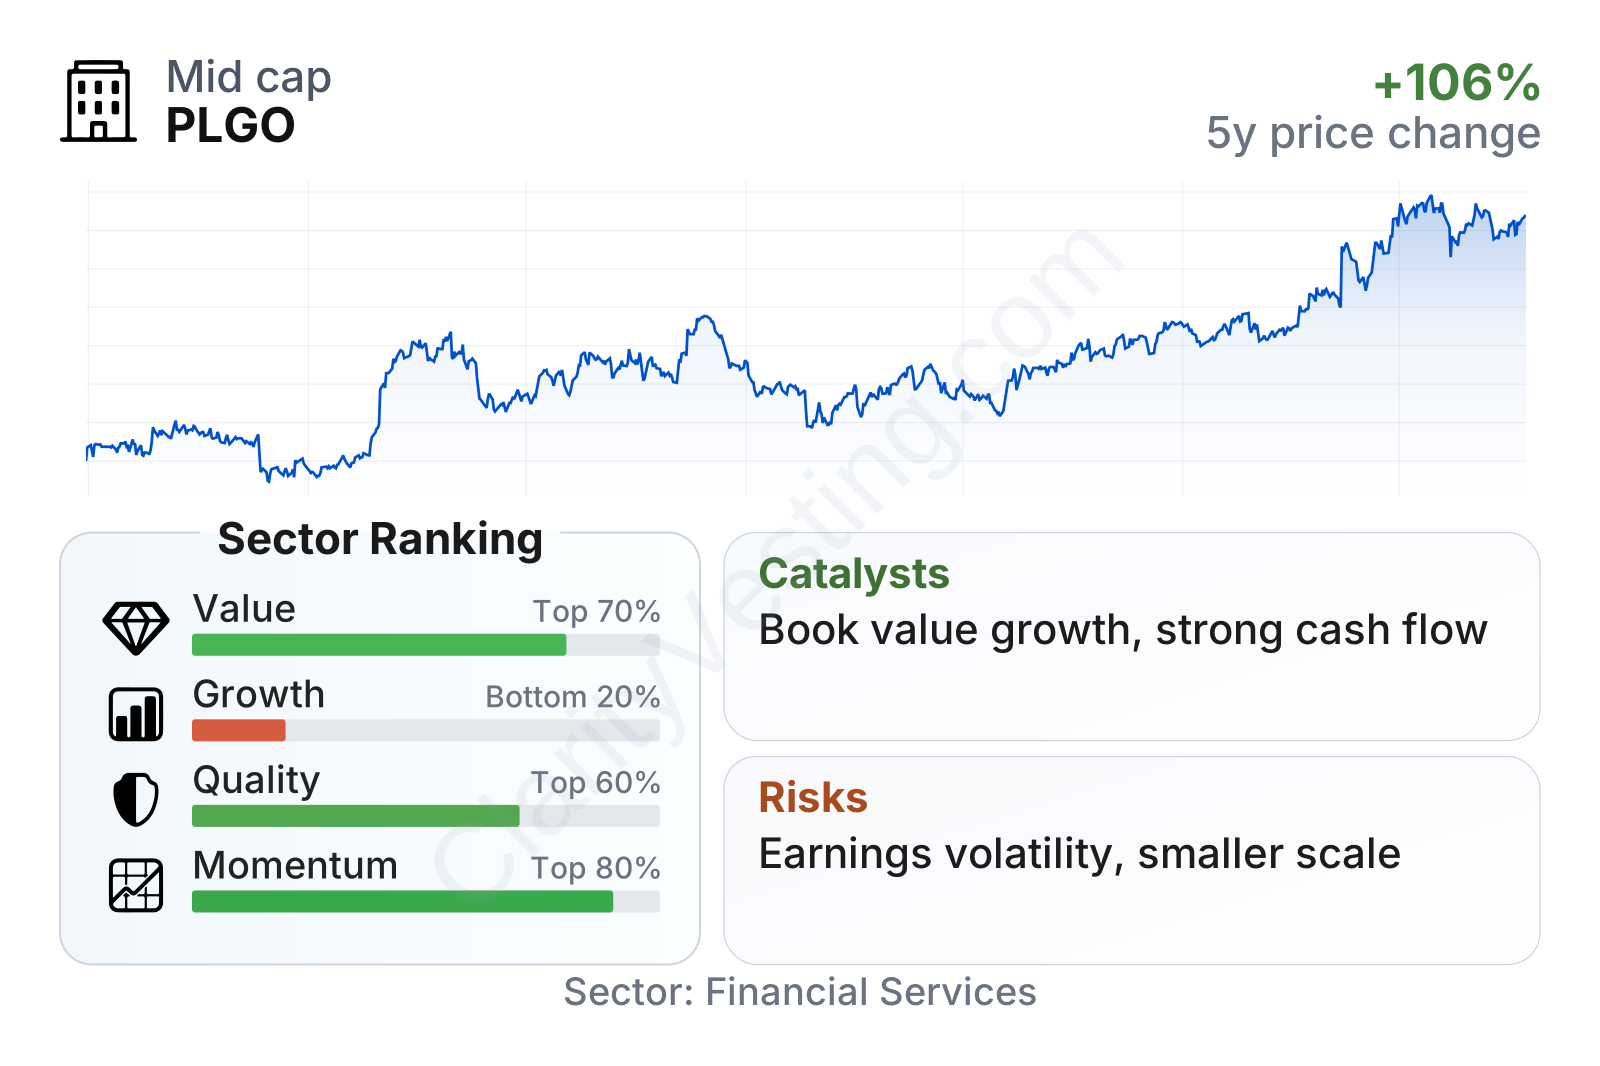
PLGO sits in the mid-cap range, and its share price has been trending upward over the last three years, with especially strong momentum over the last 6 to 12 months. On valuation, the company screens cheaper than the sector on both earnings and book value, while cash generation looks notably strong relative to its market value. Quality is respectable rather than elite: returns on equity and assets are currently above sector medians, leverage is moderate, and operating margin is slightly ahead of peers. The weaker area is growth consistency. Revenue growth is acceptable, but the longer-term earnings record is much less steady, which helps explain why the market has not awarded it a richer multiple.
Growth
The insurance industry is a mature sector rather than a hyper-growth one, but that does not mean growth is absent. Well-run insurers can expand through pricing discipline, product mix changes, acquisitions, better claims management, and higher investment income when rates are supportive. In that context, PLGO appears to be operating in a sector where durable compounding is possible, but usually with less excitement and more dependence on execution than in fast-growing technology fields.
PLGO’s strategy appears sensible if the objective is steady long-term value creation. Revenue per share has grown at a rate noticeably above the sector median over five years, and book value per share has also advanced faster than the industry median. That is important for an insurer because book value often provides a cleaner signal of value creation than revenue alone.
Earnings per share have been volatile. The company posted a very strong level in 2023, dropped sharply in 2024, and then recovered in 2025, while the 2026 year-to-date reading suggests profitability remains positive. This pattern supports a mixed conclusion: PLGO has clear earnings capacity, but it has not yet shown a smooth upward progression that would normally justify a premium growth label.
Book value per share has been much steadier than earnings. After a dip in 2022, it improved strongly in 2023 and has remained on an upward path since then. For a long-term insurance investor, that stability is meaningful because it suggests that despite earnings swings, the underlying capital base has been building over time.
Another potential growth support is cash generation. PLGO’s free cash flow yield is far above the sector median, and free cash flow in absolute dollars is sizable for a company of this scale. Strong cash generation gives management flexibility to support dividends, strengthen the balance sheet, repurchase shares, or pursue acquisitions if attractive opportunities arise.
There is also a possible external catalyst from the current insurance environment. Across many insurance lines, the industry has been trying to push through higher pricing to offset claims inflation and loss volatility. If PLGO has adequate underwriting discipline and can retain business while rates rise, that can support margin improvement without requiring explosive policy growth.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


