Stock Analysis · Pacira BioSciences Inc (PCRX)
Overview
Pacira BioSciences is a pharmaceutical company focused on non-opioid pain management and related hospital-based treatments. Its core business is selling branded products used around surgery and other procedures to reduce pain, improve recovery, and lower reliance on opioids. The company also has a smaller business that supports product development and manufacturing partnerships through its drug delivery technology.
Pacira’s revenue base is concentrated in a few products, which makes the business fairly easy to understand. Based on the company’s most recent annual filings and 2026 quarterly updates, the main sources of revenue are approximately:
- EXPAREL: about 75% to 80% of revenue. This is the company’s largest product by far, a long-acting local anesthetic used for postsurgical pain control.
- ZILRETTA: about 10% to 15% of revenue. This is an extended-release corticosteroid injection for osteoarthritis knee pain.
- iovera°: about 5% to 10% of revenue. This device-based pain treatment uses focused cold therapy to temporarily block nerve signals.
- Other: a small remaining share from collaboration, licensing, and contract manufacturing activities, including work tied to its delivery technology platform.
The business mix shows a company with one dominant franchise supported by smaller growth assets. That concentration is important: it creates strong commercial focus, but it also means performance still depends heavily on EXPAREL.
The multiyear income flow also shows a useful pattern. Revenue has continued to rise, gross profit has improved, and cost of revenue has become a smaller share of sales over time. However, operating expenses increased sharply in 2024 before easing in 2025, which helps explain why accounting earnings have looked much more volatile than top-line growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Drug Manufacturers - Specialty & Generic | |
| Market Cap ⓘ | $1.45B | |
| Beta ⓘ | 0.25 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 104.00 | 24.79 |
| P/B Ratio ⓘ | 2.18 | 3.08 |
| FCF Yield ⓘ | 12.36% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 2.59% | 0.57% |
| PEG ⓘ | 11.21 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 6.20% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 7.97% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -21.61% | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | -0.98% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | -11.44% | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | 14.38% | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 2.97% | 3.24% |
| ROA (Latest) ⓘ | 1.15% | 3.01% |
| ROIC (5Y Median) ⓘ | 3.76% | 4.60% |
| ROA (5Y Median) ⓘ | 0.85% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | 6.97 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 7.88 | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | 1.80 | 1.00 |
| Net Debt / Assets ⓘ | 16.58% | 5.45% |
| EBITDA / Interest ⓘ | 8.30 | 9.64 |
| Operating Margin (Latest) ⓘ | 3.97% | 9.27% |
| Operating Margin (5Y Median) ⓘ | 7.33% | 7.38% |
| Debt to Equity (Latest) ⓘ | 61.33% | 28.58% |
| Profit Margin (Latest) ⓘ | 1.96% | 3.59% |
| Free Cash Flow (Latest) ⓘ | $179.51M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +22.57% | +42.80% |
| 12M Return (excl. last month) ⓘ | -10.35% | +18.50% |
| 6M Return ⓘ | +55.06% | +7.57% |
| Price vs. 200-Day MA ⓘ | +50.21% | +5.12% |
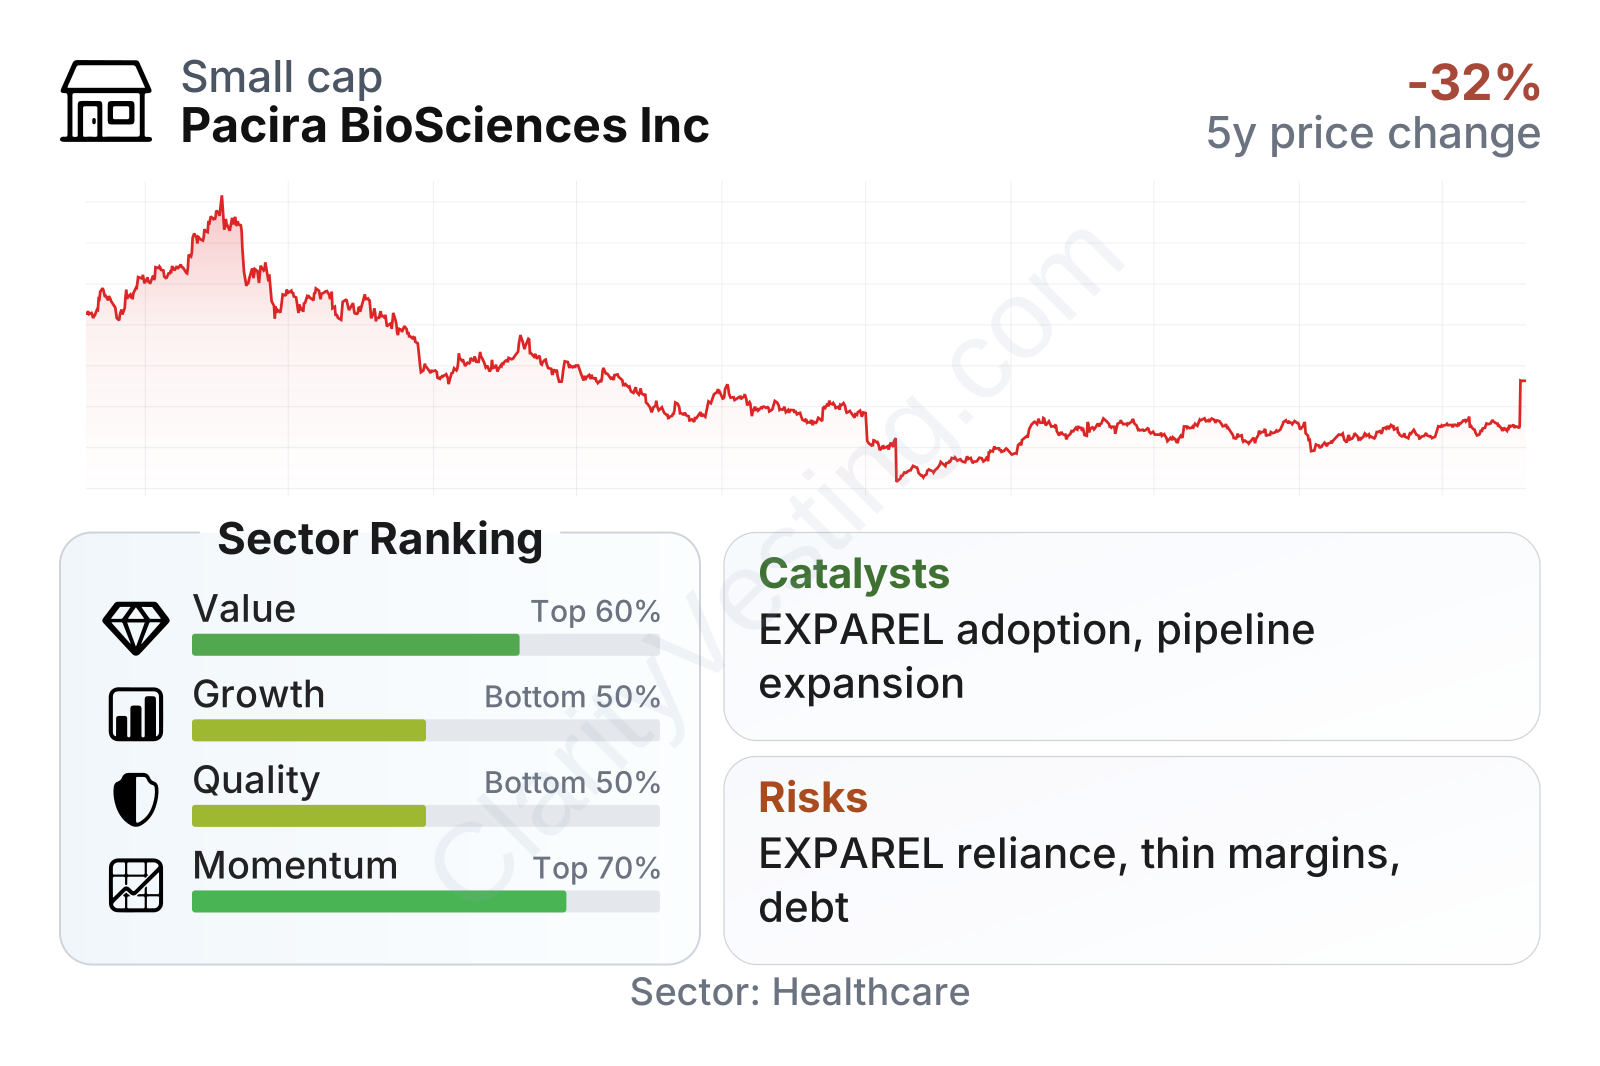
Pacira is a mid-sized healthcare company with unusually low share-price volatility for a biotech-related name, as reflected by its very low beta. On valuation and cash generation, the picture is mixed: the earnings multiple is high versus the sector median, but free cash flow metrics look much stronger than typical peers. Growth and quality rankings sit in the lower half of the sector, mainly because margins and returns on capital remain modest while debt is still above industry norms. Market momentum has improved meaningfully in recent months, suggesting sentiment has recovered from the sharp stock decline seen between 2022 and 2024.
Growth
Pacira operates in an area with long-term relevance. Hospitals and surgeons continue to look for ways to control pain while reducing opioid use, shortening recovery time, and managing total procedure costs. That gives the company exposure to a healthcare need that is unlikely to disappear. The broader sector is not a high-growth digital market, but demand for effective non-opioid pain solutions remains strategically attractive.
The company’s growth strategy is logical. It is built around expanding the use of EXPAREL, improving penetration across surgical settings, and adding support from adjacent products such as ZILRETTA and iovera°. Pacira has also been developing new opportunities from its delivery technology and pipeline, which could broaden the business beyond its current product concentration if execution is successful.
Recent revenue growth has been positive but not explosive. After very strong expansion in 2021 and 2022, growth slowed materially, then settled into a more moderate mid-single-digit range. That profile suggests Pacira has moved from a rapid post-pandemic recovery phase into a more mature commercial stage. For a long-term view, that means future upside will likely depend less on simple volume recovery and more on new indications, better sales execution, and additional products.
Cash generation is one of the more encouraging parts of the profile. Free cash flow remains solid in absolute terms even after coming off its recent peak, and its five-year compound growth has been much stronger than the sector median. That matters because it gives Pacira more flexibility to fund research, support commercialization, and manage debt without depending heavily on new share issuance.
A meaningful catalyst is the company’s continued effort to deepen adoption of its non-opioid portfolio in orthopedic and soft-tissue procedures, where hospital protocols can influence usage over time. Another catalyst is pipeline progress tied to localized, long-acting pain treatment approaches. Recent company updates in 2026 have also kept attention on execution, profitability recovery, and product expansion rather than on a shrinking business, which is an important distinction for a company coming off a difficult period.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


