Stock Analysis · Pan American Silver Corp (PAAS)
Overview
Pan American Silver Corp is a precious-metals mining company that produces silver and gold, with additional output of zinc, lead, and copper as by-products. Its mines and development projects are spread across the Americas, giving it geographic diversification across countries such as Mexico, Peru, Bolivia, Argentina, Canada, Brazil, Chile, and Guatemala. In practical terms, the business finds metal deposits, develops mines, extracts ore, processes it, and sells refined metal or concentrates into global commodity markets.
Revenue is driven mainly by the metals it sells, and the mix can shift meaningfully with production volumes, mine sequencing, and metal prices. After the Yamana transaction, gold became a larger part of the business than in earlier years, while silver remains central to the company’s identity and long-term strategy.
- Gold: approximately 55% to 65% of revenue in the latest business mix. This includes output from key gold-heavy operations added or expanded in recent years.
- Silver: approximately 25% to 35% of revenue. This comes from primary silver mines and silver produced alongside other metals.
- Zinc, lead, and copper: combined approximately 5% to 15% of revenue, depending on prices and mine-level output. These are largely by-products sold from polymetallic operations.
- Other mining-related items: usually a very small share, including treatment arrangements and minor commercial adjustments.
The business model is inherently tied to commodity prices, but scale matters. Pan American Silver is one of the larger listed precious-metals miners, with a broad operating base and a meaningful reserve portfolio. Over the last few years, the company’s revenue base has expanded strongly, and profitability has improved sharply after a weak period in 2022 and 2023. That rebound reflects both higher metal prices and better operating performance.
The long-term picture shows a business that moved from pressure in 2022 and 2023 to a much stronger earnings profile in 2024 and especially 2025. Revenue has climbed materially, while operating income and net income recovered from losses to strong positive levels. That swing matters because miners often look inexpensive or expensive at the wrong point in the cycle; here, the recent improvement is not only a price effect but also a reflection of better cost absorption and a larger production base.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $18.36B | |
| Beta ⓘ | 1.58 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 13.10 | 16.92 |
| P/B Ratio ⓘ | 2.50 | 1.66 |
| FCF Yield ⓘ | 8.36% | 5.83% |
| Dividend Yield ⓘ | 1.40% | 2.07% |
| EBIT / EV ⓘ | 9.37% | 6.38% |
| PEG ⓘ | 7.02 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 38.40% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 5.61% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 123.05% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 9.98% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 20.58% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 64.24% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 8.26% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 17.71% | 9.59% |
| ROA (Latest) ⓘ | 14.31% | 4.92% |
| ROIC (5Y Median) ⓘ | 2.30% | 7.91% |
| ROA (5Y Median) ⓘ | 1.55% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | -0.38 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.21 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | -0.30 | 0.93 |
| Net Debt / Assets ⓘ | -7.14% | 13.69% |
| EBITDA / Interest ⓘ | 35.85 | 12.38 |
| Operating Margin (Latest) ⓘ | 44.17% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 15.23% | 11.82% |
| Debt to Equity (Latest) ⓘ | 11.43% | 40.30% |
| Profit Margin (Latest) ⓘ | 32.03% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $1.54B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +200.97% | +73.47% |
| 12M Return (excl. last month) ⓘ | +35.48% | +27.59% |
| 6M Return ⓘ | -20.98% | -4.02% |
| Price vs. 200-Day MA ⓘ | -16.11% | -0.65% |
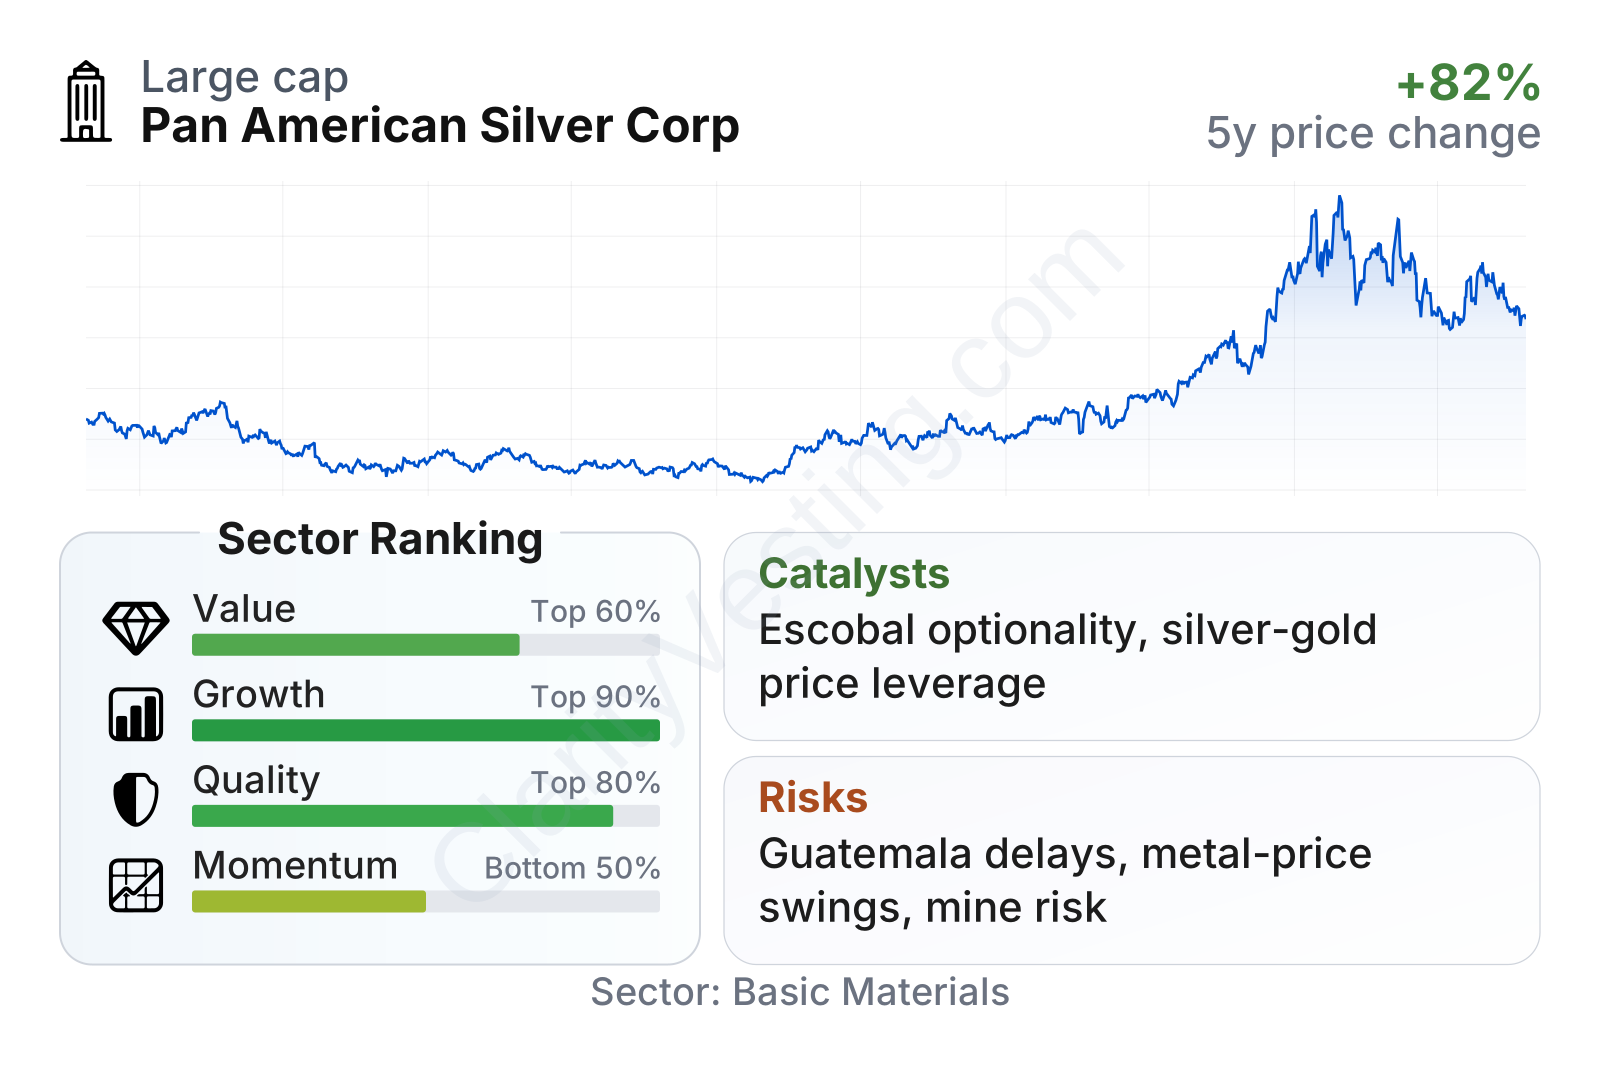
Pan American Silver currently combines strong growth and solid operating quality with only middle-of-the-pack market momentum. The company stands out for high returns on capital and assets versus much of the sector, very low leverage, and unusually strong interest coverage. On valuation measures, the picture is mixed: earnings and cash-flow multiples look reasonable relative to peers, while the price-to-book ratio is richer than the sector median, which is common when the market gives credit to asset quality and improved profitability.
The share price has been volatile, which is normal for a mining company exposed to silver and gold prices. Over a multi-year period, the stock has risen sharply, but recent months show a pullback from highs. That pattern suggests the market has already recognized much of the operational recovery, while still reacting quickly to changes in metal prices and risk sentiment.
Growth
Pan American Silver operates in a sector with durable long-term relevance. Silver benefits from both investment demand and industrial uses, especially in electronics, solar applications, and electrification-related systems. Gold remains supported by central bank buying, jewelry demand, and its role as a store of value during inflation and geopolitical uncertainty. That does not create steady growth in the way software or healthcare sometimes can, but it does support a long runway for well-positioned low-cost producers with sizable reserve lives.
The company’s strategy broadly makes sense for future growth. Management has built a larger, more diversified producer rather than depending on one flagship mine. That matters because mining is rarely smooth: grades change, permitting can slow projects, and some sites will perform better than others in any given year. A wider asset base can reduce the impact of problems at a single operation. The company also retains optionality from suspended or developing assets, which can become more valuable when metal prices are high or local conditions improve.
Revenue growth has been strong recently. After a difficult period with declines and major swings, year-over-year sales growth accelerated markedly from mid-2023 onward and stayed well above the sector median into 2026. That supports the view that the current earnings base is not coming from one isolated quarter but from a broader operating upturn.
Cash generation is another important positive. Free cash flow was weak or negative during the tougher part of the cycle, but it has improved dramatically and recently moved into a very strong range. For a miner, this is critical because free cash flow funds exploration, project development, dividends, and balance-sheet resilience without requiring heavy new borrowing or equity issuance.
A major catalyst remains the company’s leverage to silver and gold prices. Because many mine costs are relatively fixed in the short term, higher realized prices can translate into disproportionately stronger margins and cash flow. Another catalyst is operational normalization at assets that have faced interruptions or lower throughput in the past. If production reliability improves while metal prices stay supportive, earnings power can expand further.
There is also an asset-specific angle. Escobal in Guatemala has long been viewed as one of the most significant silver assets in the industry, and any credible progress toward a full restart would be a meaningful development for the company’s long-term production profile. That is not something to treat as near-certain, but it remains one of the clearest upside variables tied specifically to Pan American Silver rather than to the whole sector.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


