Stock Analysis · Orezone Gold Corp (ORZCF)
Overview
Orezone Gold Corp is a gold producer focused on West Africa. Its core asset is the Bomboré mine in Burkina Faso, where the company mines ore, processes it, and sells gold. In practical terms, Orezone is a single-commodity business: it is tied mainly to the volume of gold it can produce, the cost of producing each ounce, and the market price of gold.
The company’s revenue base is currently simple and concentrated.
- Gold sales: approximately 100% of revenue. This comes from gold produced at Bomboré and sold into the market.
- Other revenue: immaterial. Public filings and company disclosures point overwhelmingly to operating revenue being generated by gold production rather than a diversified mix of metals, services, or royalties.
That concentration makes Orezone easy to understand for long-term readers: if Bomboré expands successfully and gold prices remain supportive, the business can scale quickly. If mine performance weakens or country conditions deteriorate, results can also change quickly. Over the last several years, the company has moved from a development-stage profile with little to no revenue into a producing miner with rising sales, stronger operating income, and positive net earnings, which is a meaningful transition for a company of its size.
The financial flow also shows a clear business shift. Orezone went from no meaningful revenue in 2021 to more than $375 million in annual revenue by 2025, while operating income and net income turned solidly positive. Another encouraging point is that interest expense has not risen with revenue; it has actually eased in recent periods, suggesting that growth has not been entirely consumed by heavier financing costs.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $1.49B | |
| Beta ⓘ | 1.22 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.39 | 16.90 |
| P/B Ratio ⓘ | 2.30 | 1.65 |
| FCF Yield ⓘ | 14.15% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | 39.95% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 187.40% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 40.66% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 33.78% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -16.48% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 36.37% | 9.26% |
| ROA (Latest) ⓘ | 12.01% | 4.91% |
| ROIC (5Y Median) ⓘ | 26.45% | 7.70% |
| ROA (5Y Median) ⓘ | 11.64% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.68 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | 16.07 | 12.34 |
| Operating Margin (Latest) ⓘ | 38.88% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 31.76% | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | 17.93% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $210.87M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +202.94% | +68.89% |
| 12M Return (excl. last month) ⓘ | +131.03% | +30.21% |
| 6M Return ⓘ | +9.89% | -4.16% |
| Price vs. 200-Day MA ⓘ | +12.31% | -1.27% |
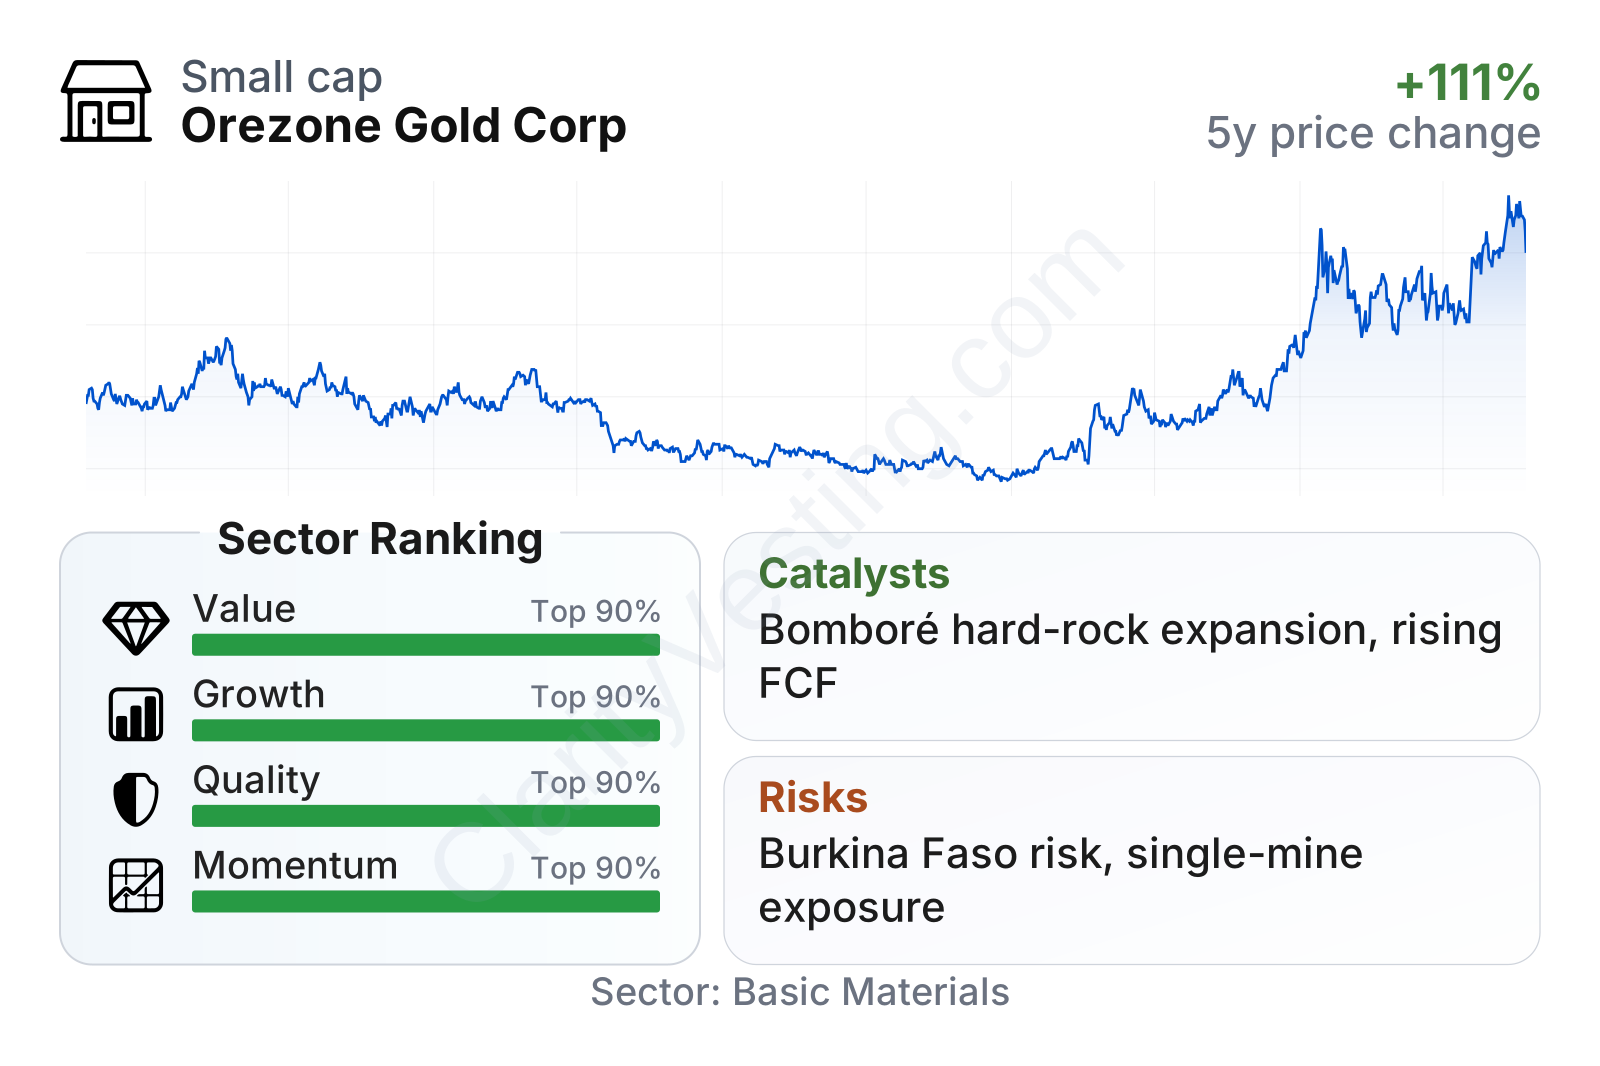
Orezone is now a mid-sized gold producer by market value, with share-price volatility above the broader market, which is common for single-asset mining companies. On valuation, the shares screen at a lower earnings multiple than the sector median, while free-cash-flow yield and EBIT relative to enterprise value look notably stronger than many peers. At the same time, the price-to-book ratio sits above the sector median, which suggests the market is assigning a premium to the asset base and growth outlook rather than valuing the company as a distressed or overlooked miner.
The broader quality profile appears strong. Profitability metrics such as return on invested capital, return on assets, and operating margin rank well above typical sector levels. Balance-sheet pressure also looks manageable, with leverage measures and interest coverage indicating that debt is present but not overwhelming relative to operating earnings. Growth and momentum factors are also near the top of the sector, reflecting both the mine ramp-up and the sharp stock-price recovery from 2025 into 2026.
Growth
Gold remains a structurally important commodity, supported by central bank buying, jewelry demand, investment demand, and its role as a perceived store of value during periods of inflation, currency weakness, or geopolitical stress. That does not make the sector predictable, but it does mean a successful low-cost producer can remain relevant for a long time if its reserve base and expansion pipeline are credible.
Orezone’s growth case is mainly tied to increasing output from Bomboré and extending the mine’s economic life through staged development. The company has highlighted hard-rock expansion potential in addition to the existing oxide operation, which matters because it can lift throughput, production, and asset longevity if executed well. For a miner of this size, moving from a single operating phase to a broader multi-stage mine plan can significantly change earnings power.
Revenue growth has been unusually strong, with several recent periods showing sharp year-over-year gains. There was some unevenness in 2024, which is normal in mining because production timing, grades, and gold prices can move quarter to quarter. The bigger picture is still clear: Orezone is operating from a much larger revenue base than it had only a few years ago, and the latest annual and trailing figures point to continued expansion rather than stagnation.
Cash generation has also improved in an important way. Free cash flow was deeply negative during the buildout phase, then turned positive and has continued climbing. That transition is a major milestone because it suggests the mine is no longer just consuming capital to grow; it is increasingly producing cash that can support debt reduction, expansion spending, and financial flexibility.
A notable catalyst is the company’s effort to expand Bomboré through hard-rock development and broader processing capacity. If completed on time and near budget, that could support a step-up in production beyond the current oxide-based profile. Another favorable backdrop is the gold price environment: because Orezone is almost entirely exposed to gold, higher realized prices can flow through earnings and cash flow quickly when operating performance is stable.
Recent company updates have also centered on construction and financing progress for the next phase of Bomboré. For long-term analysis, that matters more than short-term headline noise because the company’s medium-term value creation depends heavily on whether it can convert a successful first mine phase into a larger, longer-duration operating platform.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


