Stock Analysis · OceanaGold Inc (OGPIF)
Overview
OceanaGold Inc is a mid-sized gold mining company. It explores for, develops, and operates mines that produce gold, with copper and silver as smaller by-products at some sites. The company’s producing assets are located in the Philippines, New Zealand, and the United States, which gives it a more diversified footprint than many single-country miners. In simple terms, its business model is straightforward: extract metal from its mines, sell it into global commodity markets, and try to keep production costs below the selling price.
The main source of revenue is gold sales. Based on the company’s recent operating profile and mine disclosures, gold appears to account for the large majority of revenue, while copper and silver make up a much smaller share.
- Gold: approximately 85% to 90% of revenue. This is the core product across the company’s operating mines and the main driver of earnings and cash flow.
- Copper: approximately 8% to 12% of revenue. This is mainly tied to the Didipio operation in the Philippines, where copper is produced alongside gold.
- Silver and other minor revenue: approximately 1% to 3% of revenue. These are by-products or smaller sales categories that do not meaningfully change the overall investment case.
What stands out operationally is that OceanaGold is not just a pure exploration name depending on future discoveries. It already has producing assets and cash generation, while still keeping some upside from mine life extensions, resource conversion, and project development. The recent financial flow also points to a stronger earnings profile: revenue and operating income improved meaningfully by 2025, while interest expense fell sharply, suggesting cleaner balance sheet management and better operating leverage.
The recent financial profile shows a noticeable improvement in scale and profitability over the last few years. Revenue has moved up from the low-$300 million range to around the high-$400 million range, while operating income and net income have expanded faster than sales. Another positive sign is the sharp decline in interest expense, which suggests debt pressure has eased and more operating cash is reaching shareholders and the balance sheet.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $1.59B | |
| Beta ⓘ | 1.02 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.84 | 16.90 |
| P/B Ratio ⓘ | 2.55 | 1.65 |
| FCF Yield ⓘ | 13.37% | 5.76% |
| Dividend Yield ⓘ | 9.79% | 2.13% |
| EBIT / EV ⓘ | 15.46% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 31.90% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 8.73% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -5.37% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -1.71% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 11.06% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 624.71% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 27.55% | 9.26% |
| ROA (Latest) ⓘ | 16.72% | 4.91% |
| ROIC (5Y Median) ⓘ | N/A | 7.70% |
| ROA (5Y Median) ⓘ | N/A | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | 15.70 | 12.34 |
| Operating Margin (Latest) ⓘ | 34.80% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 23.61% | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | 22.22% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $212.80M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +68.89% |
| 12M Return (excl. last month) ⓘ | N/A | +30.21% |
| 6M Return ⓘ | -4.16% | -4.16% |
| Price vs. 200-Day MA ⓘ | +5.56% | -1.27% |
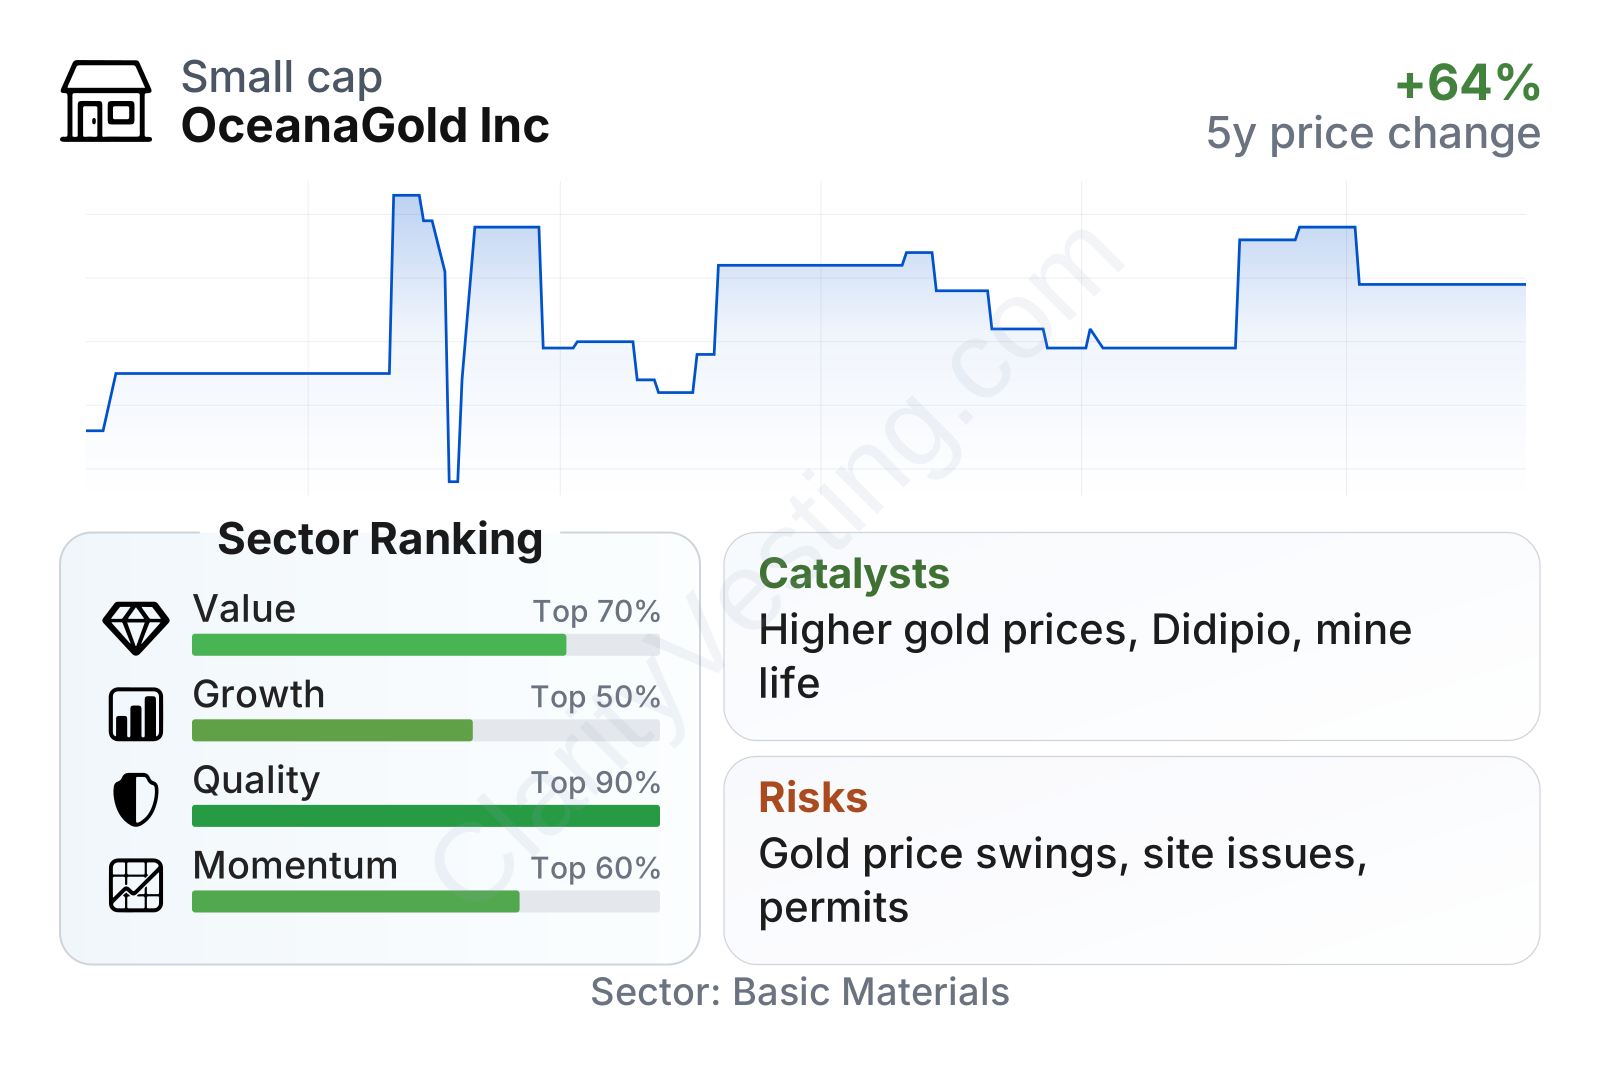
The market currently values OceanaGold like a profitable miner rather than a distressed turnaround. Its earnings multiple sits below the sector median, while cash flow-based measures look stronger than many peers. Free cash flow yield is notably high for the industry, and profitability metrics such as operating margin, return on assets, and return on invested capital are well above typical gold-sector levels. Growth has also been solid, especially on revenue and free cash flow over recent years.
The share price has also shown improving momentum over the last several months, outperforming the broader sector on a shorter time horizon. At the same time, the stock does not look priced like a high-growth premium name. That combination — stronger profitability, better cash generation, and only moderate valuation — is one of the more interesting elements in the current setup. One point to watch is book value growth, which has been weaker than the sector, indicating that asset base expansion has not matched the pace seen elsewhere.
Growth
Gold mining is not a high-growth industry in the same way as software or semiconductors, but it can still benefit from powerful long-term drivers. Demand for gold is supported by jewelry, central bank buying, investment demand, and its role as a store of value during periods of inflation, geopolitical tension, or financial uncertainty. That means the sector can become very attractive when metal prices are strong, even if production volumes grow only moderately.
OceanaGold’s strategy makes sense for that environment. The company is focused on getting more value from existing mines, extending mine life, and improving operating performance rather than chasing large, expensive acquisitions. That tends to be a more disciplined path in mining, where overpaying for projects has often destroyed value. Its portfolio mix also helps: Didipio adds copper exposure, which can support revenue diversification, while the United States and New Zealand assets provide lower political risk than many emerging-market mining regions.
A meaningful catalyst is the company’s ability to convert higher gold prices into cash flow. Mining has operating leverage: once a mine is running, a higher gold price can lift margins significantly if costs stay under control. The company’s recent margins and free cash flow suggest this effect is already visible. Another potential catalyst is reserve replacement and resource growth around existing operations, because extending mine life can increase the value of infrastructure already in place without requiring a completely new mine build.
Recent company updates have also emphasized operational execution, mine development progress, and continued returns of capital, including dividends. In a sector where many companies struggle to consistently produce cash, a miner that is already generating solid free cash flow and maintaining financial flexibility can attract attention, especially if gold prices remain supportive.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


