Stock Analysis · Oil-Dri Corporation Of America (ODC)
Overview
Oil-Dri Corporation of America is a specialty materials company built around sorbent minerals, especially clay-based products. In simple terms, it mines, processes, and sells absorbent materials that are used in everyday products such as cat litter, industrial cleanup products, fluids purification, agricultural carriers, and ingredients for animal health and nutrition. The company has been in this niche for decades, which matters because success depends on mineral reserves, processing know-how, customer relationships, and the ability to tailor products to specific uses.
Its business is organized across several end markets rather than one single product line. Based on recent annual reporting, revenue is spread across consumer and business-to-business applications, with cat litter and related consumer absorbent products remaining the largest contributor. A practical breakdown is:
- Retail and Wholesale Products Group: about 47% of revenue — mainly cat litter, animal health products sold through retail channels, and other consumer absorbent products.
- Business to Business Products Group: about 43% of revenue — industrial and automotive absorbents, agricultural and horticultural carriers, animal health ingredients, fluids purification products, and sports field conditioners.
- Packaging / other support activities: about 10% of revenue — flexible packaging and related operations that support internal and external customers.
That mix is useful for long-term analysis because it gives Oil-Dri some diversification. Consumer pet products can provide steadier demand, while industrial, agricultural, and purification uses can add growth when those markets are healthy. Recent years also show a business that has not only increased sales, but improved how much profit it keeps from those sales.
The financial flow over the last few years points to a meaningful operational improvement: revenue climbed from roughly $349 million in fiscal 2022 to about $494 million in fiscal 2026, while net income expanded much faster. That suggests the business did more than just sell more volume; it also benefited from stronger pricing, better mix, or improved cost control.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $1.27B | |
| Beta ⓘ | 0.76 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 22.29 | 16.90 |
| P/B Ratio ⓘ | 4.01 | 1.65 |
| FCF Yield ⓘ | 3.40% | 5.76% |
| Dividend Yield ⓘ | 0.96% | 2.13% |
| EBIT / EV ⓘ | 5.50% | 6.30% |
| PEG ⓘ | 4.08 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3.30% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 7.55% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 47.39% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 16.80% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 12.53% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 7.36% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 14.07% | 4.91% |
| ROIC (5Y Median) ⓘ | 17.38% | 7.70% |
| ROA (5Y Median) ⓘ | 11.63% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -0.28 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.30 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.21 | 0.95 |
| Net Debt / Assets ⓘ | -4.69% | 13.69% |
| EBITDA / Interest ⓘ | 42.78 | 12.34 |
| Operating Margin (Latest) ⓘ | 14.44% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 11.76% | 11.80% |
| Debt to Equity (Latest) ⓘ | 17.99% | 40.56% |
| Profit Margin (Latest) ⓘ | 11.54% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $43.06M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +215.39% | +68.89% |
| 12M Return (excl. last month) ⓘ | +33.14% | +30.21% |
| 6M Return ⓘ | +20.66% | -4.16% |
| Price vs. 200-Day MA ⓘ | +9.81% | -1.27% |
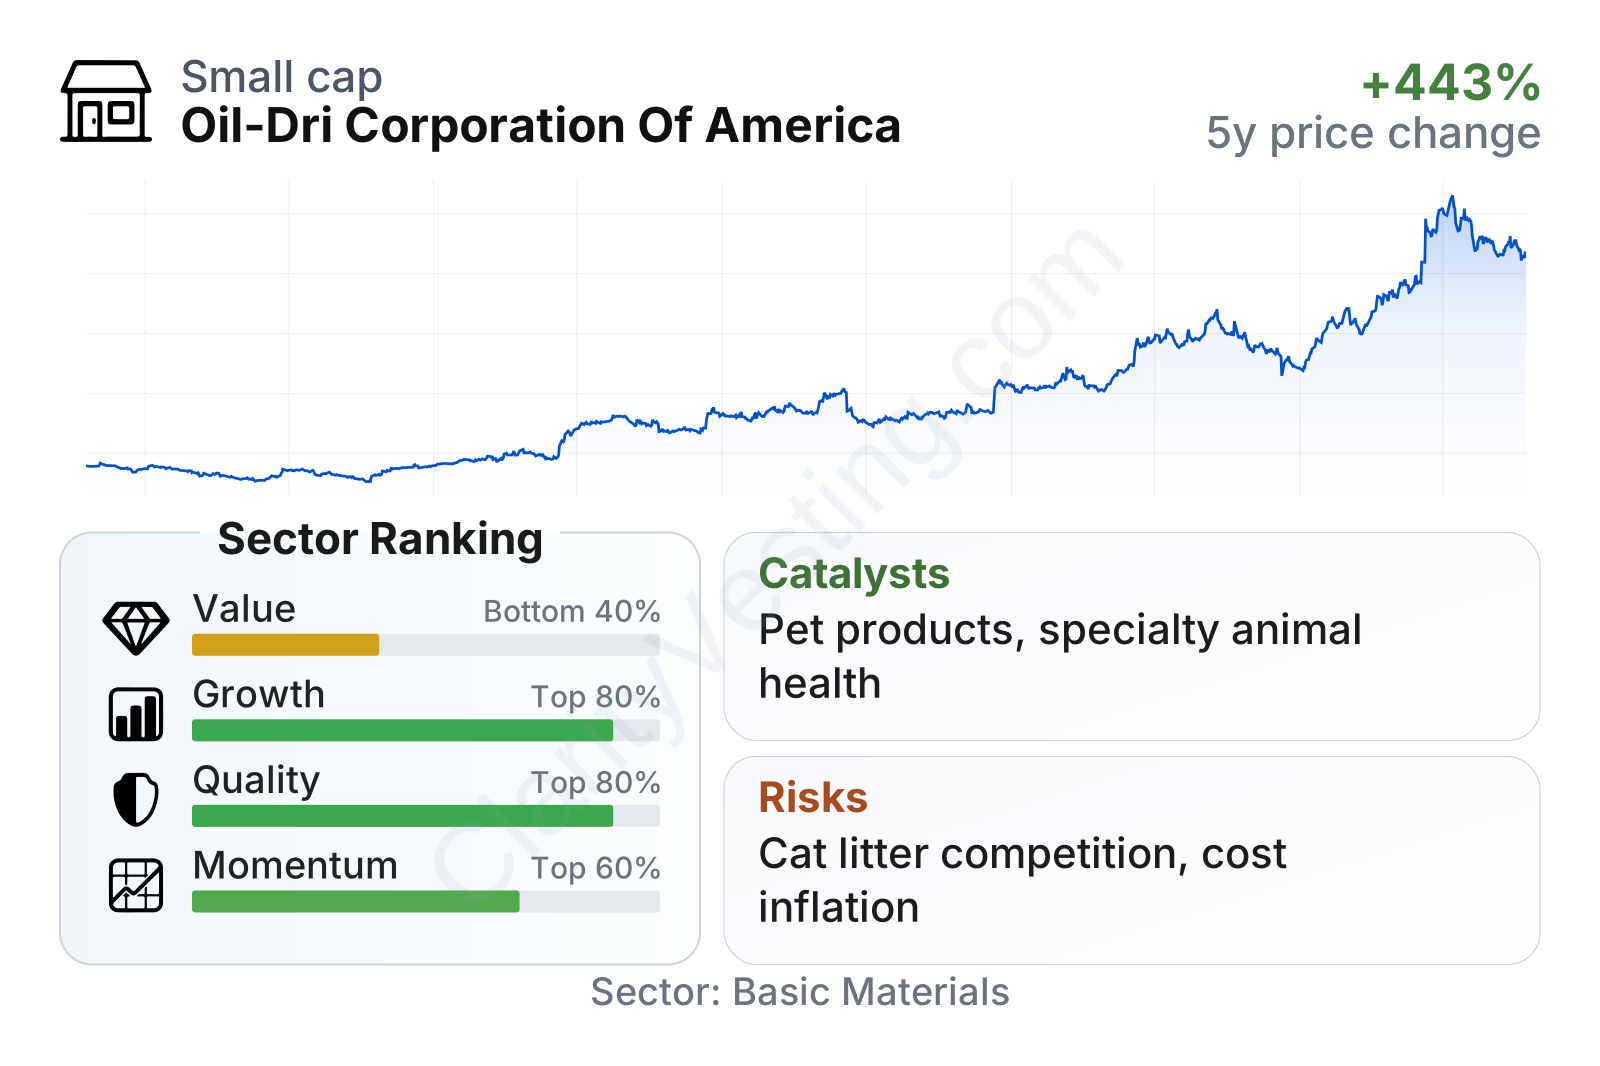
Oil-Dri is still a relatively small public company, with a market value around $1.2 billion, and its share price has been less volatile than the broader market, as shown by a beta below 1. The quality profile stands out: profitability on assets is well above the sector median, leverage is low, and interest coverage is very strong. Growth metrics are also favorable over a five-year view, especially earnings, book value per share, and revenue per share.
The weaker area is valuation. The stock trades above the sector median on earnings and far above it on book value, while free cash flow yield and EBIT-to-enterprise-value sit below many peers. In other words, the operating profile looks strong, but the market is already recognizing a good portion of that improvement.
Growth
Oil-Dri operates in markets that are mature in some areas and still expandable in others. Traditional absorbents are not a fast-changing theme like artificial intelligence or biotech, but they serve recurring needs: pet care, industrial cleanup, agricultural productivity, and purification applications. That makes the sector more about steady compounding, product mix upgrades, and market share gains than explosive top-line growth.
The company’s recent strategy appears coherent for that kind of industry. Management has focused on higher-value products, particularly in cat litter, animal health, and specialty ingredients, while continuing to improve margins. This matters because a company in a modest-growth sector can still create strong shareholder returns if it consistently moves toward better-margin categories and uses capacity efficiently.
Revenue growth has slowed from the unusually strong pace seen in 2022 and 2023, when year-over-year gains were often in the low-to-mid teens or higher, to a more normalized range in 2026. The latest annual pace is around 3%, which is not impressive on its own, but it comes after several years of expansion and against a much larger revenue base. Over five years, revenue per share growth still compares well with the sector.
Cash generation tells an even better growth-quality story. Free cash flow moved from negative territory a few years ago to roughly the mid-$40 million range on a trailing basis. That improvement gives the company more flexibility to invest in capacity, support product innovation, manage downturns, and continue its long dividend record without stretching the balance sheet.
One notable catalyst is the company’s continued push into higher-value animal health and specialty sorbent applications. These categories can carry better margins than commoditized absorbents. Another is the resilience of pet-related demand, which tends to be less cyclical than many industrial end markets. If Oil-Dri continues to combine stable pet-care demand with specialized industrial and agricultural applications, it has a reasonable path to continued earnings growth even without dramatic industry expansion.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


