Stock Analysis · NextVision Stabilized Systems Ltd (NXSNF)
Overview
NextVision Stabilized Systems Ltd is an Israeli defense technology company focused on stabilized camera systems for drones and other mobile platforms. In simple terms, it makes compact cameras that stay steady and deliver clear imagery even when the aircraft or vehicle is moving, vibrating, or operating in difficult conditions. These products are used for intelligence, surveillance, reconnaissance, security, and targeting-related missions. The company mainly sells electro-optical and infrared payloads, which are small systems that combine cameras, stabilization, and control components into one unit.
The business model is relatively straightforward: NextVision develops the systems, manufactures them, and sells them to drone makers, defense companies, and integrators. Demand is tied to the wider spread of unmanned systems in military and security applications, especially smaller drones that need lightweight, high-performance imaging equipment.
Public disclosures indicate that revenue is primarily generated from product sales rather than recurring software or service contracts. A precise split by product family is not consistently disclosed in the material available, but the revenue mix can still be described at a high level:
- Electro-optical stabilized payload systems: likely the large majority of revenue. These include day cameras, thermal cameras, and combined imaging payloads mounted on drones and other platforms.
- Spare parts, support, and related services: a much smaller share of revenue, with no clear percentage regularly broken out.
- Other custom or integration-related sales: present in some cases, but not disclosed in enough detail to assign a reliable percentage.
What stands out most is how efficiently the company converts sales into profit. Over the last several years, revenue has climbed rapidly while operating expenses remained comparatively contained, leading to unusually high margins for an industrial and defense equipment business. That pattern suggests a specialized product niche with strong pricing power and a lean operating structure, although it also raises the question of how sustainable those margins remain as the company scales.
The financial flow shows a business that has expanded very quickly since 2021. Revenue has increased several times over, and profit has risen even faster, while research and administrative spending grew much more slowly than sales. That operating leverage is a major part of the current investment case.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Security & Protection Services | |
| Market Cap ⓘ | $5.65B | |
| Beta ⓘ | 0.80 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 38.12 | 22.29 |
| P/B Ratio ⓘ | 8.12 | 1.98 |
| FCF Yield ⓘ | 2.10% | 6.26% |
| Dividend Yield ⓘ | 0.92% | 1.92% |
| EBIT / EV ⓘ | 2.52% | 4.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 137.70% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 76.24% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | 73.49% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 82.51% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 16.25% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 101.75% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 113.79% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 21.14% | 10.75% |
| ROA (Latest) ⓘ | 22.58% | 5.41% |
| ROIC (5Y Median) ⓘ | N/A | 9.37% |
| ROA (5Y Median) ⓘ | 25.73% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.39 |
| Net Debt / Assets ⓘ | N/A | 19.27% |
| EBITDA / Interest ⓘ | 171.38 | 9.58 |
| Operating Margin (Latest) ⓘ | 67.05% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 64.19% | 10.30% |
| Debt to Equity (Latest) ⓘ | N/A | 64.82% |
| Profit Margin (Latest) ⓘ | 60.55% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $118.69M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +67.77% |
| 12M Return (excl. last month) ⓘ | +71.74% | +12.05% |
| 6M Return ⓘ | -39.38% | 0.00% |
| Price vs. 200-Day MA ⓘ | -33.65% | +0.67% |
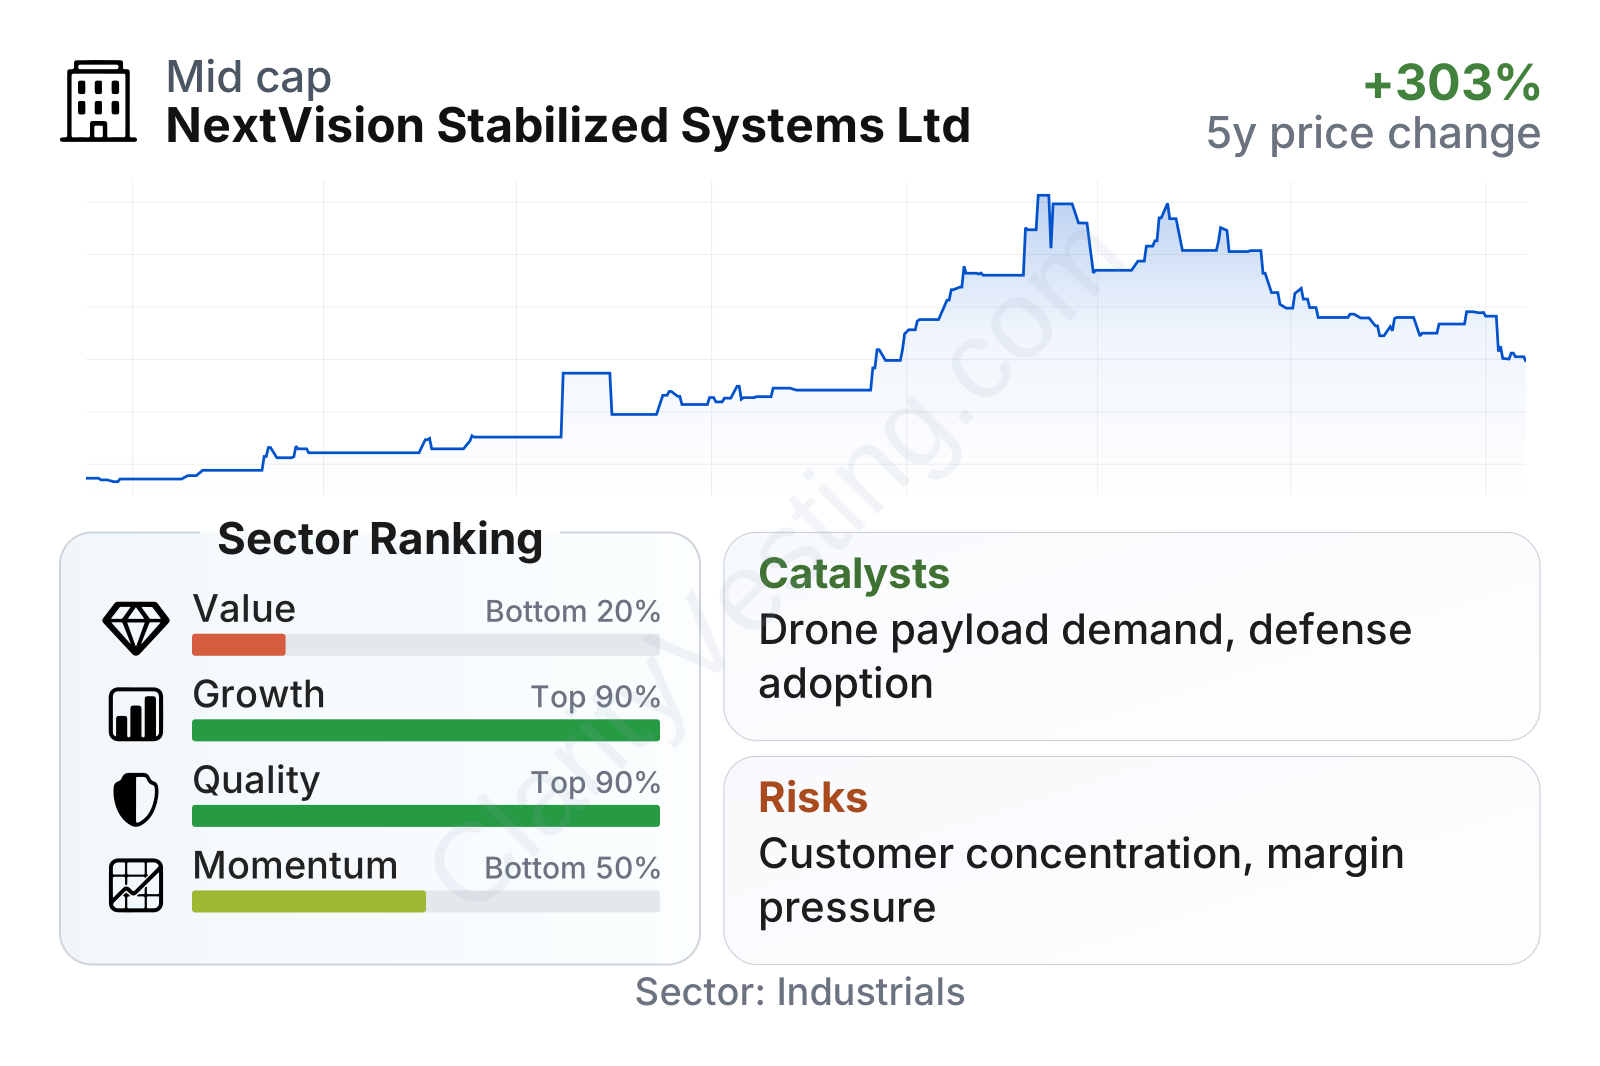
NextVision is now a mid-sized company by market value, but its fundamentals look stronger than many companies in its broader sector on growth and profitability. Revenue growth, earnings growth, return on assets, return on invested capital, and operating margin all rank near the top of the sector. The balance sheet also appears conservative, with very limited financial strain and extremely high interest coverage.
The weak point in the table is valuation. The stock trades at a clear premium to sector norms on earnings, book value, and free cash flow yield. In other words, the market is already recognizing the company’s recent surge in performance. Momentum is mixed as well: the longer-term share move has been very strong, but the shorter-term trend has cooled after a sharp run-up.
Growth
NextVision operates in a part of the defense and drone ecosystem that is benefiting from a powerful long-term trend. Military forces and security organizations around the world are spending more on unmanned aerial systems, loitering munitions, border monitoring, and portable surveillance tools. A stabilized imaging payload is a critical subsystem in many of these platforms, because drones are only as useful as their ability to see, track, and transmit clear information. That puts the company in a segment with structural demand rather than a short-lived technology fad.
The company’s strategy also looks coherent. Instead of trying to build full drones or large weapon systems, it focuses on one high-value component where size, weight, image quality, and stabilization matter. That specialization can be attractive in defense supply chains because many drone makers prefer to source key subsystems from companies with proven expertise rather than develop every part internally.
The recent growth profile has been exceptional, not merely good. Year-over-year revenue growth accelerated from already high levels into triple digits by mid-2026, far above typical industrial sector performance. That kind of acceleration usually reflects both strong end-market demand and successful execution in production and sales.
Cash generation has also moved higher, which matters because rapid revenue growth can sometimes hide weak cash conversion. Here, free cash flow has trended upward over time, suggesting that a meaningful share of accounting profit is turning into real cash. Even so, the free cash flow yield remains modest at the current market value, which means the market is placing a high price on future expansion.
Recent company communications and filings have pointed to continued order activity and broad international demand for drone imaging solutions. The most important catalyst is not one single contract headline, but the broader normalization of drones as standard military equipment. If that trend continues, NextVision could keep benefiting from repeat orders, new customer programs, and a larger installed base across multiple platforms.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


