Stock Analysis · New Oriental Education & Technology Group Inc (NWOEF)
Overview
New Oriental Education & Technology Group is a China-based education company that has rebuilt its business after the country’s major tutoring regulation changes in 2021. Today, the group operates a broad education platform centered on test preparation, overseas study consulting, adult and language training, non-academic learning programs, and educational services delivered both in learning centers and online. It also owns East Buy, an e-commerce livestreaming business that grew out of its online education capabilities and became an important second engine for the group.
The company’s revenue base is now more diversified than it was before the regulatory reset. Based on the latest annual filing and company reporting, the main sources of revenue are approximately:
- Educational services and test preparation: about 55% to 65% of revenue. This includes overseas test prep, domestic test prep, adult and university student courses, language training, and broader educational programs.
- East Buy e-commerce and private-label products: about 30% to 40% of revenue. This activity mainly includes livestreaming sales, online merchandise, and related supply chain operations.
- Overseas study consulting and other services: about 5% to 10% of revenue. This includes application consulting, educational content, and smaller ancillary activities.
That mix matters because it shows New Oriental is no longer just a traditional tutoring operator. It is increasingly a hybrid platform combining education services with a consumer-facing digital retail operation. Over the last few years, revenue, gross profit, and operating income have all recovered strongly, and the business has moved from a large loss in fiscal 2022 to steadily rising profitability by fiscal 2026.
One notable feature of the business model is its financial flexibility. Interest expense is almost negligible, which suggests the company is operating with a very light debt burden. At the same time, selling and administrative costs remain substantial, so future efficiency will depend on how well New Oriental scales both its learning network and East Buy without letting overhead rise too quickly.
The long-term picture here is a clear turnaround: revenue has climbed materially since fiscal 2023, while net income and operating income have improved each year. The business is larger, more profitable, and less financially constrained than it was during the post-regulation reset.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Education & Training Services | |
| Market Cap ⓘ | $7.01B | |
| Beta ⓘ | 0.18 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 15.07 | 17.88 |
| P/B Ratio ⓘ | 1.92 | 1.29 |
| FCF Yield ⓘ | 11.13% | 12.39% |
| Dividend Yield ⓘ | 26.55% | 2.85% |
| EBIT / EV ⓘ | 16.98% | 6.43% |
| PEG ⓘ | 0.78 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 23.00% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 18.88% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | 57.33% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 1.31% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 2.59% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.33% | 12.34% |
| ROA (Latest) ⓘ | 5.66% | 6.30% |
| ROIC (5Y Median) ⓘ | 11.21% | 10.49% |
| ROA (5Y Median) ⓘ | 4.45% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.38 |
| Net Debt / Assets ⓘ | N/A | 21.51% |
| EBITDA / Interest ⓘ | N/A | 9.46 |
| Operating Margin (Latest) ⓘ | 12.90% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 11.20% | 9.53% |
| Debt to Equity (Latest) ⓘ | N/A | 72.35% |
| Profit Margin (Latest) ⓘ | 8.39% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $780.17M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +20.92% |
| 12M Return (excl. last month) ⓘ | -0.26% | +2.13% |
| 6M Return ⓘ | -9.96% | +1.26% |
| Price vs. 200-Day MA ⓘ | -5.89% | +1.39% |
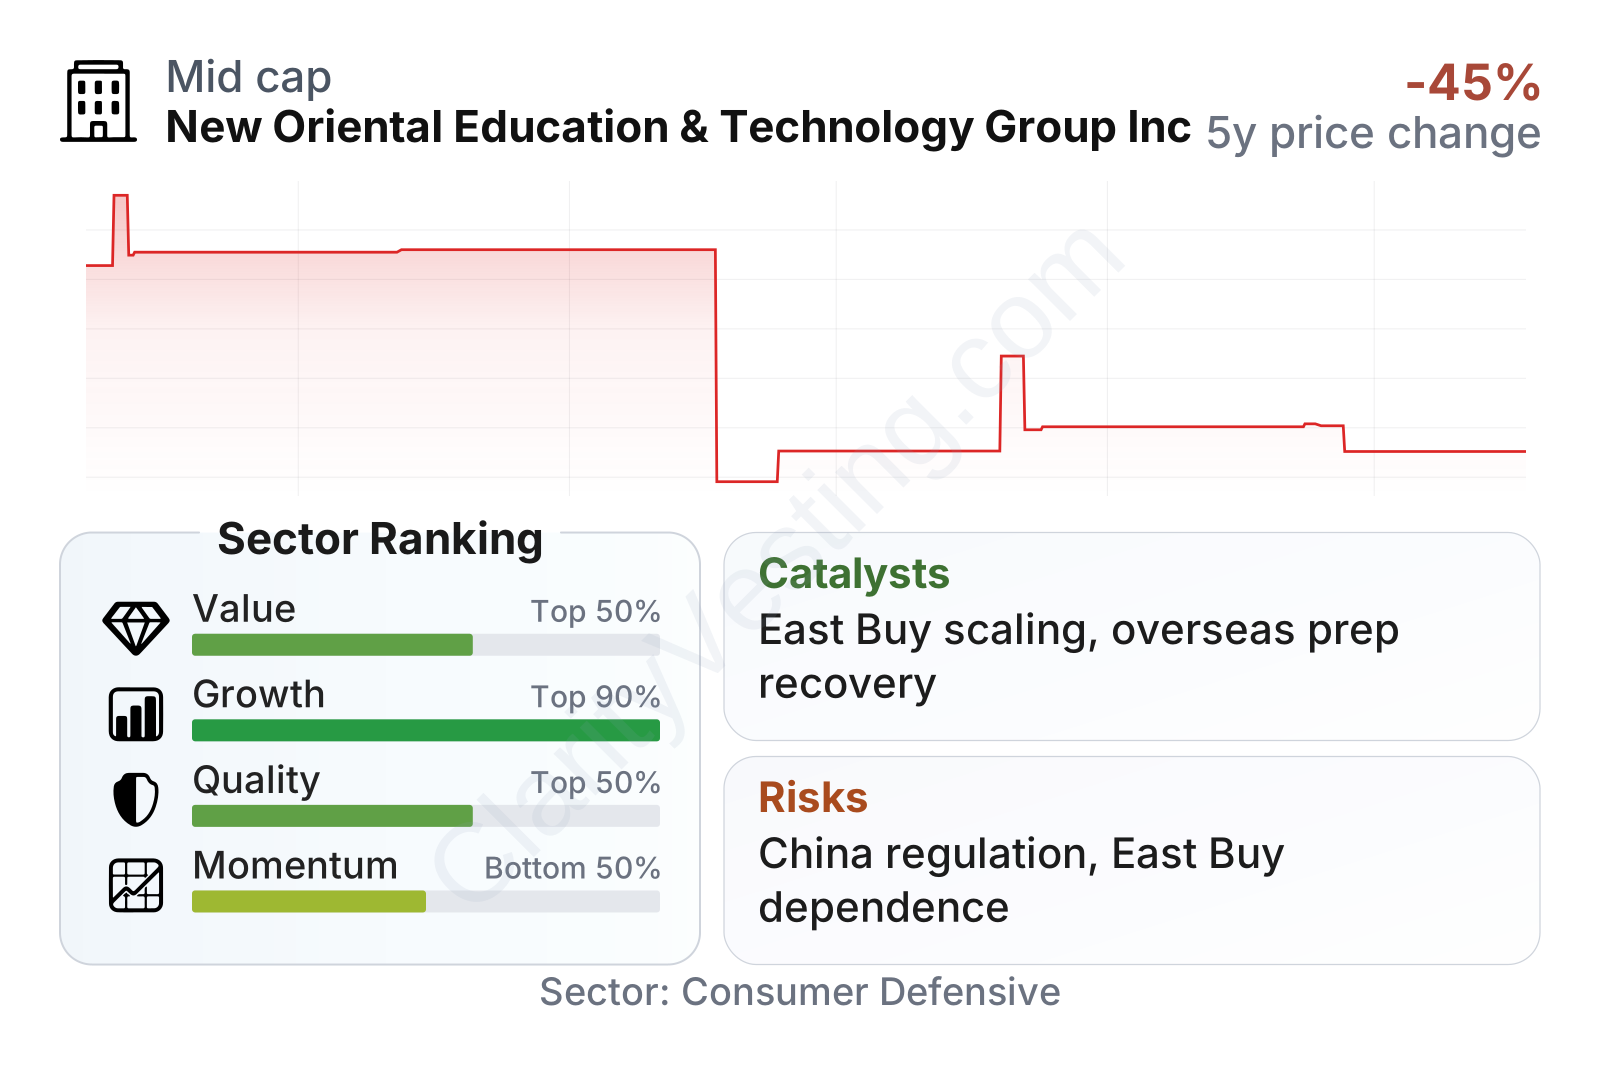
New Oriental stands out for strong growth and solid operating quality, while recent market performance has been weaker than much of its sector. Growth metrics rank near the top of the peer group, margins are above sector norms, and the earnings multiple sits below the sector median. That combination suggests the market is recognizing the recovery, but not valuing it like a high-premium growth company.
The company is mid-sized rather than dominant at the global level, but it is still one of the most recognizable private education brands in China. Another useful point for long-term analysis is volatility: the stock’s beta is very low, which indicates trading has historically moved less sharply than the broader market. Even so, the share price has been under pressure since 2025, so the stock’s path has not mirrored the underlying operating improvement.
Growth
New Oriental operates in parts of the education market that still have structural demand. Families and students in China continue to spend on language learning, test preparation, study abroad services, and skills development that can improve educational or career outcomes. Those categories are more durable than purely speculative consumer trends because they are tied to exams, admissions, and employability.
The company’s strategy also makes sense in the context of the new regulatory environment. Instead of relying on the old K-9 after-school tutoring model, it has shifted toward areas that remain permitted and commercially attractive: adult education, overseas exam preparation, educational tourism, non-academic enrichment, and digital commerce through East Buy. That repositioning has reduced dependence on one single business line and created multiple paths for expansion.
Revenue growth has accelerated over the most recent periods, moving from high single digits to above 20% year over year by the latest fiscal year-end. That is far ahead of the sector median and suggests demand has remained healthy across the rebuilt portfolio. Over a five-year view, revenue per share growth has also been strong, showing that the rebound is not just a short-term base effect.
Cash generation adds credibility to the growth profile. Free cash flow has stayed comfortably positive, in the hundreds of millions of dollars, even while the company continues investing in operations and brand development. This is important because it shows the expansion is not being funded by heavy leverage or persistent cash burn.
Recent company communications have also highlighted ongoing network expansion, product development, and efforts to deepen the East Buy ecosystem. A practical catalyst is the continued normalization of student mobility and overseas exam demand, which supports test prep and consulting. Another is East Buy’s ability to extend from livestream traffic into repeat purchases, self-operated products, and broader consumer reach. If those two engines keep advancing together, New Oriental could keep growing even if any one segment slows.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


