Stock Analysis · Novavax Inc (NVAX)
Overview
Novavax is a biotechnology company focused on vaccines. Its business is centered on discovering, developing, and commercializing preventive vaccines, with the company best known for its COVID-19 vaccine, marketed as Nuvaxovid or NVX-CoV2373 in many regions. Novavax also has a combination COVID-19 and influenza vaccine candidate in development and continues to work on its stand-alone influenza program. For a long-term view, the most important point is that Novavax is no longer just a pandemic-era vaccine supplier; it is trying to reposition itself as a more focused vaccine platform company that can generate recurring value from partnerships, commercial sales, and future product launches.
Revenue has become more concentrated and simpler to understand than during the peak pandemic years. Based on recent annual disclosures and company updates, the main sources of revenue are approximately:
- Product sales and related COVID-19 vaccine commercial revenue: about 55% to 65% of recent annual revenue. This includes sales of the company’s COVID-19 vaccine in markets where Novavax or its partners commercialize doses.
- Licensing, royalties, and partnership revenue: about 30% to 40%. This has become increasingly important after the Sanofi partnership, which includes upfront payments, milestone opportunities, and royalties tied to commercialized products.
- Grant, contract, and other revenue: generally 0% to 10%, depending on the period. This may include work under government or collaborative arrangements and smaller miscellaneous items.
The business mix has shifted sharply over the last few years. Pandemic vaccine demand created very large but volatile sales, then revenue dropped as global booster demand normalized. More recently, the company has been leaning on partnership economics and a leaner operating model to stabilize the business. Another notable change is cost discipline: research and administrative spending have come down meaningfully from the peak years, which helped the company move from very large losses toward much narrower losses and, at one point, a return to annual profitability.
The long-term pattern is clear: revenue has been highly uneven, but expenses have fallen much faster than they did during the heavy development and pandemic scale-up phase. That cost reset is one of the main reasons the business now looks materially different from the Novavax of 2021 to 2023.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $1.85B | |
| Beta ⓘ | 2.44 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | N/A | 2.97 |
| FCF Yield ⓘ | -2.36% | 3.11% |
| Dividend Yield ⓘ | N/A | 2.04% |
| EBIT / EV ⓘ | -16.95% | 0.57% |
| PEG ⓘ | 1.32 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -76.30% | 7.35% |
| RPS Growth (5Y CAGR) ⓘ | -19.44% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -56.22% | -18.43% |
| BVPS Growth (5Y CAGR) ⓘ | -37.14% | 3.94% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.61% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.74% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -150.48% | 3.34% |
| ROA (Latest) ⓘ | -23.20% | 2.95% |
| ROIC (5Y Median) ⓘ | N/A | 4.60% |
| ROA (5Y Median) ⓘ | -26.88% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.02 |
| Net Debt / Assets ⓘ | 10.90% | 5.85% |
| EBITDA / Interest ⓘ | N/A | 9.60 |
| Operating Margin (Latest) ⓘ | -53.99% | 9.19% |
| Operating Margin (5Y Median) ⓘ | -39.64% | 7.53% |
| Debt to Equity (Latest) ⓘ | -155.00% | 29.44% |
| Profit Margin (Latest) ⓘ | -59.87% | 3.52% |
| Free Cash Flow (Latest) ⓘ | -$43.59M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +53.34% | +34.80% |
| 12M Return (excl. last month) ⓘ | +31.82% | +19.33% |
| 6M Return ⓘ | +30.76% | +7.18% |
| Price vs. 200-Day MA ⓘ | +22.53% | +3.20% |
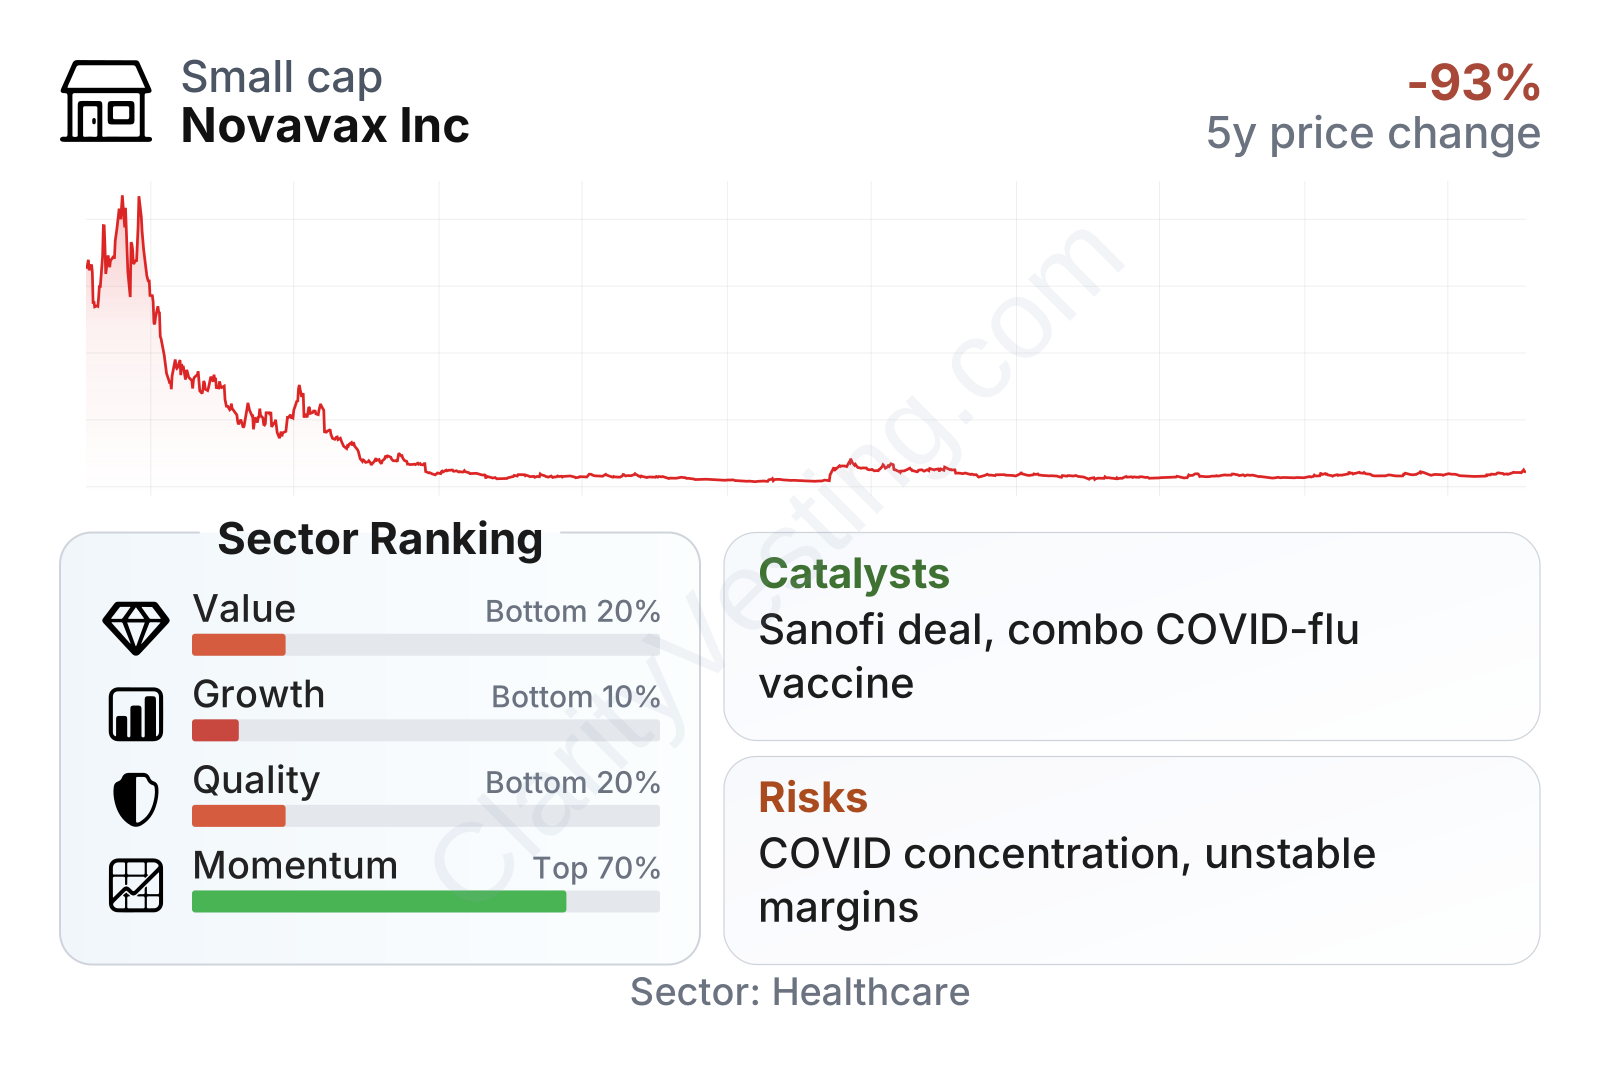
Novavax remains a small-cap biotechnology company with very high share-price volatility, reflected in a beta well above the market average. On broad factor rankings, it sits in the lower tier of the healthcare sector for value, growth, and quality, while recent price momentum has been somewhat better than the sector median. In plain English, the market has recently treated the stock more favorably than its fundamentals alone would suggest, likely because investors are reacting to restructuring progress, partnership economics, and pipeline optionality rather than steady operating performance.
The table also shows an uneven profile. Growth metrics are weak because recent year-over-year revenue has contracted sharply, and quality measures remain pressured by negative returns on capital and negative margins. At the same time, cash burn has improved a lot from prior periods, which matters more for Novavax than traditional valuation screens. This is a company in transition, so the headline ratios need to be read alongside the turnaround context.
Growth
Novavax operates in a sector that still has long-term relevance. Vaccines remain one of the more durable areas of biopharma because respiratory viruses continue to circulate, public health systems continue to purchase immunizations, and manufacturers can build repeat demand through seasonal booster campaigns. However, the COVID-19 vaccine market is much smaller and more competitive than it was during the emergency phase of the pandemic. That means growth is less about broad market expansion and more about whether Novavax can secure a defendable niche with differentiated products and strong commercial partners.
The current strategy is more coherent than it was a few years ago. Management has reduced operating expenses, narrowed the company’s focus, and used partnerships to extend its commercial reach without carrying the full burden of global commercialization alone. The Sanofi agreement is especially important because it provides immediate economic support and external validation from one of the world’s largest vaccine companies. It also creates a path for Novavax’s technology to be used in future combination products, especially the combined COVID-19 and flu vaccine candidate, which could be more attractive in a seasonal vaccination market than a stand-alone COVID shot.
Revenue trends remain volatile and difficult to read quarter by quarter. The recent year-over-year declines are severe, with revenue down by roughly three-quarters in the latest comparison period. That looks weak on the surface, but Novavax’s revenue base is distorted by milestone timing, seasonal vaccine sales, and the post-pandemic reset. For this company, a single partnership payment or product update can have an outsized impact on reported growth.
Cash generation is still negative, but the trend has improved substantially from the deepest burn periods. Trailing free cash flow remains below zero, yet the losses are much smaller than they were two to three years ago. That improvement suggests the restructuring has had real effect, even if the business has not yet reached a stable self-funding position.
The most meaningful catalyst is the respiratory vaccine pipeline. Novavax’s protein-based approach gives it a differentiated technological profile compared with the mRNA leaders. If the combined COVID-flu program continues to progress and produces competitive results, it could open a more practical commercial opportunity than relying only on a shrinking stand-alone COVID market. In addition, updated regulatory approvals, expanded market access, and partner-led commercialization could improve revenue visibility more than recent figures imply.
Recent company updates have also pointed to continued work on regulatory filings and partnership execution. For a company of this size, those events matter because they can reshape both the income statement and the balance-sheet outlook relatively quickly.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


