Stock Analysis · Nutex Health Inc (NUTX)
Overview
Nutex Health Inc is a healthcare company focused on two main activities: operating hospitals and emergency facilities, and supporting independent physician groups through a management and technology platform. In simple terms, it combines physical care sites with an administrative network that helps doctors manage billing, contracting, staffing, and other back-office functions.
The company’s business is generally organized into two reporting segments. Based on recent annual filings, revenue is primarily generated from patient care delivered through its hospitals and outpatient facilities, with a smaller but still meaningful contribution from its population health and physician support operations.
- Hospital Division: approximately 85% to 90% of revenue in recent periods. This includes facility fees and patient service revenue from micro-hospitals, specialty hospitals, emergency rooms, and related healthcare operations.
- Population Health Management Division: approximately 10% to 15% of revenue in recent periods. This segment includes management services for affiliated physician groups, risk-based care support, contracting, and other services tied to value-based care arrangements.
That mix matters because the hospital side gives Nutex direct exposure to patient volumes and reimbursement trends, while the population health side can add a more asset-light source of fees if physician participation expands. Over the last few years, the company’s revenue base has also become much larger, but results have been uneven, with a period of sharp losses followed by a meaningful profitability recovery.
The business model is somewhat unusual within public healthcare companies. Nutex is not one of the very large national hospital chains, and it is not purely a software or insurance platform either. Its niche is a hybrid approach centered on smaller acute-care facilities and physician alignment.
The longer-term financial picture shows a dramatic rebound after a weak 2022-2023 period. Revenue and operating income improved sharply in 2024 and 2025, and profit generation has recovered to levels far above many companies in the same healthcare peer group. That recovery is central to understanding why the stock has attracted attention.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Care Facilities | |
| Market Cap ⓘ | $1.32B | |
| Beta ⓘ | 2.00 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 7.90 | 24.79 |
| P/B Ratio ⓘ | 5.01 | 3.08 |
| FCF Yield ⓘ | 20.83% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 42.64% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -13.60% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 11.48% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | 4.69% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | -22.49% | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | 15.82% | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | -25.93% | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 73.75% | 3.24% |
| ROA (Latest) ⓘ | 18.65% | 3.01% |
| ROIC (5Y Median) ⓘ | 24.53% | 4.60% |
| ROA (5Y Median) ⓘ | 9.00% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | 0.39 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.81 | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | 0.37 | 1.00 |
| Net Debt / Assets ⓘ | 14.73% | 5.45% |
| EBITDA / Interest ⓘ | 19.43 | 9.64 |
| Operating Margin (Latest) ⓘ | 42.91% | 9.27% |
| Operating Margin (5Y Median) ⓘ | 27.02% | 7.38% |
| Debt to Equity (Latest) ⓘ | 88.09% | 28.58% |
| Profit Margin (Latest) ⓘ | 21.25% | 3.59% |
| Free Cash Flow (Latest) ⓘ | $274.17M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +537.46% | +42.80% |
| 12M Return (excl. last month) ⓘ | +125.10% | +18.50% |
| 6M Return ⓘ | +84.22% | +7.57% |
| Price vs. 200-Day MA ⓘ | +34.94% | +5.12% |
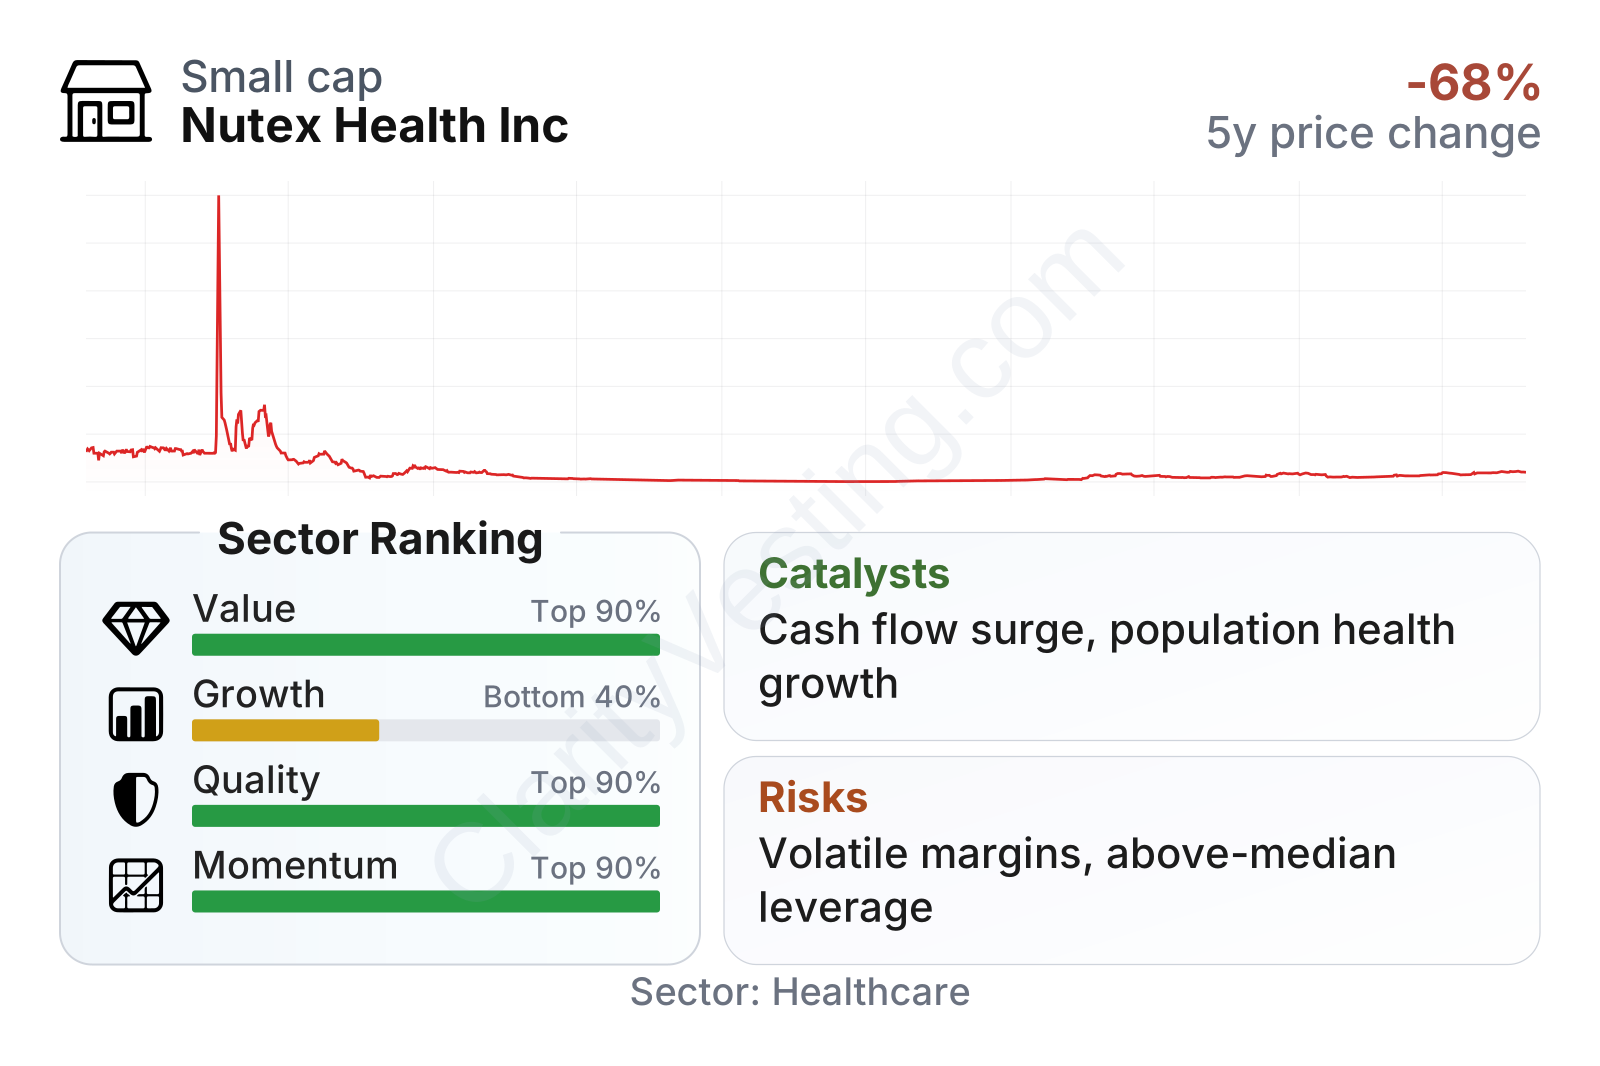
Nutex currently screens as strong on profitability, cash generation, and recent share-price momentum, while its growth profile is less convincing on the most recent year-over-year comparison. The company ranks very high versus much of the healthcare sector on quality and value measures, helped by strong returns on capital, solid interest coverage, and a low earnings multiple. At the same time, the stock’s beta above 2 suggests unusually high volatility, which fits its large price swings over the last several years.
The stock history also shows how extreme sentiment around the company has been. After a deep collapse from earlier highs, the shares rebounded very strongly from 2024 into 2026. That kind of move can happen when a small or mid-sized company shifts from losses to profits, but it also means the market’s view can change very quickly if operating results disappoint.
Growth
Healthcare is generally a growing sector over the long run because of aging demographics, chronic disease management needs, and continued demand for accessible care outside traditional large hospital campuses. Nutex operates in parts of the market that can benefit from those trends, especially community-based emergency and hospital services and physician-oriented population health infrastructure.
The company’s strategy has a clear logic. Smaller local facilities can serve patients looking for easier access than a large hospital system may provide, while the physician-services platform gives Nutex a way to deepen relationships with clinicians and participate in value-based care arrangements. If executed well, that combination can support both patient service revenue and recurring management-related income.
Growth, however, has not been smooth. Over the past few years, quarterly and annual revenue growth has been highly volatile. There was a major acceleration through 2024 and much of 2025, followed by a much slower pattern more recently, including a year-over-year decline in the latest period shown. That makes the company look less like a steady compounder and more like a business still normalizing after a turbulent phase.
One of the most encouraging developments is cash generation. Free cash flow moved from weak or negative levels into a very strong positive figure over the trailing twelve months. For a healthcare operator, that is important because accounting profits can sometimes look healthier than actual cash production. In Nutex’s case, the recent improvement appears substantial enough to strengthen the balance sheet and support operational flexibility.
A major catalyst for the long-term outlook is whether the company can keep converting its larger revenue base into durable earnings and cash flow. Another is expansion of the population health business, which could improve business mix if higher-margin management and risk-service revenue grows faster than the facility side. Continued maturation of recently developed facilities and better utilization at existing sites could also support future operating leverage.
Recent company communications have emphasized continued profitability, strong cash flow, and operating progress. For a business that had gone through a difficult earnings period, that shift is significant because it changes the debate from basic survival and restructuring toward sustainability of margins and expansion potential.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


