Stock Analysis · Netskope Inc (NTSK)
Overview
Netskope is a cloud security company. Its software helps businesses protect employees, data, and applications as work moves across the internet, cloud platforms, and private networks. In simple terms, Netskope sits between users and the digital tools they use, checking traffic, enforcing security rules, and trying to stop data leaks, malware, and unauthorized access.
The company’s main platform is built around Security Service Edge, or SSE, a category that combines secure web access, cloud application protection, zero trust network access, and data security tools into one service. Netskope has been positioning itself as a vendor that can replace several older point products with a more unified platform.
Based on company filings, Netskope generates most of its revenue from subscriptions, with a much smaller contribution from professional services and other support-related work.
- Subscription revenue: about 94% of fiscal 2026 revenue — recurring fees for access to the Netskope platform, including cloud security, zero trust access, data protection, and related platform capabilities.
- Professional services and other revenue: about 6% of fiscal 2026 revenue — implementation, consulting, onboarding, training, and related customer support activity tied to deployments.
This mix matters for long-term analysis because subscription-heavy software businesses usually benefit from recurring revenue, better visibility, and stronger customer retention than product businesses that rely on one-time sales.
The business model shows a positive top-line pattern: revenue and gross profit have risen quickly over the last three fiscal years. At the same time, operating costs expanded even faster in the latest year, especially research and development and selling expenses, which explains why growth has not yet translated into accounting profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Software - Infrastructure | |
| Market Cap ⓘ | $8.43B | |
| Beta ⓘ | N/A | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 30.28 |
| FCF Yield ⓘ | -0.81% | 4.19% |
| Dividend Yield ⓘ | N/A | 1.30% |
| EBIT / EV ⓘ | -10.49% | 2.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 29.20% | 15.70% |
| RPS Growth (5Y CAGR) ⓘ | 21.30% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -11.54% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 9.72% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 7.73% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -66.02% | 9.44% |
| ROIC (5Y Median) ⓘ | N/A | 8.35% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.50 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.48 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.28 |
| Net Debt / Assets ⓘ | 29.87% | 3.48% |
| EBITDA / Interest ⓘ | N/A | 12.91 |
| Operating Margin (Latest) ⓘ | -94.66% | 9.77% |
| Operating Margin (5Y Median) ⓘ | -76.88% | 8.53% |
| Debt to Equity (Latest) ⓘ | 467.03% | 34.51% |
| Profit Margin (Latest) ⓘ | -91.84% | 7.14% |
| Free Cash Flow (Latest) ⓘ | -$68.26M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +56.52% |
| 12M Return (excl. last month) ⓘ | N/A | +13.17% |
| 6M Return ⓘ | +133.70% | +15.38% |
| Price vs. 200-Day MA ⓘ | +65.00% | +7.53% |
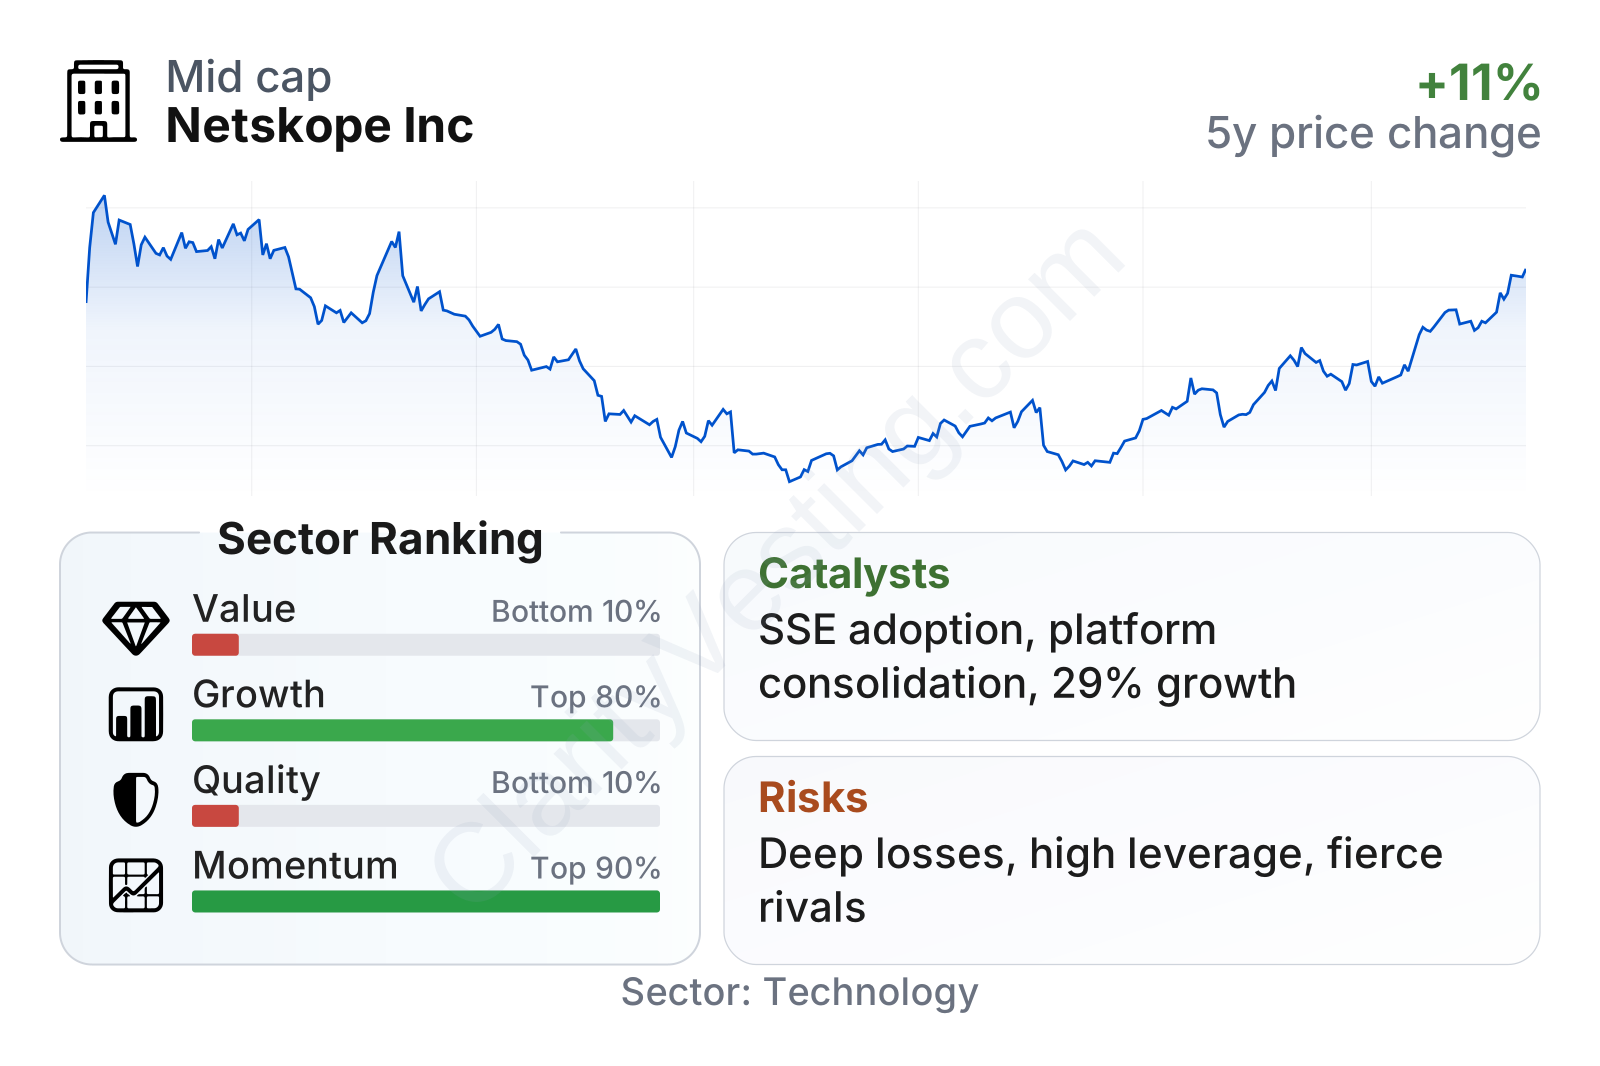
Netskope currently sits in an unusual position: strong growth and strong share-price momentum, but weak profitability and weak traditional valuation support. Revenue growth is running well above the sector median, and its five-year revenue-per-share trend is also notably stronger than many software peers. However, returns on capital, operating margin, profit margin, and free cash flow remain far below sector norms. In other words, the market is recognizing growth potential, but the underlying financial quality is still in a buildout phase rather than a mature software profile.
The stock’s recent path has also been volatile. After a sharp drop earlier in 2026, the shares rebounded strongly into September. That kind of move often reflects changing expectations around growth, market sentiment, or strategic developments, but it also signals that the stock can reprice quickly in both directions.
Growth
Netskope operates in a part of cybersecurity that has strong long-term tailwinds. Companies are shifting applications and data to the cloud, employees are connecting from more places and more devices, and traditional network security tools are less suited to this environment. That supports demand for secure access, zero trust architecture, and cloud-native protection, which are all central to Netskope’s offering.
The strategy makes sense in this context. Rather than focusing on a single tool, Netskope is trying to become a broader control layer for cloud use, web traffic, data movement, and private application access. This matters because customers often prefer to reduce the number of security vendors they manage. A broader platform can improve cross-selling and make deployments harder to replace once embedded.
Recent company reporting points to continued expansion. Fiscal 2026 revenue reached about $709 million, up from roughly $538 million in fiscal 2025 and about $407 million in fiscal 2024. That is a fast pace for a company that is already at meaningful scale. The latest growth metrics also show year-over-year revenue growth around 29%, clearly above the sector median.
Another important catalyst is the broader enterprise transition toward platform consolidation in cybersecurity. If customers continue replacing separate web gateway, VPN, cloud access security, and data protection tools with integrated platforms, Netskope is operating in an area where spending can shift in its favor. Its emphasis on SSE and zero trust also aligns with how many large organizations are redesigning security architecture.
There is also a market-structure angle. Netskope is large enough to compete for enterprise contracts, but still small relative to the biggest platform companies in cybersecurity and networking. That leaves room for share gains if execution remains strong and customer adoption broadens internationally and across product modules.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


