Stock Analysis · NAPCO Security Technologies Inc (NSSC)
Overview
NAPCO Security Technologies is a U.S. security equipment company focused on products used to protect buildings and control access. It designs and sells electronic door-locking systems, access-control platforms, intrusion and fire alarm systems, and communication services that connect alarm panels to monitoring centers. Its customers are mainly security dealers, system integrators, distributors, and commercial or institutional building operators.
The business mixes hardware sales with recurring service revenue. That matters because hardware can be more cyclical, while service subscriptions can add stability and usually carry higher margins. In recent filings, management has continued to emphasize school security, commercial access control, wireless locks, and cloud-connected alarm communications as major priorities.
Based on the company’s latest annual filing, revenue is concentrated in a few major buckets:
- Equipment sales: about 79% of revenue. This includes door-locking products, access-control systems, intrusion and fire alarm panels, and related hardware.
- Service revenue: about 21% of revenue. This primarily includes recurring cellular communication and network services tied to alarm reporting and remote connectivity.
Within equipment, NAPCO highlights access control and locking solutions as a central growth area, especially products aimed at schools, hospitals, multifamily housing, and commercial buildings. Within services, the recurring revenue base is tied to installed devices already in the field, which can create a longer-lasting customer relationship than a one-time hardware sale.
The company’s financial structure has improved over the last several years. Revenue has expanded from roughly $144 million in fiscal 2022 to just above $200 million in fiscal 2026, while gross profit has grown faster than sales. That points to a business mix shifting toward higher-value products and services, even though operating expenses have also risen as the company invests in sales, administration, and product development.
The main pattern is rising revenue and a much larger gross profit base than a few years ago, helped by a favorable mix and strong pricing discipline. Operating expenses have also moved up, especially selling and administrative costs, but profitability remains far above where it stood in 2022.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Security & Protection Services | |
| Market Cap ⓘ | $1.29B | |
| Beta ⓘ | 1.50 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 30.15 | 22.10 |
| P/B Ratio ⓘ | 6.58 | 1.97 |
| FCF Yield ⓘ | 4.58% | 6.38% |
| Dividend Yield ⓘ | 1.60% | 1.94% |
| EBIT / EV ⓘ | 4.32% | 4.79% |
| PEG ⓘ | 16.27 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.00% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 9.68% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | 36.78% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 8.77% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | 9.21% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 71.48% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 73.63% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 23.72% | 10.84% |
| ROA (Latest) ⓘ | 19.35% | 5.41% |
| ROIC (5Y Median) ⓘ | 23.93% | 9.38% |
| ROA (5Y Median) ⓘ | 19.70% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | -2.44 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.55 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | -2.34 | 1.39 |
| Net Debt / Assets ⓘ | -51.01% | 19.28% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | 24.63% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 24.63% | 10.29% |
| Debt to Equity (Latest) ⓘ | 2.71% | 65.48% |
| Profit Margin (Latest) ⓘ | 21.27% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $59.23M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +79.39% | +61.68% |
| 12M Return (excl. last month) ⓘ | -13.12% | +12.58% |
| 6M Return ⓘ | -20.00% | 0.00% |
| Price vs. 200-Day MA ⓘ | -10.32% | +0.02% |
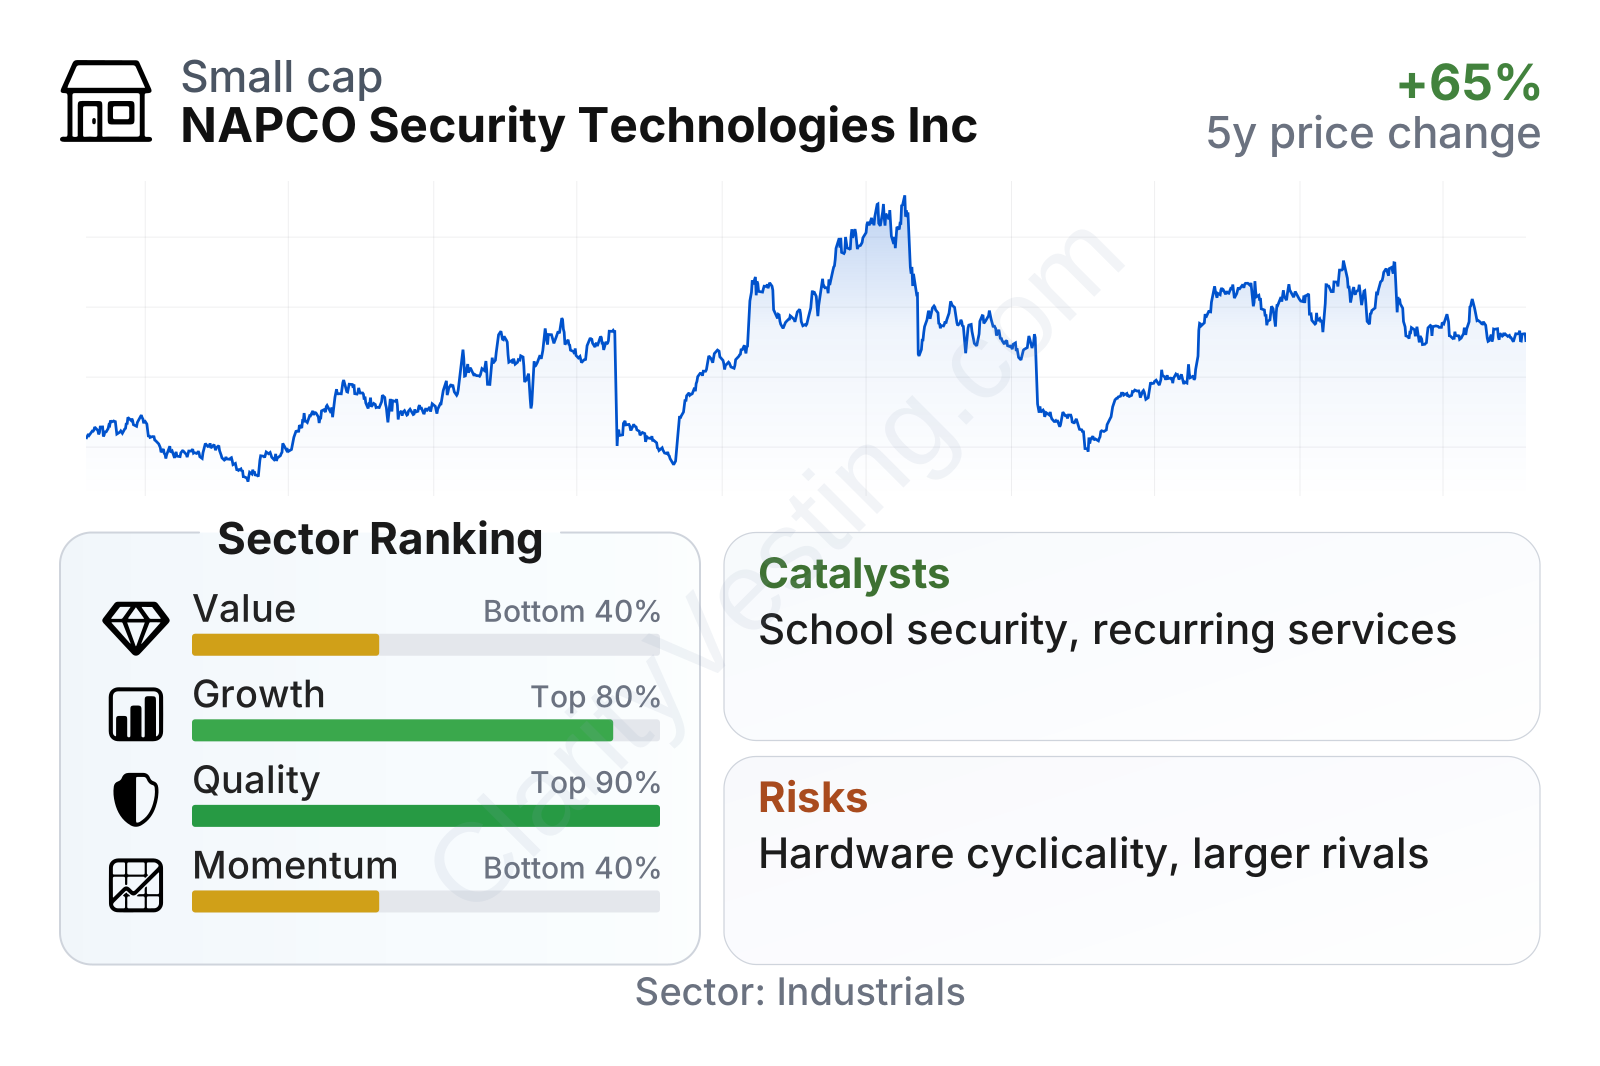
NAPCO stands out more for business quality than for cheapness. Profitability, returns on capital, and balance-sheet strength rank well above much of the industrials universe, while valuation and recent share-price momentum are less favorable. In simple terms, the company looks financially strong and efficiently run, but the market still assigns it a premium compared with many peers, even after a weaker recent stock trend.
Growth
NAPCO operates in security, life safety, and electronic access control, all of which are supported by long-term demand. Schools and public buildings continue to spend on door security and lockdown capabilities. Commercial buildings are gradually replacing older mechanical systems with connected access-control platforms. In parallel, alarm communication is moving away from legacy technologies toward cellular and network-based services. These are not temporary shifts; they are structural changes that can support demand over many years.
The company’s strategy is coherent with those trends. Its product lineup addresses both upfront equipment demand and recurring communication revenue after installation. That combination can be powerful: each new device sale can create a future service relationship, and each installed base expansion can make revenue less dependent on the next hardware order cycle. Management has also leaned into products such as wireless locks and school-focused entry systems, which fit current customer priorities around safety, easier retrofits, and centralized control.
Growth has not been perfectly smooth, but the broader direction remains positive. After very strong expansion earlier in the period, revenue growth cooled and even briefly turned negative in late 2024, then recovered into fiscal 2026. The latest year-over-year pace is around 10%, slightly ahead of the sector median, which suggests the company is still growing at a healthy rate even after a period of normalization.
Cash generation has strengthened meaningfully over time. Free cash flow has risen from low levels a few years ago to roughly the high tens of millions on a trailing basis. That matters because it shows the business is not just reporting accounting profits; it is also converting a meaningful share of earnings into cash that can support dividends, product development, and balance-sheet flexibility.
A notable recent opportunity is the continued push for school and institutional security upgrades in the United States. NAPCO has repeatedly positioned its locking and access products for this market, and tighter safety requirements or district-level funding programs could continue to support demand. Another useful catalyst is the recurring service base: as more cellular communicators and connected devices are installed, the service line can grow faster than hardware over time and improve margin durability.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


