Stock Analysis · NRG Energy Inc (NRG)
Overview
NRG Energy is a U.S. power and energy company that combines electricity generation with a large retail energy business. In simple terms, it produces power, buys and sells electricity and natural gas in wholesale markets, and supplies homes and businesses with retail electricity services. Over time, NRG has shifted away from being mainly a traditional power plant owner and has built a broader customer-focused platform, especially after expanding its retail and home-services footprint through acquisitions.
Its business is largely tied to two engines: selling energy to end customers and managing a fleet of power generation assets that can capture value when electricity demand is high. That mix makes NRG different from a regulated utility. It has more exposure to energy market prices, but it also has more room to benefit from strong power demand, effective hedging, and customer growth.
Based on recent company reporting, revenue is primarily generated from customer-facing electricity and related energy sales, with additional contribution from generation and wholesale activities. A practical way to think about the business is:
- Retail electricity and energy services: approximately 70% to 80% of revenue. This includes electricity sold to residential, commercial, and industrial customers, plus related retail products and energy management offerings.
- Wholesale and generation-related sales: approximately 20% to 30% of revenue. This includes electricity produced by NRG’s generation fleet, capacity revenues, and market-based energy trading and optimization.
- Other services: a small share of revenue. This can include home-related energy services and smaller ancillary activities depending on the reporting period and acquisitions.
That revenue mix matters because the retail business tends to provide recurring customer demand, while the generation side can add upside when power markets tighten. It also means reported revenue can move around with commodity prices even when the underlying customer base is stable.
The multiyear income flow shows a business with large revenue swings but much more uneven profit conversion. Revenue recovered in 2025 after a weaker 2024, gross profit improved, but net income remained pressured by higher operating costs and interest expense. This reinforces an important point for long-term analysis: NRG’s headline sales can look strong while bottom-line results remain volatile.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Utilities | |
| Industry | Utilities - Independent Power Producers | |
| Market Cap ⓘ | $21.20B | |
| Beta ⓘ | 1.16 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 26.40 | 17.28 |
| P/B Ratio ⓘ | 4.40 | 1.51 |
| FCF Yield ⓘ | 1.64% | 0.65% |
| Dividend Yield ⓘ | 1.74% | 3.77% |
| EBIT / EV ⓘ | 3.29% | 5.01% |
| PEG ⓘ | 0.39 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 11.00% | 6.10% |
| RPS Growth (5Y CAGR) ⓘ | 8.79% | 3.87% |
| EPS Growth (5Y CAGR) ⓘ | -1.39% | -11.30% |
| BVPS Growth (5Y CAGR) ⓘ | -12.92% | 4.23% |
| Margin Growth (5Y Trend) ⓘ | -6.37% | 3.57% |
| FCF Growth (5Y CAGR) ⓘ | 35.99% | -8.84% |
| DPS Growth (5Y CAGR) ⓘ | 12.23% | 4.84% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.35% | 6.53% |
| ROA (Latest) ⓘ | 2.66% | 3.20% |
| ROIC (5Y Median) ⓘ | 12.72% | 5.95% |
| ROA (5Y Median) ⓘ | 4.49% | 2.75% |
| Net Debt / EBIT (Latest) ⓘ | 15.71 | 7.13 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.78 | 7.23 |
| Net Debt / EBITDA (Latest) ⓘ | 7.39 | 4.31 |
| Net Debt / Assets ⓘ | 58.35% | 38.42% |
| EBITDA / Interest ⓘ | 2.97 | 4.58 |
| Operating Margin (Latest) ⓘ | 4.47% | 20.83% |
| Operating Margin (5Y Median) ⓘ | 6.59% | 20.08% |
| Debt to Equity (Latest) ⓘ | 483.36% | 137.69% |
| Profit Margin (Latest) ⓘ | 2.56% | 11.37% |
| Free Cash Flow (Latest) ⓘ | $348.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +159.90% | +52.37% |
| 12M Return (excl. last month) ⓘ | -33.38% | +8.84% |
| 6M Return ⓘ | -40.62% | -3.95% |
| Price vs. 200-Day MA ⓘ | -26.98% | -0.79% |
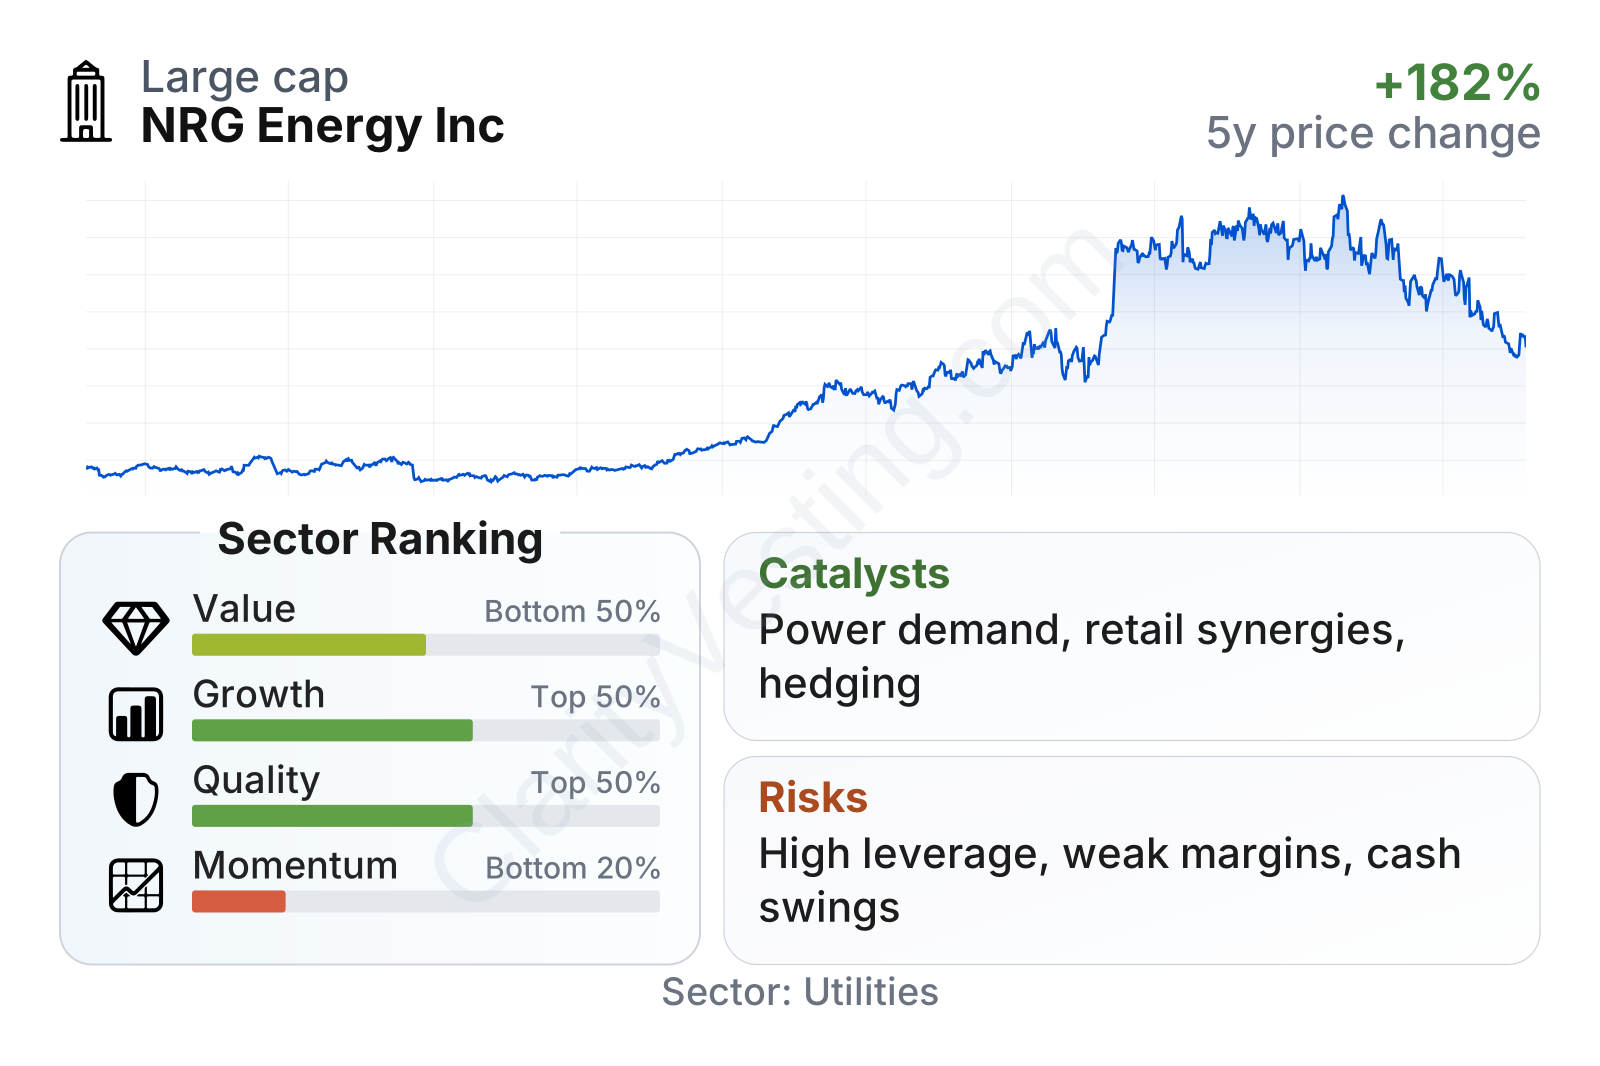
NRG is a large company within the independent power producer space, and its current profile is mixed. Growth and quality indicators are generally better than the sector median, helped by strong returns on invested capital and solid multiyear expansion in revenue per share and free cash flow. At the same time, value metrics do not screen as especially cheap relative to the utility sector, and recent share-price momentum has weakened sharply after a very strong multiyear run. The biggest balance-sheet watchpoint remains leverage, which is well above typical sector levels.
Growth
NRG operates in a part of the power market that is benefiting from several long-term demand drivers. U.S. electricity demand is getting support from data centers, industrial reshoring, electrification, and the need for grid reliability during extreme weather. These trends do not lift every utility equally, but they can be especially important for companies with flexible generation assets and meaningful exposure to competitive power markets.
NRG’s strategy broadly fits that backdrop. The company has emphasized integrated retail-and-generation operations, cost discipline, capital returns, and the ability to serve customers across multiple regions. Its acquisition activity has also strengthened its consumer-facing scale. In plain language, NRG is trying to pair a large customer base with generation assets that can supply or hedge that demand. If managed well, that can create a more durable earnings base than relying on wholesale power markets alone.
Revenue per share has moved higher over the last five years, with the strongest step-up appearing in the most recent year. That suggests growth has not come only from inflation in energy prices; on a per-share basis, the company has also expanded its business scale. This is a helpful signal for long-term readers because it points to real commercial progress rather than just temporary market noise.
Free cash flow has been much more volatile than revenue. NRG has shown that it can generate strong cash in favorable periods, but the pattern is not smooth and the latest trailing figure has turned negative. For a company with a leveraged balance sheet and active capital allocation plans, that volatility is one of the central issues to monitor. Strong long-term growth is more convincing when cash generation becomes more consistent from year to year.
A notable near-term catalyst is the broader tightening in power markets linked to rising load demand, especially from data infrastructure. NRG has repeatedly positioned itself around reliability, dispatchable generation, and retail scale, which could become more valuable if reserve margins stay constrained in key regions. The company has also highlighted synergy capture and integration benefits from recent acquisitions, which could support earnings if execution remains on track.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


