Stock Analysis · Enpro Industries (NPO)
Overview
Enpro Industries is a specialized industrial company that makes engineered products used in demanding environments. Its businesses are centered on applications where reliability, contamination control, sealing performance, and precision matter more than low cost. In practical terms, Enpro sells components and systems used in semiconductor manufacturing, industrial process equipment, pumps, compressors, heavy machinery, and other mission-critical equipment.
The company operates through two main segments: Sealing Technologies and Advanced Surface Technologies. Sealing Technologies includes sealing products, metal polymer bearings, and related engineered components used across industrial markets. Advanced Surface Technologies is more exposed to semiconductor and other high-tech manufacturing needs, including products that help customers control contamination, manage wafer handling, and improve process performance.
Based on recent annual reporting, Enpro’s revenue mix is approximately:
- Sealing Technologies: about 59% of revenue. This segment includes industrial sealing systems, bearings, and other engineered products serving general industrial, power generation, aerospace, and process industries.
- Advanced Surface Technologies: about 41% of revenue. This segment includes semiconductor-focused products such as contamination-control components, wafer-handling solutions, and advanced materials technologies.
This mix matters because it gives Enpro exposure to two different rhythms: a steadier industrial base on one side and a more cyclical but potentially faster-growing semiconductor-related business on the other. Over the last several years, sales have moved from roughly $840 million in 2021 to more than $1.1 billion in 2025, showing that the company has become meaningfully larger even though earnings have been uneven.
The business flow also shows a useful pattern: revenue and gross profit have generally expanded since 2021, but net income has been much more volatile. That suggests the company can grow sales, yet the final profit line is still sensitive to costs, interest expense, and integration or operating pressures.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Industrial Machinery | |
| Market Cap ⓘ | $6.51B | |
| Beta ⓘ | 1.55 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 149.38 | 22.45 |
| P/B Ratio ⓘ | 4.07 | 1.98 |
| FCF Yield ⓘ | 2.51% | 6.31% |
| Dividend Yield ⓘ | 0.41% | 1.96% |
| EBIT / EV ⓘ | 1.33% | 4.81% |
| PEG ⓘ | 1.88 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 17.60% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 7.74% | 7.75% |
| EPS Growth (5Y CAGR) ⓘ | -12.12% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 4.75% | 6.22% |
| Margin Growth (5Y Trend) ⓘ | -1.77% | 0.72% |
| FCF Growth (5Y CAGR) ⓘ | 6.62% | 10.98% |
| DPS Growth (5Y CAGR) ⓘ | 3.75% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 3.36% | 10.92% |
| ROA (Latest) ⓘ | 1.74% | 5.41% |
| ROIC (5Y Median) ⓘ | 3.02% | 9.21% |
| ROA (5Y Median) ⓘ | 2.92% | 4.94% |
| Net Debt / EBIT (Latest) ⓘ | 5.51 | 2.07 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.04 | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | 2.56 | 1.43 |
| Net Debt / Assets ⓘ | 19.23% | 19.27% |
| EBITDA / Interest ⓘ | 5.90 | 9.53 |
| Operating Margin (Latest) ⓘ | 7.59% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 8.01% | 10.27% |
| Debt to Equity (Latest) ⓘ | 37.07% | 65.48% |
| Profit Margin (Latest) ⓘ | 3.60% | 6.62% |
| Free Cash Flow (Latest) ⓘ | $163.40M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +157.67% | +58.56% |
| 12M Return (excl. last month) ⓘ | +36.10% | +15.63% |
| 6M Return ⓘ | +22.45% | +4.19% |
| Price vs. 200-Day MA ⓘ | +6.54% | +0.93% |
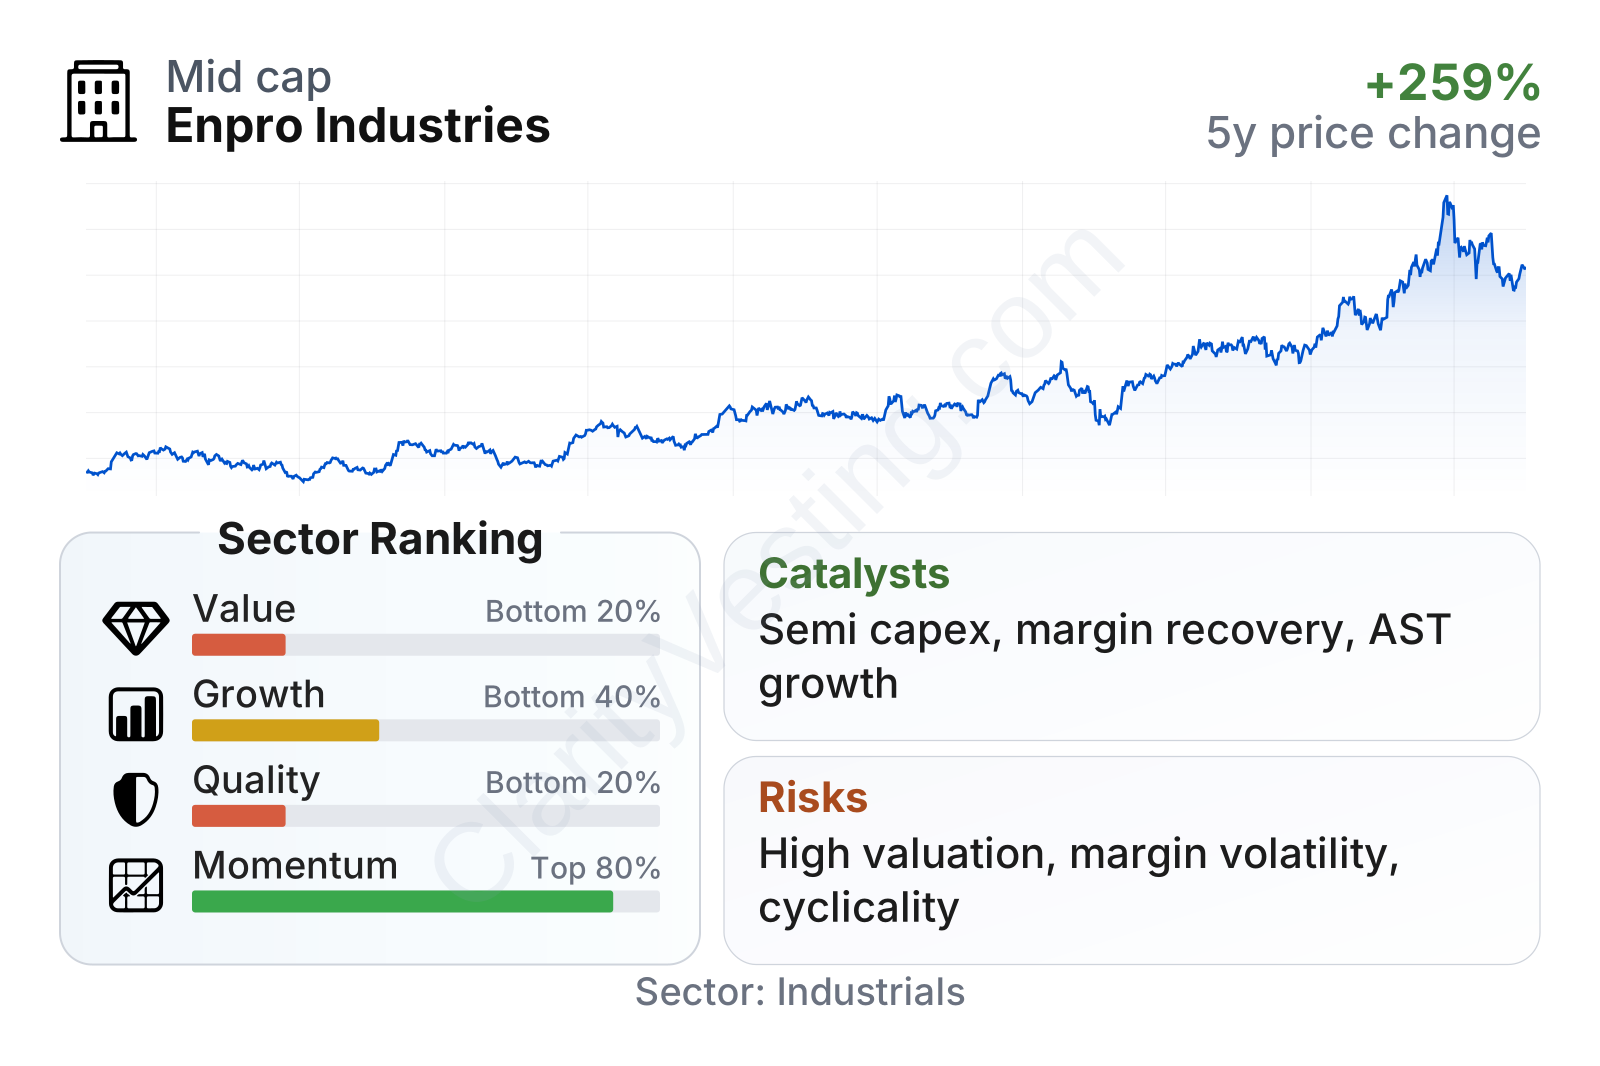
Enpro is now a mid-sized industrial company with a stock that has strongly outperformed much of its sector over the last three years. At the same time, the latest overall profile is mixed: recent revenue growth is solid, but profitability, returns on capital, and balance-sheet efficiency remain weaker than many industry peers. The market is currently assigning a rich valuation despite those softer quality metrics, which means expectations have risen faster than operating performance.
Growth
Enpro is active in markets that have attractive long-term drivers, especially semiconductor equipment and high-specification industrial applications. The semiconductor side benefits from structural demand linked to artificial intelligence infrastructure, advanced chips, and the global push for more manufacturing capacity. The industrial side is less exciting, but it tends to be more diversified and can provide resilience when chip-related demand weakens.
The company’s strategy also makes sense on paper. Enpro focuses on niche products where failure is costly for customers, which can support pricing power and recurring replacement demand. Its portfolio has gradually tilted toward businesses with higher technical barriers, especially through its Advanced Surface Technologies operations. That shift could improve the company’s growth profile if semiconductor demand stays healthy and if execution remains disciplined.
Recent revenue momentum has improved noticeably. After a softer period in 2023 and early 2024, year-over-year growth turned positive and then accelerated, reaching a high-teens pace in the latest reading. That is well above the sector median and suggests the company is currently participating in a stronger demand environment rather than merely treading water.
Cash generation has also held up reasonably well. Free cash flow has moved upward over time and is now around the upper end of its recent range. That is important because Enpro’s investment case depends not only on revenue growth, but also on turning that growth into cash that can support debt service, acquisitions, and internal investment.
A meaningful catalyst is the company’s exposure to semiconductor capital spending through contamination-control and wafer-handling products. If foundry and advanced packaging investment remains elevated, Enpro has a clear path to capture incremental demand. Another positive factor is that highly engineered components are often embedded deeply in customer processes, which can make revenue sticky once qualified. In recent company communications, management has continued to emphasize operational improvement, portfolio focus, and demand tied to advanced semiconductor manufacturing, all of which support the growth narrative.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


