Stock Analysis · Neo Performance Materials Inc (NOPMF)
Overview
Neo Performance Materials Inc. is a specialty materials company focused on products that sit deeper in industrial supply chains rather than consumer-facing brands. Its business is centered on magnetic materials, rare earth-related processing, and advanced industrial materials used in areas such as electric vehicles, electronics, industrial motors, catalysts, and other high-performance manufacturing applications. For long-term readers, the easiest way to think about Neo is as a company tied to the demand for energy efficiency, electrification, and high-specification manufacturing, but also exposed to commodity pricing and industrial cycles.
The company reports through three main business segments. Based on the latest annual mix disclosed in company filings, revenue is roughly distributed as follows:
- Magnequench: about 39% of revenue. This segment makes magnetic powders and bonded magnets used in traction motors, automotive systems, industrial motors, and electronics.
- Chemicals & Oxides: about 38% of revenue. This includes rare earth and zirconium-based materials, separation and refining activities, and products used in catalysts, polishing, ceramics, and other industrial applications.
- Rare Metals: about 23% of revenue. This segment produces metals and specialty materials used in electronics, medical, aerospace, and other precision applications.
Geographically, Neo is diversified across Asia, Europe, and North America, which helps reduce dependence on a single end market. At the same time, its operations remain closely linked to global manufacturing conditions and rare earth supply chains, especially in China and Europe. Over the last several years, revenue peaked in 2022, then declined in 2023 and 2024 before showing signs of stabilization. Gross profit has held up better than revenue, but operating profit and net income have been under pressure, showing that the business still has work to do on cost absorption and margin recovery.
The longer-term picture shows a meaningful change in earnings quality. Revenue has moved down from the 2022 peak, while gross profit has been more resilient, suggesting some pricing discipline and mix support. However, selling, general, and administrative costs have risen, and operating income has compressed sharply, which explains why recent net results have remained weak despite still-positive gross profit.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $1.03B | |
| Beta ⓘ | 1.63 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.90 |
| P/B Ratio ⓘ | 2.15 | 1.65 |
| FCF Yield ⓘ | -10.59% | 5.76% |
| Dividend Yield ⓘ | 1.39% | 2.13% |
| EBIT / EV ⓘ | 3.12% | 6.30% |
| PEG ⓘ | 1.11 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 79.40% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | -4.76% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -4.31% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -6.94% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -3.30% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 5.28% | 9.26% |
| ROA (Latest) ⓘ | 0.20% | 4.91% |
| ROIC (5Y Median) ⓘ | 1.16% | 7.70% |
| ROA (5Y Median) ⓘ | -1.30% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 1.40 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.80 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.98 | 0.95 |
| Net Debt / Assets ⓘ | 5.85% | 13.69% |
| EBITDA / Interest ⓘ | 10.91 | 12.34 |
| Operating Margin (Latest) ⓘ | 5.95% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 2.31% | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | 0.26% | 6.43% |
| Free Cash Flow (Latest) ⓘ | -$108.67M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +310.98% | +68.89% |
| 12M Return (excl. last month) ⓘ | +80.93% | +30.21% |
| 6M Return ⓘ | +41.31% | -4.16% |
| Price vs. 200-Day MA ⓘ | +10.72% | -1.27% |
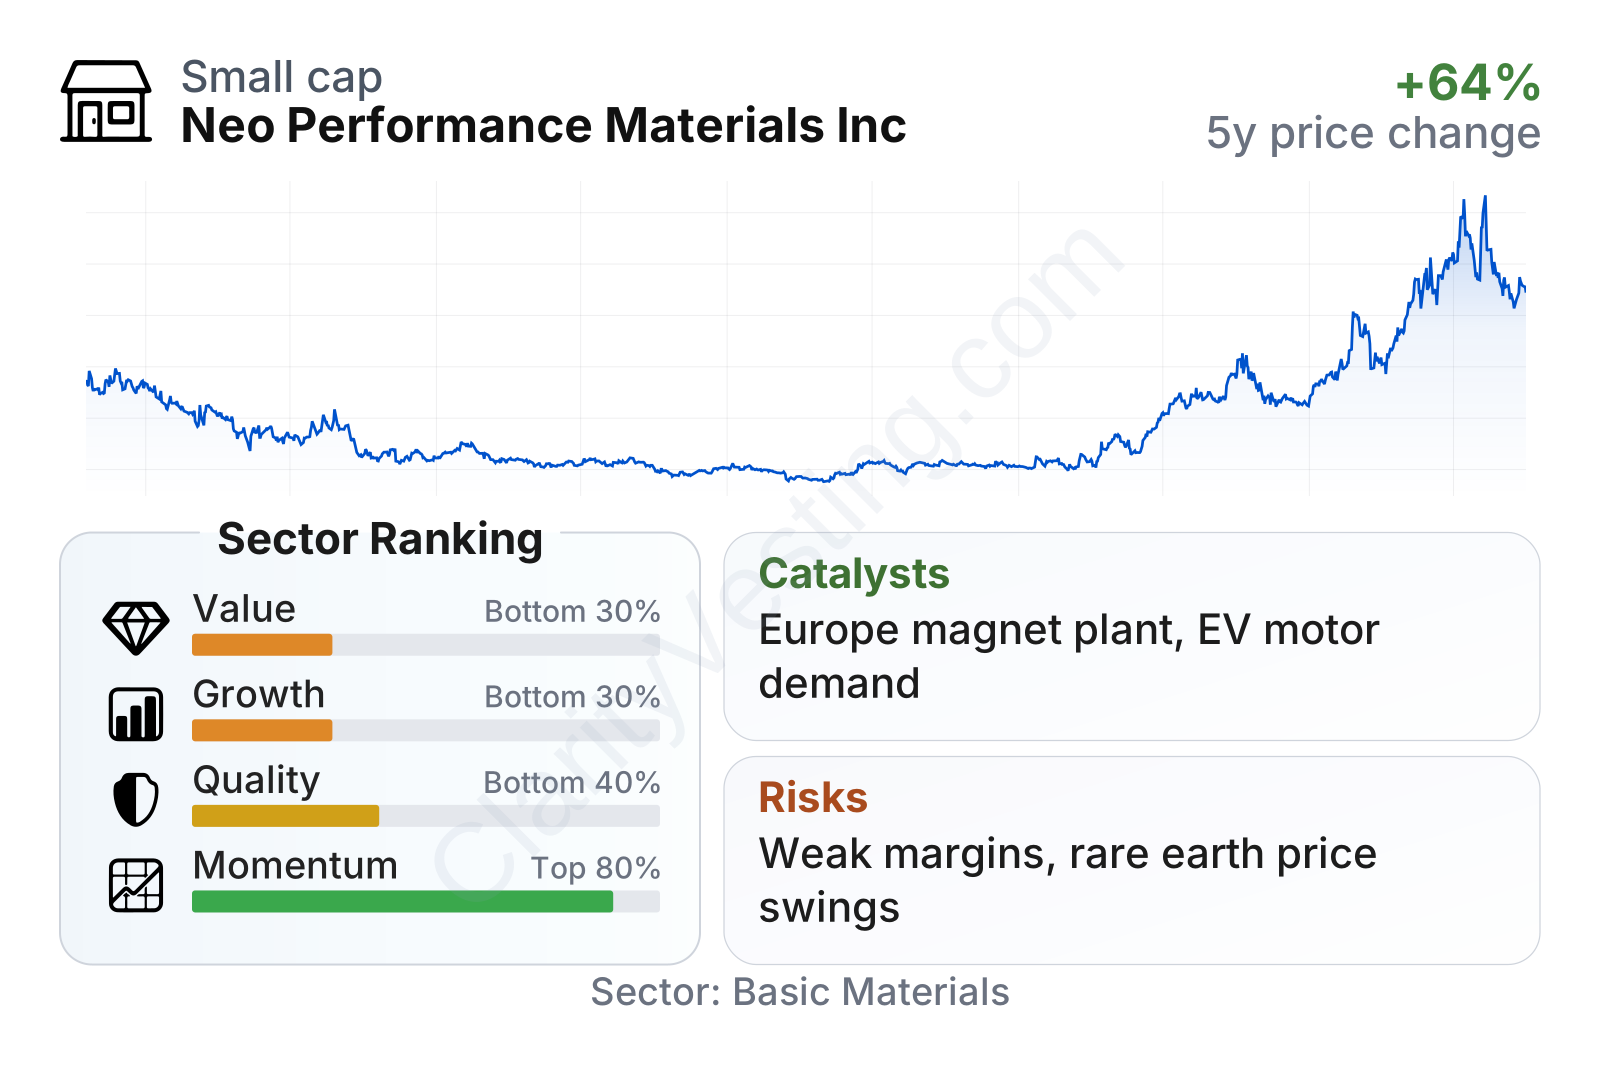
Neo is a small-cap materials company with above-average share price volatility. The stock’s recent market performance has been strong, but the underlying fundamentals are more mixed. Relative to the broader Basic Materials group, current value metrics do not look especially cheap on operating earnings, and cash generation has been weak. Quality and growth rankings also sit in the lower half of the sector, reflecting soft profitability and uneven multi-year trends, even though short-term revenue growth has recently rebounded sharply.
The combination is unusual: market momentum is strong, but core profitability remains modest. That can happen when investors are starting to price in a cyclical recovery, a strategic project, or a better industry backdrop before it fully shows up in earnings.
Growth
Neo operates in markets that should remain structurally relevant over a multi-year horizon. Electric vehicles, energy-efficient motors, automation, defense electronics, and advanced manufacturing all require specialized materials, including magnetic powders and rare earth-related inputs. That does not mean demand rises in a straight line, but it does mean the company is positioned in segments that matter for long-term industrial trends.
Its strategy also has a clear logic. Neo has been building around higher-value processing rather than simply acting as a low-margin raw materials seller. That matters because the most attractive part of the rare earth chain is often not mining itself, but refining, formulation, and engineered end-use materials. The company has also emphasized supply-chain diversification outside China, which has become more important as governments and manufacturers seek alternative sourcing for strategic materials.
A major growth catalyst is Neo’s rare earth permanent magnet project in Europe, designed to support regional automotive and industrial customers. If ramped successfully, that facility could strengthen Neo’s position in a market where customers increasingly want local, traceable supply. This is strategically important because permanent magnets are a critical input for many electric motors, and non-Chinese processing capacity remains limited.
Recent operating trends show why the market has become more interested again. Revenue growth had been negative through much of 2023 and 2024, reflecting a weak industrial environment, but more recent figures indicate a sharp rebound from those depressed levels.
The rebound needs to be viewed carefully. A very strong year-over-year growth rate can partly reflect easier comparisons after a weak period, so what matters most is whether the company can turn that sales recovery into sustained margin improvement. For long-term analysis, the key question is not just whether orders recover, but whether Neo can rebuild profitability as volumes normalize.
Cash generation remains the part of the growth case that needs the most confirmation. Free cash flow has been volatile and is currently negative on a trailing basis. That does not automatically weaken the strategic opportunity, especially if spending is supporting future capacity and customer programs, but it does mean the growth case is still more visible in industrial positioning than in current cash returns.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


