Stock Analysis · Nongfu Spring Co. Ltd (NNFSF)
Overview
Nongfu Spring Co. Ltd is a Chinese beverage company best known for packaged drinking water, but it has expanded into a broader non-alcoholic drinks platform. Its products include natural water, ready-to-drink tea, functional beverages, juice drinks, and other packaged beverages. The business is aimed at everyday consumption, which places it in a defensive part of the consumer market: people continue to buy beverages in both strong and weak economic environments, although product mix and pricing can still change.
The company’s revenue base is still centered on water, but tea and other beverages have become increasingly important. Based on the company’s annual reporting and product disclosures, the main revenue sources are approximately:
- Packaged drinking water: about 45% to 50% of revenue in recent years. This includes the company’s flagship natural water products and remains the core of the brand.
- Tea beverages: about 35% to 40%. This category includes ready-to-drink tea products and has become a major growth engine.
- Functional drinks: about 5% to 10%. These are beverages marketed around energy, vitamins, or performance-related usage.
- Juice drinks: about 5% to 10%. This includes fruit-based packaged drinks.
- Other products: usually a small residual share, including newer beverage lines and related items.
Nongfu Spring’s appeal comes from combining mass-market scale with premium branding. In practical terms, it sells products with the wide reach of a staple consumer company, while often earning margins closer to a stronger branded franchise than a commodity beverage producer.
The multi-year profit flow also shows an important pattern: revenue has climbed materially since 2021, while gross profit and operating income have grown even faster. That suggests the company has not merely sold more units; it has also kept pricing power and cost discipline.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Beverages - Non-Alcoholic | |
| Market Cap ⓘ | $59.89B | |
| Beta ⓘ | 0.24 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 24.20 | 17.88 |
| P/B Ratio ⓘ | 1.59 | 1.29 |
| FCF Yield ⓘ | 42.18% | 12.39% |
| Dividend Yield ⓘ | 19.08% | 2.85% |
| EBIT / EV ⓘ | N/A | 6.43% |
| PEG ⓘ | 1.97 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 16.00% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 14.59% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | 15.92% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 17.47% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 8.01% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 12.10% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 44.46% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 12.34% |
| ROA (Latest) ⓘ | 40.16% | 6.30% |
| ROIC (5Y Median) ⓘ | 36.07% | 10.49% |
| ROA (5Y Median) ⓘ | 24.38% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | -0.45 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.32 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | -0.39 | 1.38 |
| Net Debt / Assets ⓘ | -20.65% | 21.51% |
| EBITDA / Interest ⓘ | N/A | 9.46 |
| Operating Margin (Latest) ⓘ | 37.20% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 37.00% | 9.53% |
| Debt to Equity (Latest) ⓘ | 14.19% | 72.35% |
| Profit Margin (Latest) ⓘ | 30.24% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $25.26B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +5.90% | +20.92% |
| 12M Return (excl. last month) ⓘ | -11.15% | +2.13% |
| 6M Return ⓘ | -15.60% | +1.26% |
| Price vs. 200-Day MA ⓘ | -8.25% | +1.39% |
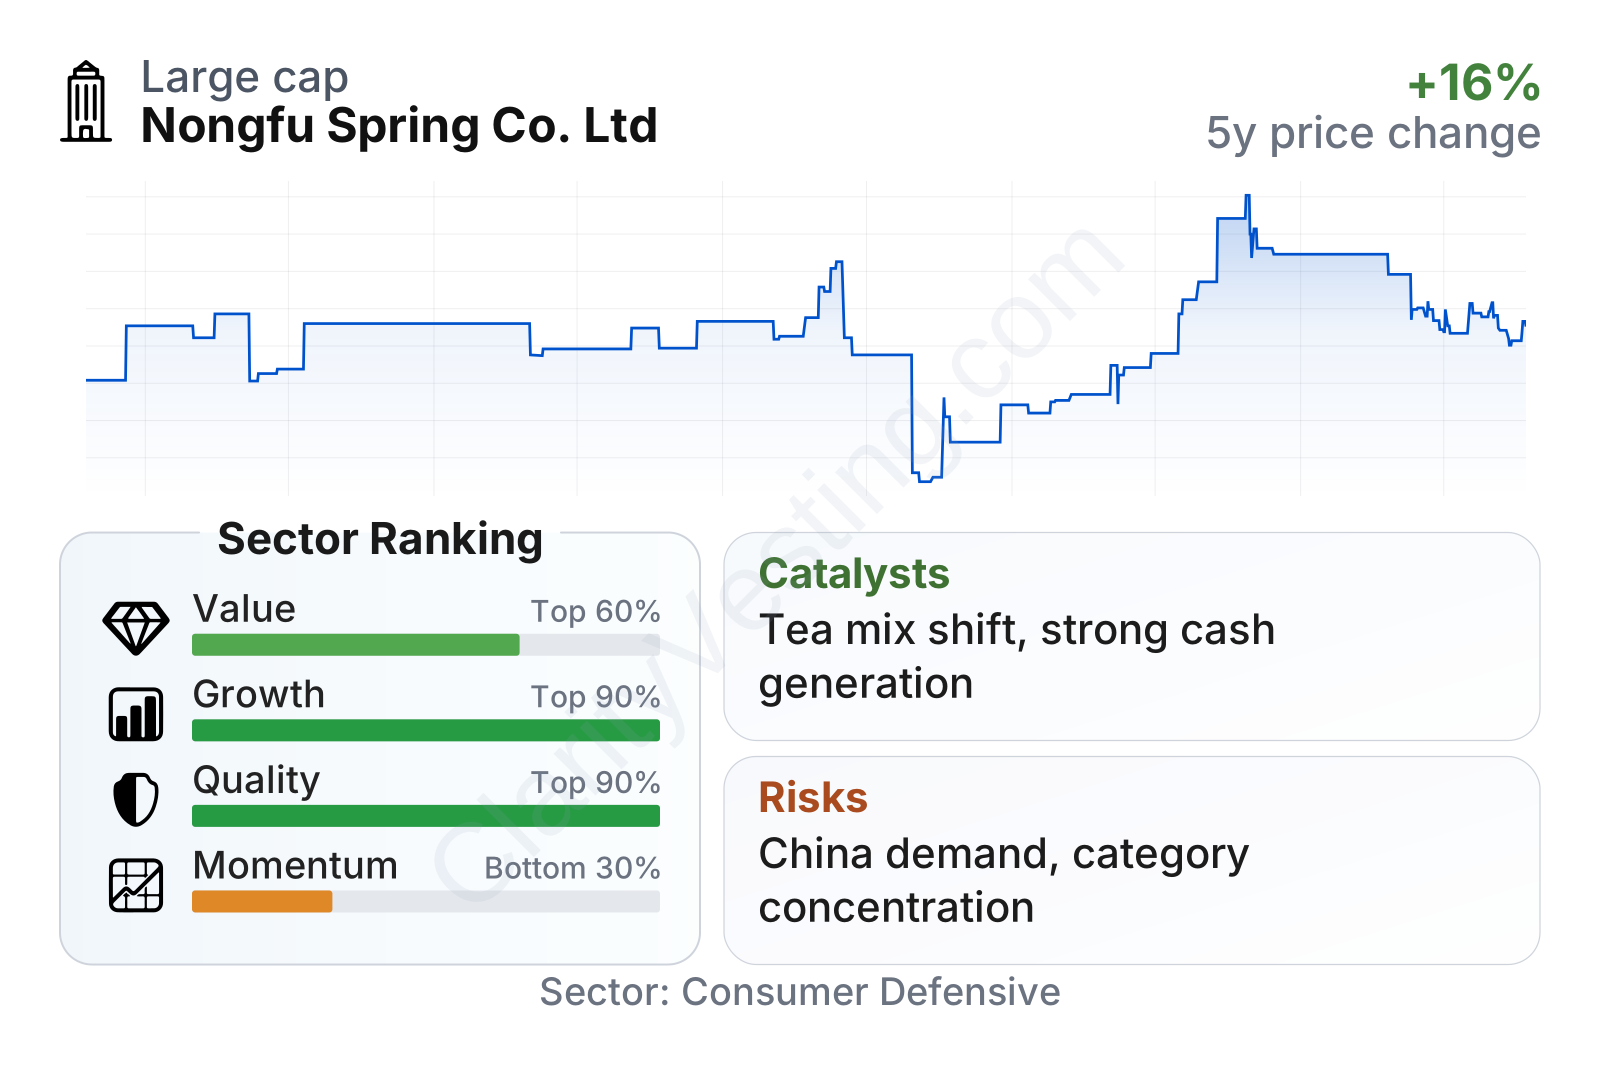
Nongfu Spring stands out on growth and quality, where it ranks near the top of its sector. Revenue growth is running well above the sector median, and its five-year gains in revenue per share, earnings per share, book value, and free cash flow all point to a business that has compounded steadily rather than relying on one-off spikes. Profitability is especially strong: operating margin is around the high-30% range versus a sector median below 10%, and profit margin is also far ahead of most peers.
The balance sheet is another notable strength. The company carries low leverage and currently has net cash rather than meaningful net debt, which gives it room to fund expansion, absorb volatility, and maintain distributions. Free cash flow generation is also unusually strong for a consumer beverage company of this size.
Valuation is not extremely stretched on basic multiples, but it is not cheap either. The earnings multiple and book multiple are somewhat above sector medians, which indicates the market continues to assign a premium for quality and growth. At the same time, recent price momentum has been weak, with the shares trailing much of the sector over the last six to twelve months and sitting below longer-term trend levels. That combination often reflects a business with strong fundamentals but softer sentiment.
Growth
Nongfu Spring operates in a sector with durable long-term demand. China’s non-alcoholic beverage market benefits from urbanization, convenience retail, premiumization, and continued interest in healthier drink choices compared with sugary carbonated products. Bottled water remains a basic consumption category, while ready-to-drink tea has been one of the more attractive segments because it can support both higher pricing and strong repeat purchases.
The company’s strategy appears coherent for future expansion. It already has a nationwide brand, broad distribution, and strong recognition in water, and it is using that platform to deepen its position in tea and other categories. This matters because water offers scale and brand trust, while tea and functional drinks can improve growth and category diversification. A beverage company that can cross-sell across multiple daily-use categories typically becomes more resilient over time.
One of the clearest catalysts is mix shift. If tea beverages continue to grow faster than packaged water, the company could gradually become less dependent on one category while preserving high margins. Another support factor is execution: over the last several years, margins have remained far above industry norms even as revenue expanded, suggesting the company has so far managed growth without sacrificing economics.
Recent operating trends also point to continued opportunity. The company has shown that it can convert revenue into cash at a high rate, and that matters because beverage growth can sometimes look attractive in sales terms while consuming large amounts of capital. Here, cash generation has remained robust, which gives future product launches and channel expansion a stronger financial base.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


