Stock Analysis · Nagacorp Ltd (NGCRY)
Overview
NagaCorp Ltd is a casino and hotel operator centered on NagaWorld, a large integrated entertainment complex in Phnom Penh, Cambodia. The group combines gaming floors, hotel rooms, restaurants, retail, meeting space, nightlife, and entertainment venues in one destination. The company is listed in Hong Kong, while the U.S. ticker NGCRY trades as an ADR.
Its business is still heavily tied to gaming, but the customer mix matters. NagaCorp serves mass-market visitors, premium players, and non-gaming guests such as hotel and event customers. The company’s position has historically been strengthened by its long-standing casino license in Phnom Penh and by exclusivity rights in a large radius around the capital, which has made NagaWorld the dominant legal casino destination in its immediate market.
Based on the company’s annual reporting structure, revenue mainly comes from the following activities:
- Gaming operations: approximately 85% to 90% of revenue in recent years. This includes mass-market tables, electronic gaming machines, premium gaming, and other casino play.
- Hotel, food and beverage, and entertainment: approximately 10% to 15% of revenue. This includes room revenue, restaurants, bars, leisure offerings, and related guest services.
That revenue mix shows a simple reality: despite being marketed as an integrated resort, NagaCorp remains primarily a gaming business, with non-gaming activities supporting traffic, occupancy, and spending inside the property.
The income profile has changed sharply since the pandemic period. Revenue and profit recovered strongly from 2021 through 2025, while financing costs dropped to a very low level by the latest year. The most striking feature is how much of each revenue dollar now reaches operating profit and free cash flow compared with the loss-making period in 2021.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 31, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Resorts & Casinos | |
| Market Cap ⓘ | $1.37B | |
| Beta ⓘ | 1.31 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 4.49 | 17.02 |
| P/B Ratio ⓘ | 0.55 | 1.61 |
| FCF Yield ⓘ | 33.33% | 8.71% |
| Dividend Yield ⓘ | 6.59% | 2.66% |
| EBIT / EV ⓘ | 74.49% | 6.51% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -8.40% | 5.50% |
| RPS Growth (5Y CAGR) ⓘ | 35.01% | 9.01% |
| EPS Growth (5Y CAGR) ⓘ | -5.38% | -16.46% |
| BVPS Growth (5Y CAGR) ⓘ | 9.85% | 5.64% |
| Margin Growth (5Y Trend) ⓘ | 119.95% | -0.17% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 5.33% |
| DPS Growth (5Y CAGR) ⓘ | -17.55% | 10.21% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 29.91% | 12.02% |
| ROA (Latest) ⓘ | 21.40% | 5.51% |
| ROIC (5Y Median) ⓘ | 5.83% | 10.72% |
| ROA (5Y Median) ⓘ | 4.28% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | -0.43 | 2.17 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.45 | 2.30 |
| Net Debt / EBITDA (Latest) ⓘ | -0.34 | 1.49 |
| Net Debt / Assets ⓘ | -10.88% | 21.53% |
| EBITDA / Interest ⓘ | N/A | 9.26 |
| Operating Margin (Latest) ⓘ | 57.19% | 9.01% |
| Operating Margin (5Y Median) ⓘ | 30.24% | 9.56% |
| Debt to Equity (Latest) ⓘ | 4.39% | 75.88% |
| Profit Margin (Latest) ⓘ | 47.75% | 5.30% |
| Free Cash Flow (Latest) ⓘ | $457.92M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -24.19% | +22.25% |
| 12M Return (excl. last month) ⓘ | -28.27% | -4.14% |
| 6M Return ⓘ | -39.22% | -0.38% |
| Price vs. 200-Day MA ⓘ | -35.04% | -1.19% |
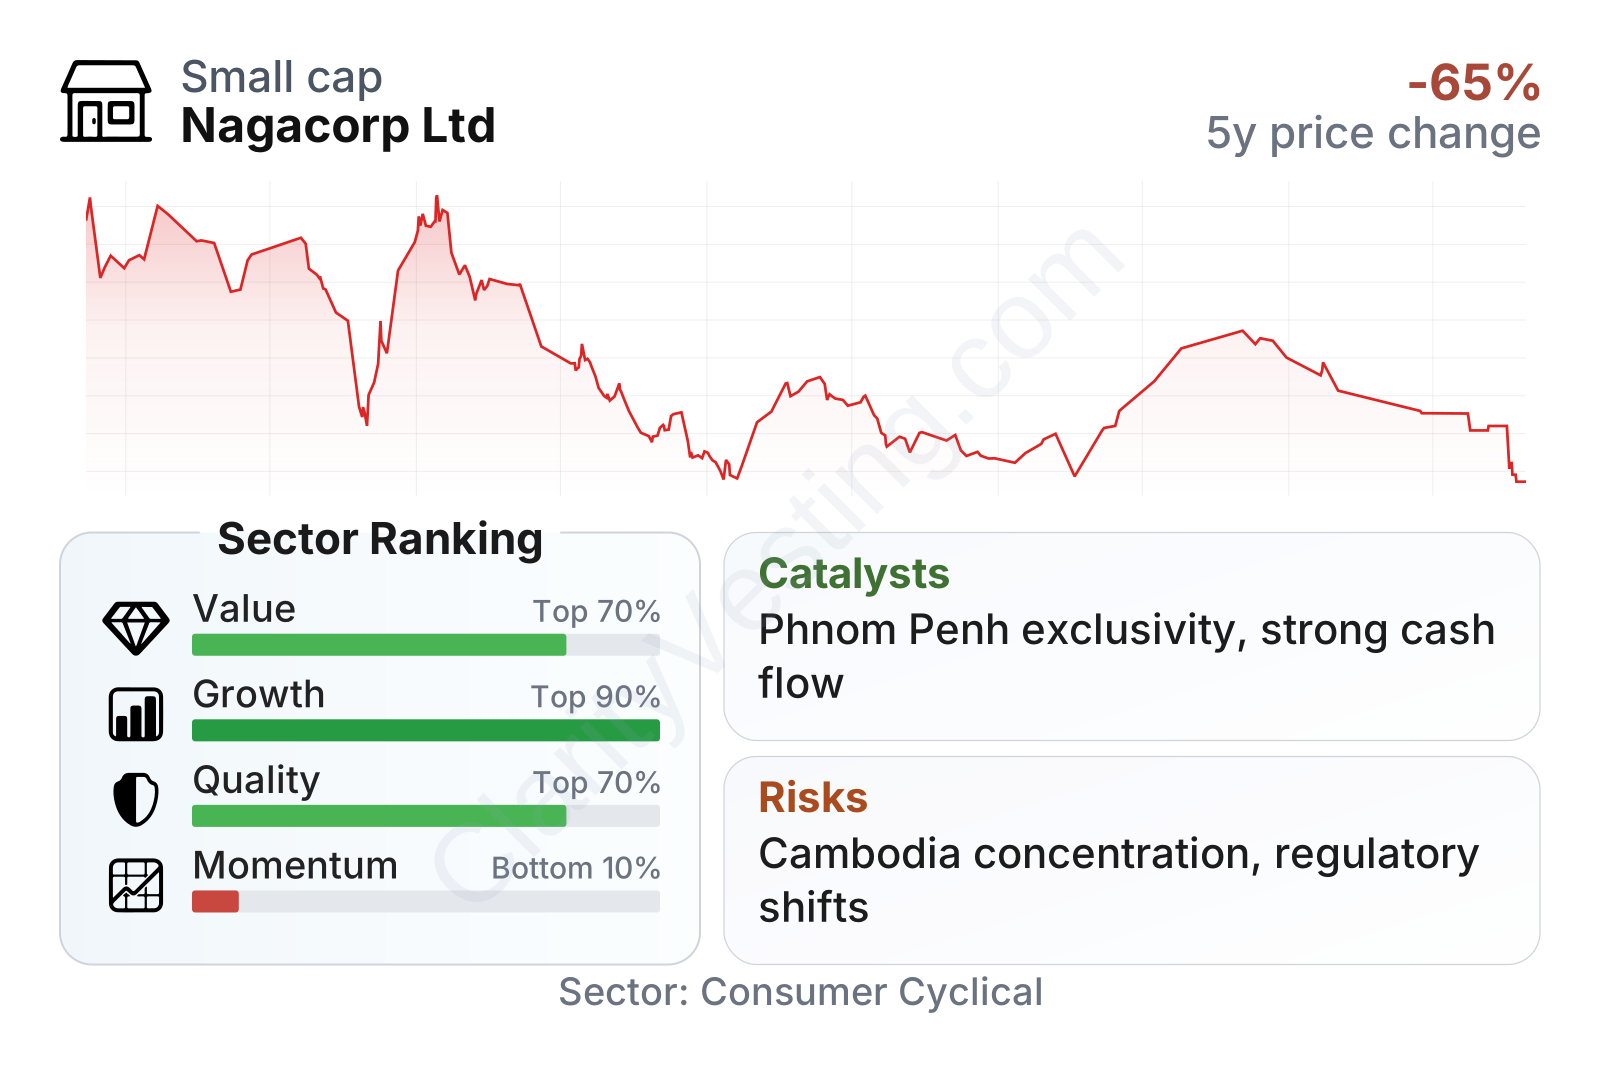
NagaCorp stands out on valuation and balance-sheet strength. Its earnings multiple and price-to-book ratio sit well below sector medians, while free cash flow yield and dividend yield are noticeably higher. On profitability, operating margin and net margin are far above typical leisure peers, and net debt metrics indicate a net cash position rather than meaningful leverage.
The weaker area is share-price momentum. Recent returns have lagged the broader consumer cyclical group by a wide margin, even though the underlying business has generated strong cash flow. Growth is also mixed: the longer-term recovery trend looks impressive, but the latest year-over-year revenue change was negative, which helps explain why the market is assigning a cautious multiple.
Growth
NagaCorp operates in a sector with long-term structural support from tourism, rising regional travel, and consumer spending on entertainment. Cambodia has benefited from growing international visitor flows over time, and Phnom Penh remains an important gateway city for business and tourism. For a casino-resort operator, that backdrop can be favorable when travel normalizes and high-value players return.
The company’s strategy is straightforward and generally coherent: use its dominant property in Phnom Penh to capture gaming demand while broadening the resort offer to keep guests on site longer. This model can work well because hotels, restaurants, events, and entertainment help feed casino traffic, even if they are not the largest direct revenue source.
A major medium-term catalyst is the company’s ability to keep converting its market position into cash generation. Recent financial performance suggests a business that has moved from post-pandemic recovery into a much more profitable phase, with strong operating leverage. If visitor traffic, premium play, and mass-market gaming volumes continue to normalize, earnings power could remain well above pre-recovery levels.
Another relevant catalyst is the company’s capital structure. With very low leverage and positive free cash flow, NagaCorp has more flexibility than many casino operators that carry heavy debt loads. That can support dividends, reinvestment, or resilience if operating conditions become uneven.
There is also a regulatory growth angle. NagaCorp’s competitive position in Phnom Penh has long been linked to its casino license and exclusivity framework. As long as that framework remains intact, the company keeps an unusually protected local market for a gaming operator.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer