Stock Analysis · Nexa Resources SA (NEXA)
Overview
Nexa Resources is a Latin American base-metals mining and smelting company focused mainly on zinc, with additional exposure to copper, lead, silver, and gold. The group operates mines in Peru and Brazil and also runs smelters, which means it is involved in both extracting ore and processing metal concentrates into refined products. That gives Nexa a more integrated business model than many smaller miners, although it also adds operational complexity.
Its revenue comes from a mix of metal sales, treatment services, and by-product credits. Based on the company’s recent annual disclosures, the sales mix is still clearly anchored in zinc-related activity, but with meaningful contributions from copper and precious metals by-products.
- Zinc and zinc-related products: approximately 45% to 55% of revenue. This includes refined zinc sold by smelters and zinc contained in concentrates from mining operations.
- Copper: approximately 15% to 25% of revenue. This comes mainly from copper in concentrates and copper-focused operations such as Cerro Lindo.
- Lead: approximately 10% to 15% of revenue. Lead is both a primary product and a by-product depending on the mine.
- Silver: approximately 10% to 15% of revenue. Silver is important economically even when it is produced as a by-product.
- Gold and other products or services: generally less than 10% combined, depending on metal prices and production mix.
Geographically, Nexa is primarily tied to South America, with Peru and Brazil representing the core of its asset base. That creates direct exposure to large mineral belts and established mining regions, but it also means country risk matters more here than for a globally diversified major miner.
The long-term business case is straightforward: Nexa is positioned around metals used in construction, infrastructure, industrial activity, and parts of the energy transition. Zinc remains essential for galvanizing steel against corrosion, while copper demand is supported by electrification and grid investment.
The flow of revenue into profit has been volatile over the last several years. Sales recovered after the 2023 downturn, operating earnings improved sharply in 2025, and net income turned positive again, but interest expense has remained a notable drag. That pattern fits a cyclical miner with meaningful financial leverage: operating recovery can be strong, yet gains do not fully reach the bottom line when borrowing costs are elevated.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Industrial Metals & Mining | |
| Market Cap ⓘ | $1.67B | |
| Beta ⓘ | 0.92 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 6.05 | 16.90 |
| P/B Ratio ⓘ | 1.87 | 1.65 |
| FCF Yield ⓘ | 10.35% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | 26.18% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 28.20% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 3.37% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 22.62% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -15.22% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 3.52% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 60.76% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -10.05% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 19.72% | 9.26% |
| ROA (Latest) ⓘ | 5.26% | 4.91% |
| ROIC (5Y Median) ⓘ | 6.91% | 7.70% |
| ROA (5Y Median) ⓘ | 1.01% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 1.77 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.66 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 1.23 | 0.95 |
| Net Debt / Assets ⓘ | 27.42% | 13.69% |
| EBITDA / Interest ⓘ | 4.67 | 12.34 |
| Operating Margin (Latest) ⓘ | 24.30% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 12.53% | 11.80% |
| Debt to Equity (Latest) ⓘ | 154.12% | 40.56% |
| Profit Margin (Latest) ⓘ | 8.02% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $173.22M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +139.86% | +68.89% |
| 12M Return (excl. last month) ⓘ | +154.83% | +30.21% |
| 6M Return ⓘ | +7.04% | -4.16% |
| Price vs. 200-Day MA ⓘ | -1.25% | -1.27% |
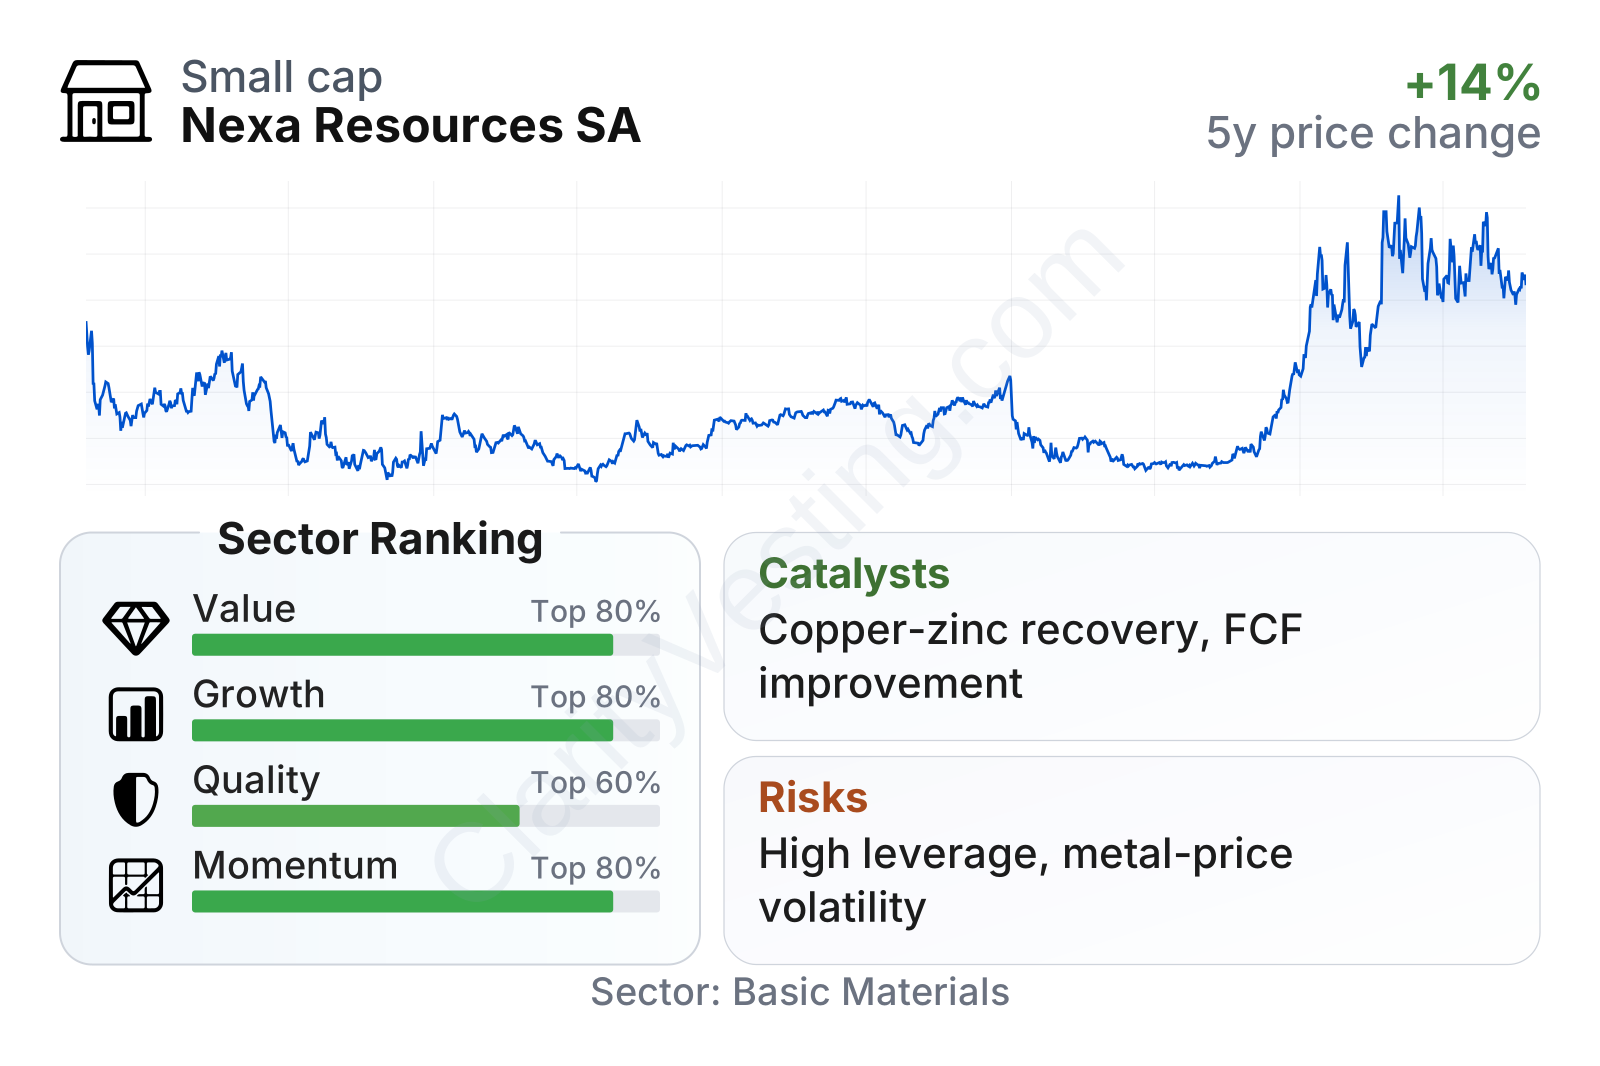
Nexa is a mid-sized mining company with a stock price history that shows how cyclical this business can be. After several weak years, the shares rebounded strongly into 2026. The latest metrics point to a company that screens well on valuation, with earnings and cash-flow multiples well below sector norms, while growth and momentum also rank well relative to peers. Quality is more mixed: current profitability is solid, but leverage remains clearly heavier than the industry median.
Growth
Nexa operates in a sector with credible long-term demand support, even if year-to-year performance can be volatile. Zinc is a mature industrial metal, but it remains essential for corrosion protection in steel, which ties demand to infrastructure, construction, transportation, and industrial maintenance. Copper adds a stronger structural growth angle because power grids, renewable energy equipment, electric vehicles, and broader electrification all require large amounts of conductive metal.
The company’s strategy is logical for this environment. It combines mining assets, which give direct exposure to metal prices, with smelting assets, which can add value through processing and commercial flexibility. Management has also spent the last few years emphasizing operational efficiency, portfolio discipline, and capital allocation after a difficult period marked by weaker profitability and pressure on the balance sheet.
Recent top-line trends suggest the business has moved out of its low point. Revenue fell sharply in 2023, then recovered through 2024 and 2025, and accelerated further in the latest period. Current year-over-year growth is running well above the sector median, which indicates that the recovery is not just a broad industry effect but also reflects company-specific improvement in volumes, pricing mix, or both.
Cash generation is another important change. Free cash flow was negative for an extended stretch, then turned positive and improved materially. For a miner, that matters because strong accounting profits are less convincing when they do not translate into cash. Nexa’s recent shift back to positive free cash flow supports the idea that the operating rebound is becoming more tangible.
One of the clearest catalysts is any sustained improvement in zinc and copper market conditions. Better metal prices can lift earnings quickly because much of the cost base is already in place. In addition, steadier operating performance at core assets such as Cerro Lindo and the company’s Brazilian operations could further support output and margins. Public company updates in 2026 have continued to highlight production discipline, cost attention, and debt management as central priorities, which is consistent with the financial profile shown today.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


