Stock Analysis · New Pacific Metals Corp (NEWP)
Overview
New Pacific Metals Corp is a mineral exploration and development company focused on silver projects in Bolivia. Unlike an operating miner, it is not currently producing metal at commercial scale. Its business is to advance mineral properties through drilling, engineering studies, permitting, community work, and project planning with the goal of eventually building mines or attracting partners for development.
The company’s asset base is concentrated in Bolivia, with its best-known projects including Silver Sand and Carangas. Silver Sand has been the flagship project for several years, while Carangas has added another potential development path with exposure not only to silver but also to zinc and lead by-products. New Pacific is part of the broader precious-metals development space, where valuations are often driven more by resource quality, project economics, permitting progress, and metal-price expectations than by current sales.
Because New Pacific is still in the development stage, its revenue profile is unusual compared with established mining companies.
- Operating revenue: 0% of the core business at this stage. The company has reported no meaningful revenue from metal production because it does not yet operate a producing mine.
- Other minor income: limited non-core items such as interest or similar financial income may appear in financial statements from cash balances, but these are not the economic engine of the business.
- Future potential revenue mix: if Silver Sand and later Carangas move into production, revenue would likely be driven primarily by silver, with additional contributions from zinc and lead at Carangas if developed.
The financial profile reflects this stage clearly: no operating sales, recurring administrative and exploration spending, and ongoing losses as the company advances its projects. Over the last several reporting periods, expenses have generally trended lower than the peak levels seen earlier in the development cycle, which suggests some cost discipline, but the company remains dependent on its balance sheet and capital markets rather than self-funded operations.
The visual summary shows a business with no operating revenue yet and a cost structure dominated by overhead and project-related spending. Losses have narrowed from earlier years, but the core point remains unchanged: value creation depends on turning mineral resources into economically viable, permitted, financeable mines.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Silver | |
| Market Cap ⓘ | $1.16B | |
| Beta ⓘ | 2.61 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.90 |
| P/B Ratio ⓘ | 6.79 | 1.65 |
| FCF Yield ⓘ | -0.63% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | -0.50% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | N/A | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -3.77% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 5.18% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -34.44% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -3.01% | 9.26% |
| ROA (Latest) ⓘ | -2.82% | 4.91% |
| ROIC (5Y Median) ⓘ | -3.38% | 7.70% |
| ROA (5Y Median) ⓘ | -4.66% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | -24.03% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.34 |
| Operating Margin (Latest) ⓘ | N/A | 13.20% |
| Operating Margin (5Y Median) ⓘ | N/A | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | N/A | 6.43% |
| Free Cash Flow (Latest) ⓘ | -$7.32M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +228.09% | +68.89% |
| 12M Return (excl. last month) ⓘ | +170.51% | +30.21% |
| 6M Return ⓘ | +11.03% | -4.16% |
| Price vs. 200-Day MA ⓘ | +18.38% | -1.27% |
New Pacific is a mid-sized silver developer by market value, but its trading behavior is much more volatile than the average materials stock, with a beta above 2.6. That means the share price has tended to move sharply, both with changing silver sentiment and with project-specific news.
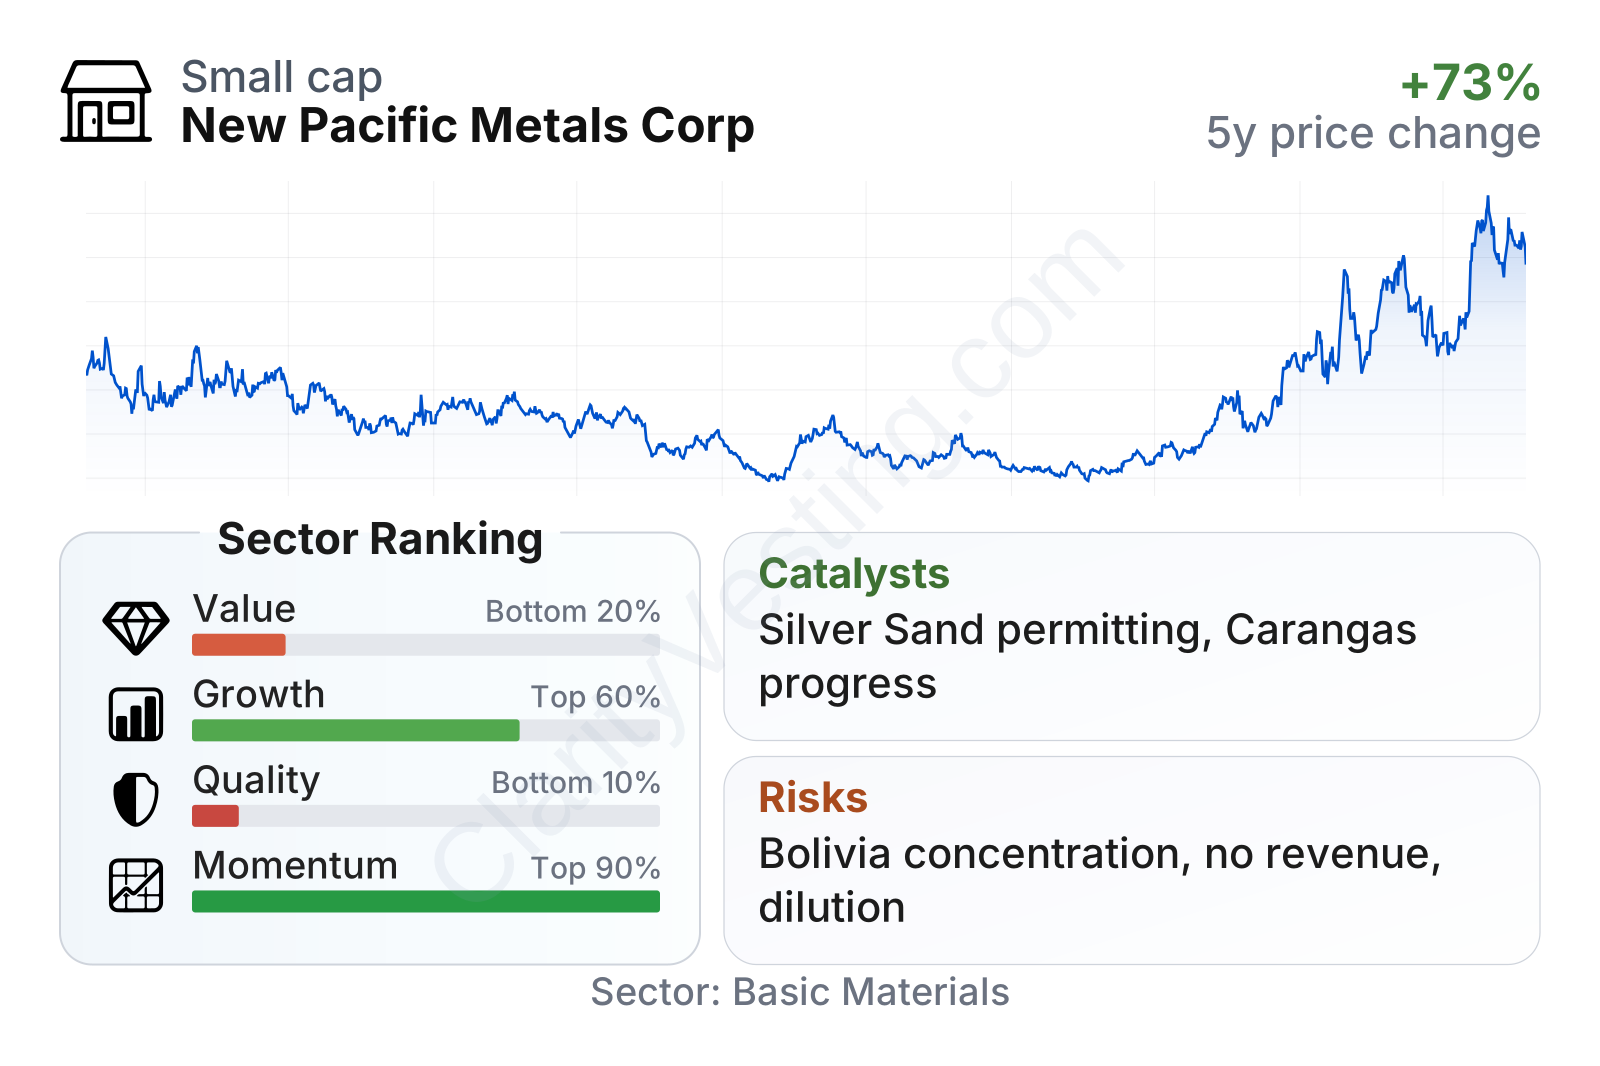
The factor profile is mixed. Momentum is very strong, with gains over the past 6 months, 12 months, and 3 years far ahead of the sector median. By contrast, value and quality metrics rank weakly because the company has no producing assets yet, negative free cash flow, and negative returns on capital and assets. Growth metrics look less weak than quality mainly because book value has increased over time and losses have not deteriorated as badly as some peers, but there is still no revenue growth to point to.
The high price-to-book ratio versus the sector median shows the market is assigning substantial value to future project potential rather than current earnings power. That can be justified in mining development cycles when an asset is seen as strategically important, but it also leaves less room for disappointment if permitting, financing, or engineering milestones slip.
Growth
New Pacific operates in a sector with long-term relevance. Silver benefits from two demand pillars: its role as a precious metal and its industrial use, especially in solar panels, electronics, and electrical applications. That gives the company exposure to both investor interest in precious metals and structural demand tied to electrification and energy transition trends. For a developer without production, this backdrop matters because stronger long-term silver demand can improve project economics and financing attractiveness.
The company’s strategy is straightforward and logical for its stage: advance one flagship silver project while building optionality through a second deposit. Silver Sand remains the central asset. Earlier technical work outlined a large open-pit silver project, and subsequent updates have focused on de-risking the asset through engineering and permitting steps. Carangas adds another layer of growth because it broadens the development pipeline and introduces base-metal by-products that could support economics if the project continues to progress well.
One of the clearest catalysts is any move that reduces uncertainty around permitting and project readiness in Bolivia. In mining development, a feasibility update, environmental approval, mining license progress, or a financing-related strategic partnership can all change how the market views a project. For New Pacific specifically, the biggest future value inflection would come from demonstrating that Silver Sand can move from a studied deposit into a realistically buildable mine.
Cash generation is still negative, which is normal for a company in this phase, but the cash burn has improved substantially from the worst period a few years ago. Recent free cash outflows have been materially lower than the 2023 peak, suggesting project spending has become more measured. Even so, the business has not yet reached the point where internal cash flow can fund growth; progress still depends on available cash and access to outside capital if development accelerates.
Recent company disclosures have also kept attention on resource advancement and project studies rather than commercial operations. That is important context: the opportunity is tied to what the assets could become over time, not to current production performance. In a favorable silver market, advanced developers can gain attention quickly because they offer leverage to higher metal prices before mines are built.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


