Stock Analysis · National Energy Services Reunited Corp (NESR)
Overview
National Energy Services Reunited Corp is an oilfield services company focused mainly on the Middle East and North Africa. In simple terms, it helps oil and gas producers drill wells, evaluate underground reservoirs, complete wells so they can start producing, and maintain production over time. The company does not usually own the oil or gas itself. Instead, it earns money by providing equipment, technical services, and integrated support to national oil companies and other upstream operators.
NESR presents itself as a regional specialist with a broad service offering across countries such as Saudi Arabia, Oman, the United Arab Emirates, Kuwait, Iraq, Algeria, and Egypt. That regional concentration matters because many of the company’s customers are large state-backed producers with long investment cycles and multi-year field development plans. This can make demand more durable than in some shorter-cycle North American markets, but it also ties the business closely to spending decisions by a limited set of major customers.
Based on the company’s filings, revenue is primarily organized into two main reporting segments:
- Production Services — approximately 55% to 65% of revenue in recent years. This area includes hydraulic fracturing, coiled tubing, stimulation, cementing, nitrogen services, and other services used to complete wells and support production.
- Drilling and Evaluation Services — approximately 35% to 45% of revenue in recent years. This includes drilling tools, directional drilling, drilling fluids, wireline, logging, and reservoir evaluation services used before and during drilling.
That mix gives NESR exposure both to new well activity and to the work required after a well is drilled. It also means the business is not dependent on a single service line. Over the last several years, the company’s revenue base has expanded meaningfully while profitability improved from losses in 2021 and 2022 to positive net income in 2023 through 2025. The overall financial flow also shows a business that moved from weak gross profitability to a healthier operating structure, even if margins remain below many larger peers.
The long-term trend is encouraging: revenue climbed from under $0.9 billion in 2021 to above $1.3 billion by 2025, while operating income turned solidly positive. The softer point is that 2025 earnings were lower than 2024 despite slightly higher revenue, showing that execution and margins still matter as much as growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Equipment & Services | |
| Market Cap ⓘ | $2.67B | |
| Beta ⓘ | 0.40 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 28.79 | 14.47 |
| P/B Ratio ⓘ | 2.52 | 1.70 |
| FCF Yield ⓘ | 5.85% | 8.66% |
| Dividend Yield ⓘ | N/A | 3.77% |
| EBIT / EV ⓘ | 4.26% | 7.46% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 59.10% | 27.35% |
| RPS Growth (5Y CAGR) ⓘ | 8.53% | 6.75% |
| EPS Growth (5Y CAGR) ⓘ | -3.01% | -15.45% |
| BVPS Growth (5Y CAGR) ⓘ | 2.01% | 5.85% |
| Margin Growth (5Y Trend) ⓘ | 12.20% | 0.75% |
| FCF Growth (5Y CAGR) ⓘ | 55.48% | 3.62% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 16.85% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 9.24% | 11.33% |
| ROA (Latest) ⓘ | 4.78% | 6.03% |
| ROIC (5Y Median) ⓘ | 2.37% | 10.16% |
| ROA (5Y Median) ⓘ | 0.69% | 5.34% |
| Net Debt / EBIT (Latest) ⓘ | 0.85 | 1.62 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.97 | 1.91 |
| Net Debt / EBITDA (Latest) ⓘ | 0.43 | 1.06 |
| Net Debt / Assets ⓘ | 5.92% | 17.29% |
| EBITDA / Interest ⓘ | 9.78 | 9.64 |
| Operating Margin (Latest) ⓘ | 9.04% | 16.32% |
| Operating Margin (5Y Median) ⓘ | 6.60% | 19.53% |
| Debt to Equity (Latest) ⓘ | 28.70% | 54.41% |
| Profit Margin (Latest) ⓘ | 5.77% | 8.79% |
| Free Cash Flow (Latest) ⓘ | $156.33M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +343.73% | +62.93% |
| 12M Return (excl. last month) ⓘ | +275.11% | +44.83% |
| 6M Return ⓘ | +18.63% | -1.62% |
| Price vs. 200-Day MA ⓘ | +2.17% | +5.18% |
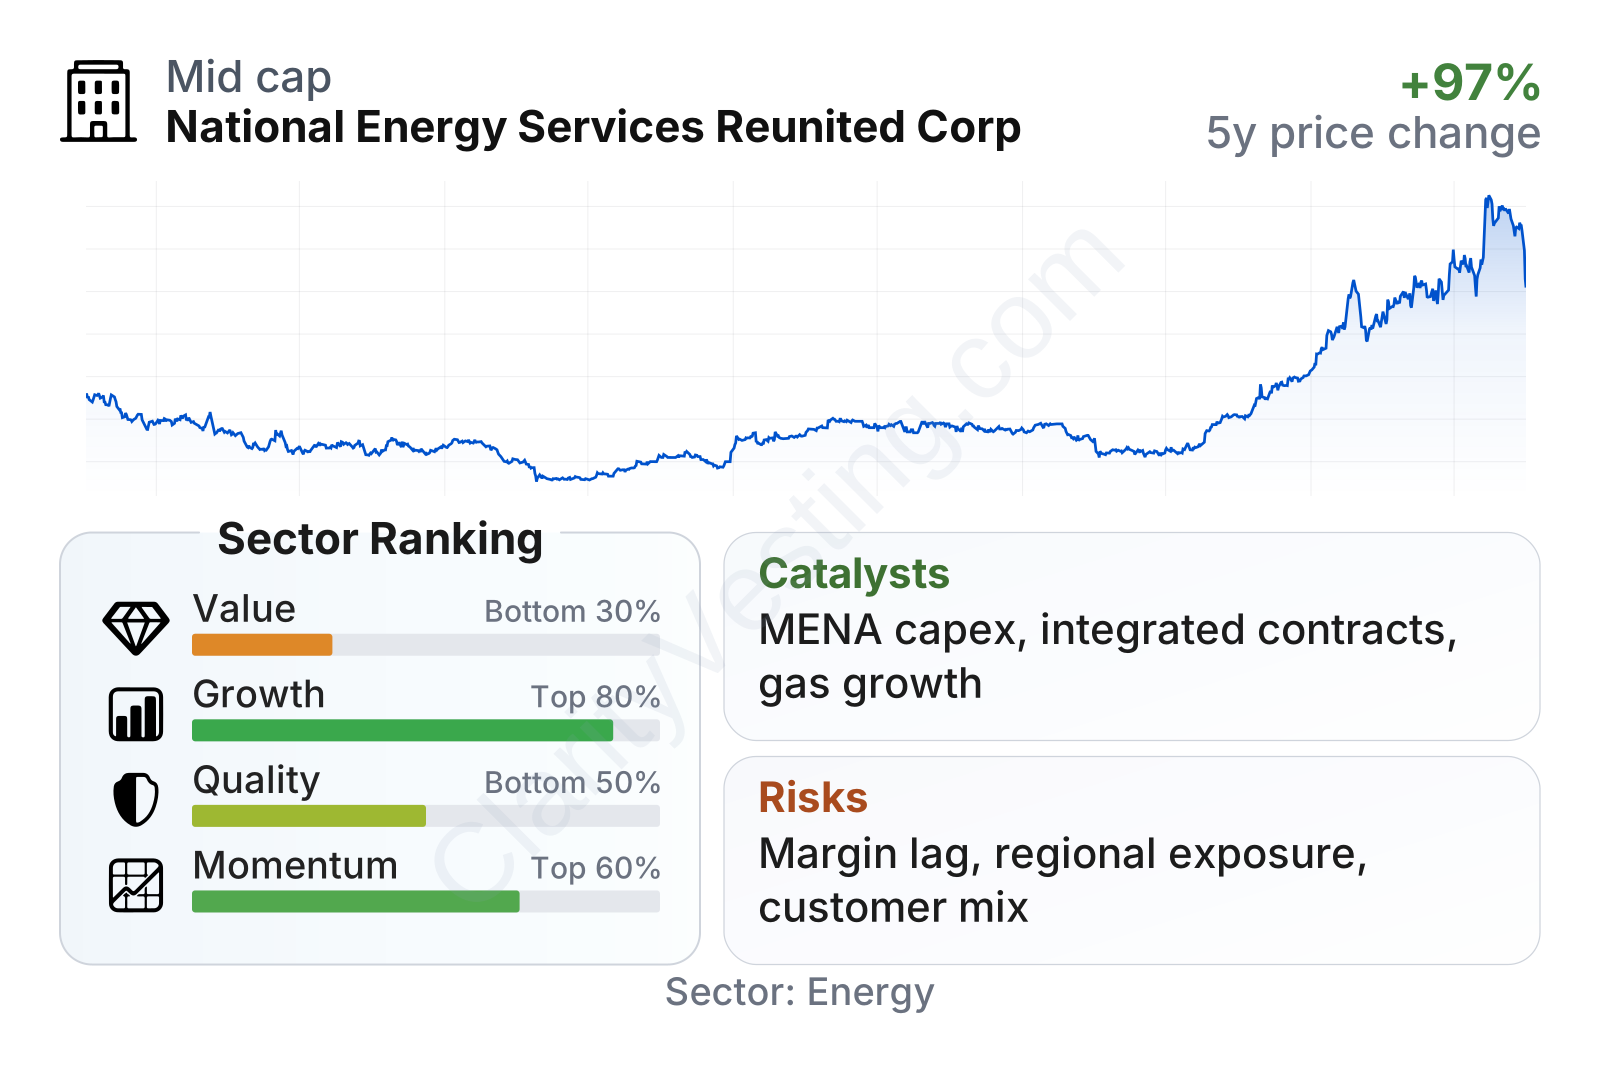
NESR is now a mid-sized energy services company with a market value around the low single-digit billions and a relatively low beta, which suggests the stock has recently been less volatile than many energy names. The factor profile is mixed. Growth and momentum rank above much of the sector, helped by strong recent revenue expansion and a large share price rebound. Value metrics look weaker, with the stock trading above sector medians on earnings and book value multiples while free cash flow yield and EBIT-to-enterprise-value sit below the sector midpoint. Quality is also mixed: leverage looks better than many peers, but returns on capital and margins still trail the broader oilfield services group.
Growth
The company operates in a part of the energy market that still has structural support. Despite the global push toward lower-carbon energy, oil and gas producers in the Middle East continue to invest heavily to maintain and expand output capacity. National oil companies in the region are among the world’s lowest-cost producers, and many are funding long-duration development programs in gas, offshore, unconventional resources, and enhanced recovery. That backdrop is generally favorable for service providers with established local operations.
NESR’s strategy also fits that environment. Rather than trying to compete everywhere, it focuses on the MENA region and builds a broad local service platform. The company has highlighted integrated service contracts, in-country manufacturing, digital tools, and newer technologies tied to efficiency and reservoir performance. This approach makes strategic sense because customers in the region increasingly prefer suppliers that can localize operations, meet domestic content requirements, and provide multiple services under one relationship.
Recent growth has accelerated sharply. Revenue growth moved from low double digits during much of 2024 to roughly 33% in the first quarter of 2026 and about 59% in the second quarter of 2026. That is far above the sector median and suggests either a step-up in activity, new contract wins, or a stronger contribution from specific service lines. It also indicates NESR is currently expanding faster than many direct peers.
Cash generation has been positive, which is important in this industry because fast growth can sometimes consume cash through working capital and equipment spending. Free cash flow has remained positive and recovered from a weaker 2025 level to a stronger level again in 2026. Over a five-year view, free cash flow growth has been exceptionally strong. That does not guarantee a straight path forward, but it shows the business is not growing only on paper.
Recent company communications have also pointed to technology partnerships, expansion in gas-related activity, and additional integrated project opportunities across the region. For NESR, the most important catalyst is not a single breakthrough product. It is the possibility of converting its regional footprint into more large, recurring contracts with national oil companies that continue to spend through the cycle. If that continues, the company could keep growing faster than the broader industry.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


