Stock Analysis · Nabors Industries Ltd (NBR)
Overview
Nabors Industries Ltd is an oilfield services company focused mainly on drilling. In simple terms, it provides the rigs, equipment, software, and related services that oil and gas producers use to drill wells on land and, to a smaller extent, offshore. The company operates across the United States, the Middle East, Latin America, and other international markets. Beyond basic rig rental, Nabors has been trying to move toward higher-value services such as drilling automation, digital tools, performance software, and power solutions for rigs.
The business is still centered on drilling activity, which means its results depend heavily on customer spending by oil and gas producers. Based on the company’s segment reporting in recent annual filings, revenue is mainly generated from the following sources:
- U.S. Drilling: approximately 35% to 40% of revenue. This includes land drilling rigs and related services for exploration and production companies in the United States.
- International Drilling: approximately 30% to 35% of revenue. This covers land drilling operations outside the U.S., especially in markets such as the Middle East and Latin America, where contracts can be longer and more stable.
- Drilling Solutions: approximately 15% to 20% of revenue. This segment includes automation technologies, software, directional drilling tools, and other products designed to improve drilling efficiency.
- Rig Technologies: approximately 5% to 10% of revenue. This business sells or upgrades rig equipment and components.
- Other operating activities, including energy transition-related and support services: generally a smaller contribution, usually below the main drilling segments.
This mix matters for long-term analysis because Nabors is no longer just a pure rig provider. It is trying to build a broader platform around drilling efficiency, rig modernization, and digital operations, which could make revenue less dependent on simple dayrates over time.
The long-term financial picture has improved from the deep losses seen earlier in the decade, but the business remains capital-intensive. Revenue recovered strongly from 2021 through 2023, softened in 2024, and then resumed moderate expansion. The earnings flow also shows how sensitive Nabors remains to costs, utilization, and interest expense: operating performance improved much faster than final net income.
Over the last several years, sales rose meaningfully from the post-downturn base, and operating income turned positive after earlier losses. However, interest costs have remained heavy, which helps explain why stronger operations have not always translated into consistently strong bottom-line profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 14, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Drilling | |
| Market Cap ⓘ | $1.26B | |
| Beta ⓘ | 1.08 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 6.20 | 13.07 |
| P/B Ratio ⓘ | 1.95 | 1.89 |
| FCF Yield ⓘ | 8.74% | 8.26% |
| Dividend Yield ⓘ | N/A | 3.50% |
| EBIT / EV ⓘ | 9.93% | 9.02% |
| PEG ⓘ | 2.90 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 6.60% | 26.55% |
| RPS Growth (5Y CAGR) ⓘ | -4.47% | 6.66% |
| EPS Growth (5Y CAGR) ⓘ | -45.01% | -6.30% |
| BVPS Growth (5Y CAGR) ⓘ | -29.56% | 5.85% |
| Margin Growth (5Y Trend) ⓘ | 34.14% | 0.61% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 3.10% |
| DPS Growth (5Y CAGR) ⓘ | -18.90% | 16.92% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 3.39% | 11.29% |
| ROA (Latest) ⓘ | -1.29% | 6.18% |
| ROIC (5Y Median) ⓘ | 3.27% | 10.35% |
| ROA (5Y Median) ⓘ | -3.60% | 5.46% |
| Net Debt / EBIT (Latest) ⓘ | 5.54 | 1.60 |
| Net Debt / EBIT (5Y Median) ⓘ | 9.93 | 1.82 |
| Net Debt / EBITDA (Latest) ⓘ | 1.69 | 0.97 |
| Net Debt / Assets ⓘ | 34.83% | 16.42% |
| EBITDA / Interest ⓘ | 5.11 | 9.71 |
| Operating Margin (Latest) ⓘ | 8.55% | 16.44% |
| Operating Margin (5Y Median) ⓘ | 6.14% | 20.55% |
| Debt to Equity (Latest) ⓘ | 357.43% | 49.13% |
| Profit Margin (Latest) ⓘ | -1.17% | 9.96% |
| Free Cash Flow (Latest) ⓘ | $110.45M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -8.12% | +56.67% |
| 12M Return (excl. last month) ⓘ | +95.06% | +46.57% |
| 6M Return ⓘ | -18.32% | -3.01% |
| Price vs. 200-Day MA ⓘ | -0.73% | +1.29% |
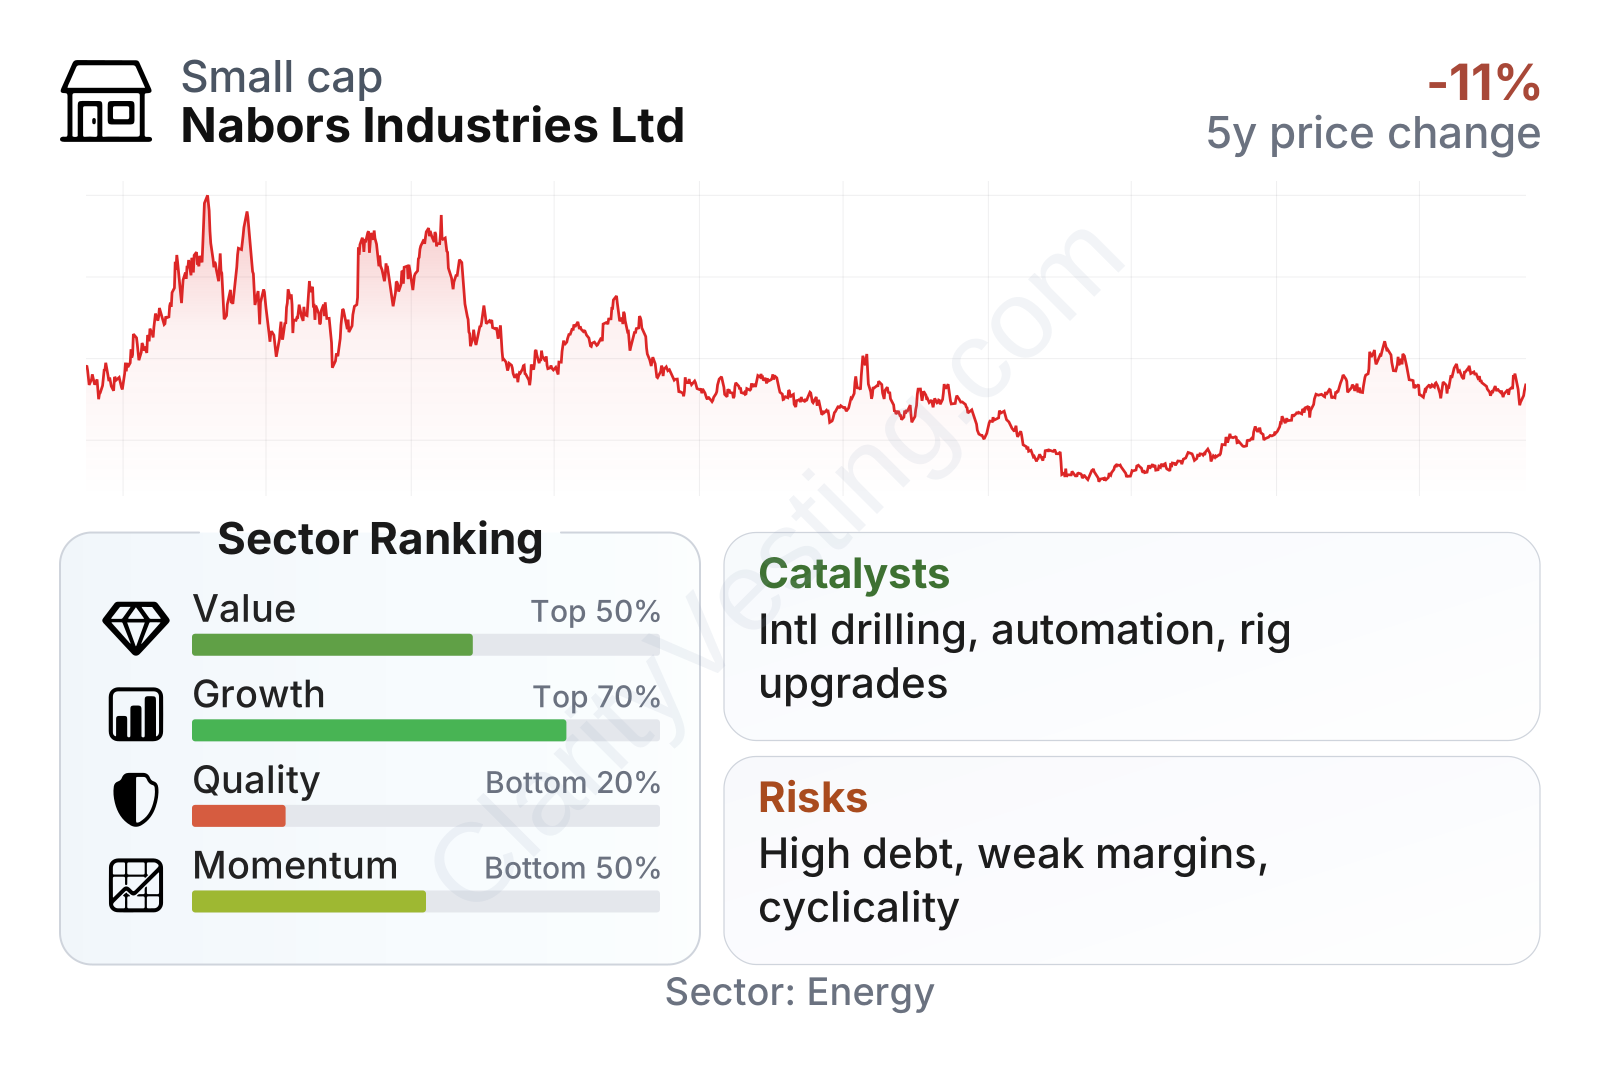
Nabors is a relatively small public company within the energy sector, and its share price history shows very high volatility. The stock climbed sharply during the drilling recovery, then fell hard, and later rebounded again, which reflects the cyclical nature of the business. In the latest factor snapshot, valuation looks mixed: the earnings multiple is low, but cash flow yield is weaker than the sector median and the price-to-book ratio is not especially cheap for a highly leveraged driller. Growth and momentum are uneven, while quality remains constrained by leverage and inconsistent profitability.
Growth
Oil and gas drilling is not a classic secular growth industry in the way cloud software or semiconductors are, but parts of Nabors’ market can still expand for years. The most attractive areas are international land drilling, automation, rig upgrades, and productivity tools that help customers lower well costs. This matters because producers are under pressure to improve efficiency, reduce downtime, and in some regions lower emissions intensity from operations. Nabors has positioned itself around those needs rather than relying only on adding more rigs.
The company’s strategy is broadly logical. It combines a large installed base of rigs with software, automation, and engineering services. That can deepen customer relationships and create more revenue per rig. Internationally, Nabors also benefits from exposure to national oil companies and longer-cycle projects, which can be steadier than short-cycle U.S. shale activity. Its technology partnerships and investments in automated drilling systems are meant to make rigs more productive and easier to operate, which could support better margins if adoption keeps rising.
Revenue growth has clearly cooled from the strong rebound phase seen in 2022 and early 2023. More recently, the pattern has been modest and uneven, with some quarters back in positive territory but at much lower rates than during the recovery surge. That suggests Nabors is now in a more mature part of the cycle, where future growth will likely depend more on mix improvement and international execution than on a broad industry upswing.
Cash generation has also been inconsistent. Free cash flow was solid at some points, turned negative, and then recovered toward break-even and positive territory again. For a long-term business case, that means growth is visible, but it has not yet become consistently self-funding at a level that would remove concern about balance-sheet pressure.
Recent company updates have pointed to continued progress in international markets, digital drilling solutions, and rig power technologies. Those areas represent the clearest catalysts because they can support better contract quality and differentiate Nabors from simpler rig contractors. If international customers continue ordering higher-spec rigs and related services, Nabors could gain from both revenue stability and better unit economics.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


