Stock Analysis · McEwen Mining Inc (MUX)
Overview
McEwen Mining Inc. is a small precious-metals mining company focused mainly on gold and silver, with an additional long-term growth platform in copper. Its producing assets are centered in the Americas, and the company has historically generated revenue by selling metal produced from its mines rather than through a diversified industrial business model. That makes the company highly exposed to metal prices, mine performance, and project execution.
The business is currently built around operating mines and advanced development projects. Based on the company’s recent public disclosures, the main revenue stream comes from its gold and silver operations, while its copper exposure is largely tied to the value of its stake in the Los Azules development project rather than current metal sales. In practical terms, McEwen Mining today is still mostly a precious-metals producer with a copper option embedded in the business.
Its revenue sources can be summarized as follows:
- Gold sales: the largest source of revenue, generated primarily from operating mines in Canada and Argentina.
- Silver sales: a smaller but meaningful contribution, usually sold alongside gold production at certain operations.
- Other mining-related revenue: limited contribution, which can include by-products, treatment adjustments, and other operational items.
- Copper project value: not a major current revenue source, but strategically important because Los Azules could become the company’s most significant asset if developed successfully.
For a simple long-term view, McEwen Mining is best understood as a miner with two layers: a current operating business that depends mainly on gold and silver output, and a future growth engine tied to copper development.
The company’s financial flow has improved from the heavy losses seen earlier in the decade, with revenue recovering from 2022 levels and operating performance turning positive more recently. Even so, the path has not been smooth, which is typical for smaller miners managing a mix of producing and developing assets.
The broad trend is encouraging: sales have moved up from the 2022 trough, and operating results improved substantially by 2025 after several weak years. That said, profitability has been uneven, showing how sensitive the business remains to mine execution, costs, and non-cash accounting swings.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Precious Metals & Mining | |
| Market Cap ⓘ | $1.01B | |
| Beta ⓘ | 1.26 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 13.40 | 16.90 |
| P/B Ratio ⓘ | 1.65 | 1.65 |
| FCF Yield ⓘ | 0.39% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | 4.28% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 26.80% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 5.05% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 6.28% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -9.01% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 37.60% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 11.38% | 9.26% |
| ROA (Latest) ⓘ | 9.27% | 4.91% |
| ROIC (5Y Median) ⓘ | -10.80% | 7.70% |
| ROA (5Y Median) ⓘ | -6.60% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 0.91 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.54 | 0.95 |
| Net Debt / Assets ⓘ | 4.99% | 13.69% |
| EBITDA / Interest ⓘ | 12.22 | 12.34 |
| Operating Margin (Latest) ⓘ | 21.95% | 13.20% |
| Operating Margin (5Y Median) ⓘ | -42.48% | 11.80% |
| Debt to Equity (Latest) ⓘ | 18.17% | 40.56% |
| Profit Margin (Latest) ⓘ | 32.46% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $3.89M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +99.74% | +68.89% |
| 12M Return (excl. last month) ⓘ | +34.59% | +30.21% |
| 6M Return ⓘ | -36.94% | -4.16% |
| Price vs. 200-Day MA ⓘ | -26.05% | -1.27% |
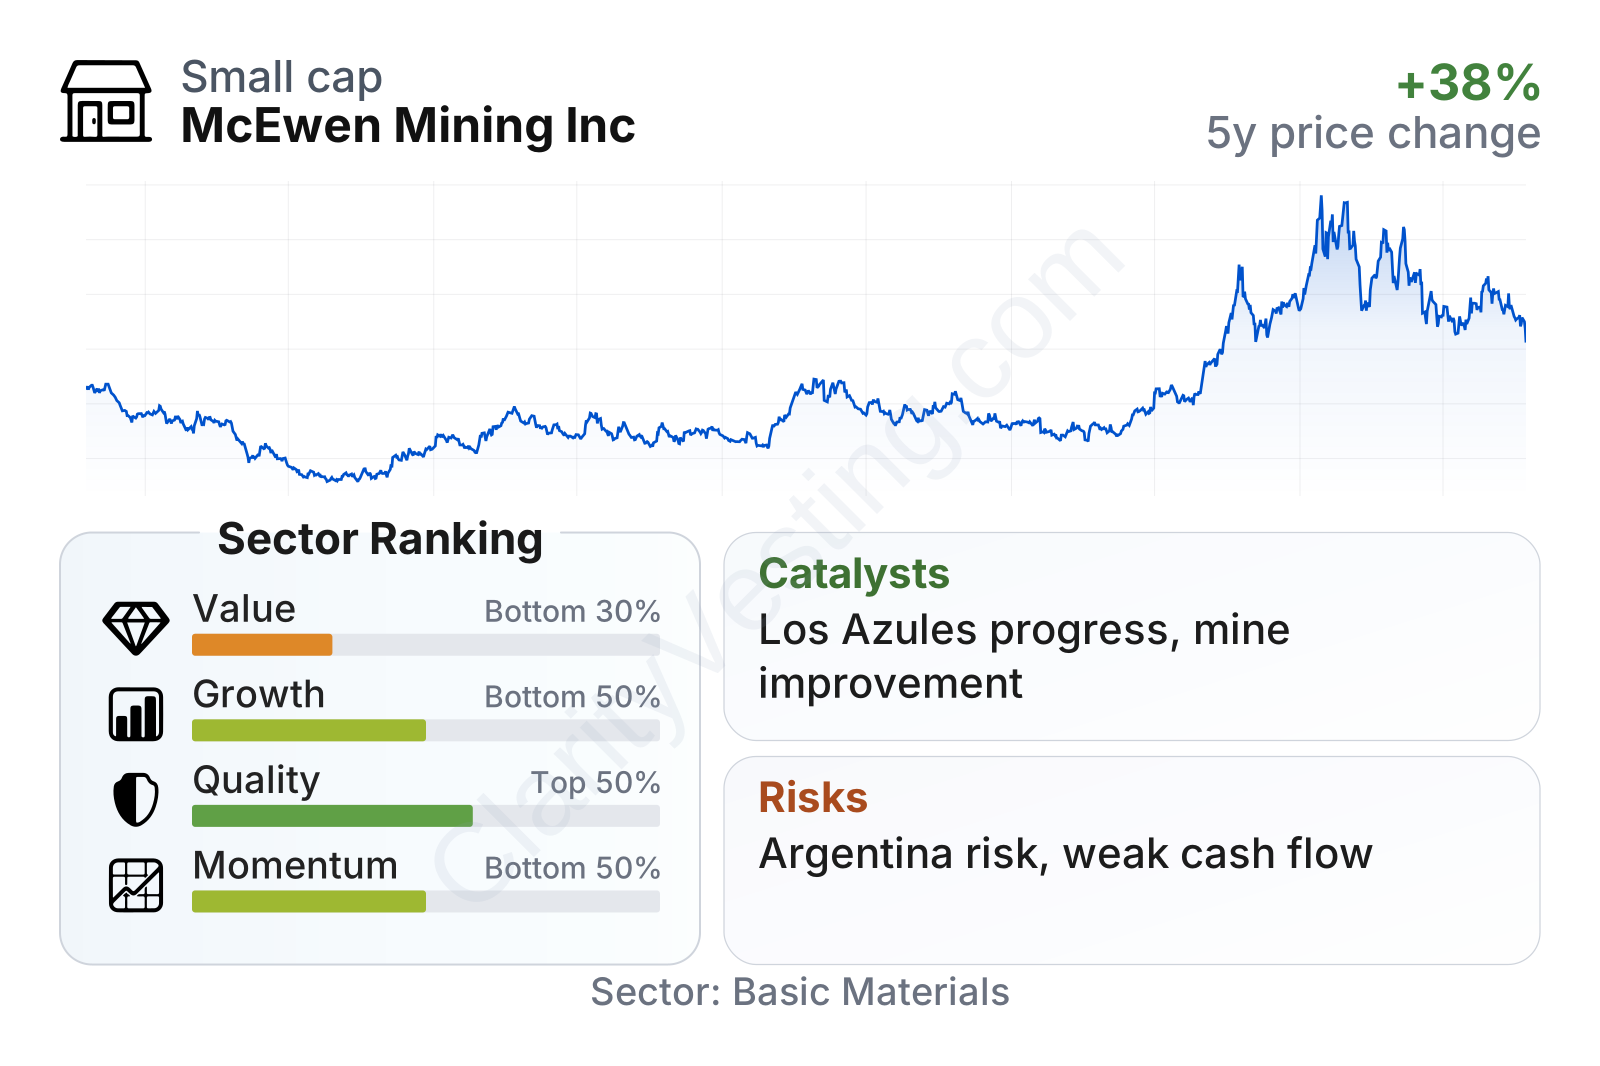
McEwen Mining sits in the small-cap range, which usually means higher upside potential but also higher volatility. The share price has risen strongly over the last three years, although the more recent pattern shows a meaningful pullback from earlier 2026 highs. That fits the company’s above-market volatility profile.
The metrics show a mixed picture. Recent profitability and returns on capital look better than many peers, and leverage remains relatively modest, with debt to equity around 18% versus a sector median above 31%. At the same time, valuation is not obviously cheap on cash-generation measures, because free cash flow remains thin and EBIT relative to enterprise value is still below the sector median. In short, operating quality has improved faster than cash conversion.
Growth
McEwen Mining operates in sectors with durable long-term relevance. Gold remains important as a store-of-value asset and a hedge in uncertain macroeconomic periods, while copper is tied to electrification, grid expansion, electric vehicles, and industrial infrastructure. That gives the company exposure to both defensive and growth-oriented commodity themes.
The company’s strategy makes sense on paper. It is trying to improve existing precious-metals operations while keeping significant upside through Los Azules, one of the better-known undeveloped copper projects in Argentina. If management can continue stabilizing mine performance and advance copper development without excessive balance-sheet strain, the business could shift from being viewed as a smaller gold miner to a broader metals platform with a more valuable development pipeline.
Revenue growth has been volatile, which is common in mining, but the most recent periods show a rebound. The latest year-over-year growth rate is well above the sector median, suggesting that operations and realized pricing have improved from the weaker phases of the cycle. The challenge is that this progress has not followed a straight line, so consistency still needs to be proven.
Cash generation remains the weaker part of the growth profile. Free cash flow has stayed negative across the recent trailing twelve-month periods shown, although the losses have narrowed materially. That matters because miners ultimately need production growth to convert into durable cash, not only accounting profits or temporary margin improvements.
A major catalyst is the continued advancement of Los Azules. Public company materials have highlighted permitting, technical work, and financing-related progress around this copper project. In a market increasingly focused on future copper supply, any step that de-risks timeline, economics, infrastructure, or strategic partnerships can have an outsized impact on how the broader company is valued.
Another important opportunity is operational improvement at the producing mines. For a company of this size, relatively small gains in grades, recoveries, throughput, or cost control can noticeably change earnings and sentiment. That creates room for upside if execution remains disciplined.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


