Stock Analysis · MasTec Inc (MTZ)
Overview
MasTec Inc is a large specialty infrastructure contractor. In simple terms, it helps build and maintain the physical systems that keep power, communications, energy, and transportation networks running. Its work includes installing electric transmission lines, building renewable energy facilities, expanding wireless and fiber networks, constructing pipelines and related energy infrastructure, and performing heavy civil work.
The company operates through several business segments, and its revenue mix can shift from year to year depending on project timing. Based on its latest annual reporting, the main sources of revenue are approximately:
- Communications: about 30% to 35% of revenue. This includes wireless network construction, fiber deployment, wireline services, and related maintenance work for telecom and broadband customers.
- Clean Energy and Infrastructure: about 25% to 30%. This segment includes renewable energy construction, power delivery work, transmission and distribution projects, and other electrical infrastructure.
- Power Delivery: about 15% to 20%. This covers electric utility work such as transmission lines, substations, and distribution network projects.
- Pipeline Infrastructure: about 10% to 15%. This includes natural gas pipelines, compressor stations, and related midstream energy facilities.
- Other Oil and Gas: about 10% to 15%. This generally includes activities tied to energy gathering systems and other traditional energy infrastructure.
- Heavy Civil: usually a smaller share than the segments above. This includes roads, bridges, rail, and other transportation-related construction.
This mix matters because MasTec is not a one-product company. It is exposed to several long-term infrastructure themes at once: electric grid expansion, data traffic growth, utility modernization, and energy network buildouts. At the same time, that diversification comes with uneven margins because some project categories are more profitable than others.
The financial flow over the last several years shows a business that has grown its sales base materially, but profitability has been volatile. Revenue moved from roughly $8 billion in 2021 to more than $14 billion in 2025, while operating income and net income swung sharply along the way. That pattern suggests MasTec has real scale, but project execution and cost control remain central to understanding the business.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Engineering & Construction | |
| Market Cap ⓘ | $16.55B | |
| Beta ⓘ | 1.84 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 32.98 | 22.10 |
| P/B Ratio ⓘ | 4.57 | 1.97 |
| FCF Yield ⓘ | 1.48% | 6.38% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 3.54% | 4.79% |
| PEG ⓘ | 0.66 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 23.40% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 14.01% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | 3.48% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 4.18% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -1.27% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | -17.71% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.85% | 10.84% |
| ROA (Latest) ⓘ | 4.88% | 5.41% |
| ROIC (5Y Median) ⓘ | 6.47% | 9.38% |
| ROA (5Y Median) ⓘ | 1.77% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 3.43 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 5.02 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 2.22 | 1.39 |
| Net Debt / Assets ⓘ | 26.72% | 19.28% |
| EBITDA / Interest ⓘ | 7.26 | 9.58 |
| Operating Margin (Latest) ⓘ | 5.29% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 3.61% | 10.29% |
| Debt to Equity (Latest) ⓘ | 93.05% | 65.48% |
| Profit Margin (Latest) ⓘ | 3.07% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $244.80M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +204.84% | +61.68% |
| 12M Return (excl. last month) ⓘ | +20.00% | +12.58% |
| 6M Return ⓘ | -46.85% | 0.00% |
| Price vs. 200-Day MA ⓘ | -36.25% | +0.02% |
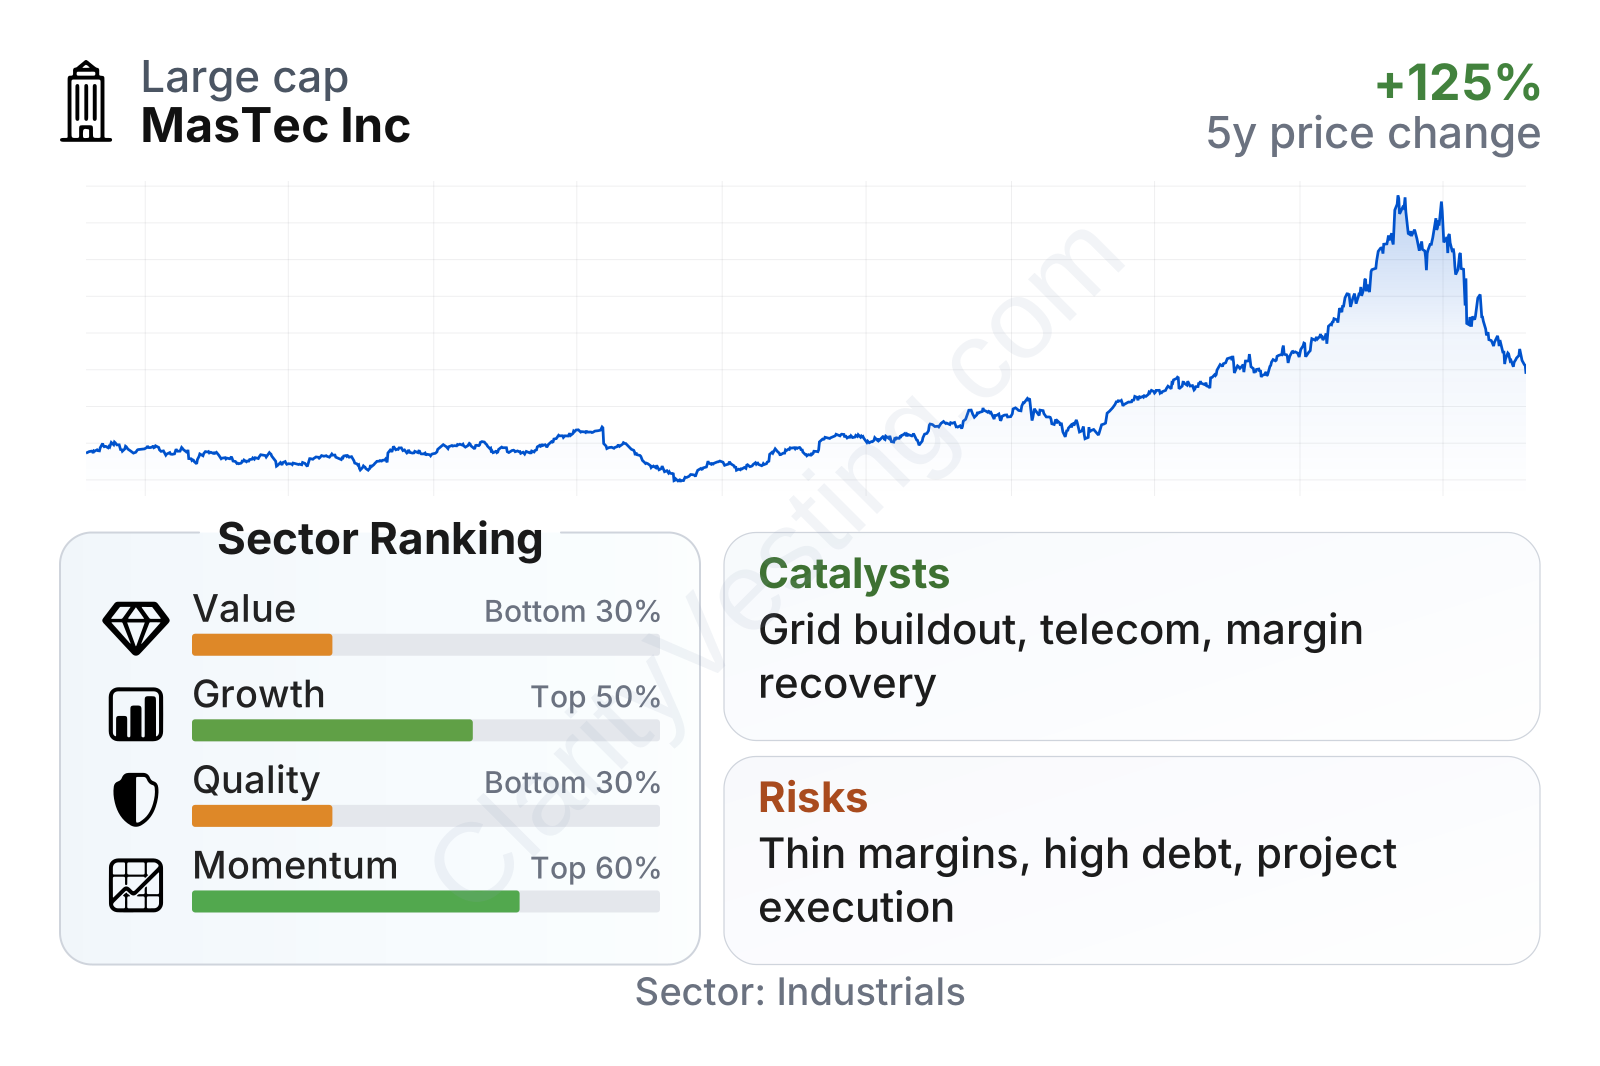
MasTec is a large-cap infrastructure contractor with a stock that has been much more volatile than the broader market, reflected in a beta above 1.8. On growth, it stands above the sector median, with recent revenue expansion clearly stronger than many industrial peers. On quality and value, however, it looks weaker: margins remain below the sector median, leverage is higher than average, and valuation multiples are elevated. Momentum is mixed, with strong multi-year share performance but a much weaker recent six-month trend.
Growth
MasTec operates in sectors with solid long-term demand. Electric grids need upgrades to handle rising power demand, renewable generation, and data center loads. Broadband and fiber deployment continue to require field construction. Utilities are spending on transmission and distribution reliability. Traditional energy infrastructure is no longer the whole picture for the company; the business is increasingly tied to broader infrastructure modernization.
The strategy also makes sense on a practical level. MasTec combines engineering, construction, installation, and maintenance capabilities across multiple infrastructure categories. That allows it to pursue very large projects and to serve customers that prefer contractors with national reach and specialized technical crews. Scale can matter in this industry because labor availability, equipment fleets, safety performance, and execution history all influence contract awards.
Recent revenue growth has been strong. The company’s year-over-year sales growth has accelerated again in the latest periods, reaching levels well above the sector median. Over five years, revenue per share growth has also outpaced the typical industrial company. That points to a business still winning work and benefiting from demand in its end markets.
Cash generation, though, has been less steady than revenue. Free cash flow has swung from strong positive years to much lower levels more recently. That is not unusual in construction-related businesses, where working capital can move sharply depending on project timing, billing milestones, and upfront costs. For a long-term view, the key point is that growth is real, but it has not translated into consistently smooth cash conversion.
Recent company updates have highlighted a large opportunity pipeline tied to power delivery, clean energy, communications, and heavy civil work. The broader backdrop remains supportive: utility capital spending, grid hardening, data center-related electrical demand, and network expansion all create room for sustained project activity. For MasTec, one of the strongest catalysts is its positioning at the intersection of energy and communications infrastructure rather than dependence on a single market.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


