Stock Analysis · Minerals Technologies Inc (MTX)
Overview
Minerals Technologies Inc. is a specialty minerals and materials company serving industrial customers around the world. Its products are used to improve manufacturing processes, reduce waste, control moisture, absorb contaminants, and enhance the performance of finished goods. In simple terms, the company takes mineral-based technologies and turns them into practical solutions for paper makers, steel and foundry operators, construction and environmental users, household and consumer-product manufacturers, and other industrial clients.
The business is organized into four main segments. Based on the company’s latest annual disclosures, revenue is spread across a fairly balanced portfolio rather than relying on a single product line.
- Consumer & Specialties: about 30% of revenue. This includes household and personal care ingredients, pet care absorbents, edible and pharmaceutical additives, and specialty mineral products used in consumer applications.
- Engineered Solutions: about 28% of revenue. This segment includes environmental and infrastructure products, building materials technologies, and services and products tied to remediation, construction, and specialized industrial uses.
- Performance Materials: about 25% of revenue. This business supplies bentonite and related materials for foundry, steel, and other industrial process applications.
- Specialty Minerals: about 17% of revenue. This segment focuses mainly on precipitated calcium carbonate and related mineral systems used in paper, packaging, and other applications where performance and cost efficiency matter.
This mix matters for long-term analysis because it gives Minerals Technologies exposure to both mature industrial markets and more specialized niches where technical know-how, formulation experience, and customer relationships can support pricing and recurring demand. Over the last several years, revenue has stayed around the low-$2 billion range, while profitability has been more cyclical, reflecting changing industrial demand, input costs, acquisition integration, and non-recurring charges.
The long-term pattern shows that sales have been relatively steady, but earnings have been less stable. After a strong rebound in 2024, 2025 was much weaker at the bottom line, even though gross profit remained meaningful. That suggests the main pressure came lower down the income statement rather than from a collapse in demand alone.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $1.99B | |
| Beta ⓘ | 1.12 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.90 |
| P/B Ratio ⓘ | 1.30 | 1.65 |
| FCF Yield ⓘ | 6.05% | 5.76% |
| Dividend Yield ⓘ | 0.75% | 2.13% |
| EBIT / EV ⓘ | -0.79% | 6.30% |
| PEG ⓘ | 2.22 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3.70% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 4.68% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -12.33% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 4.76% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -10.62% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -12.30% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 22.45% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -0.60% | 9.26% |
| ROA (Latest) ⓘ | -1.94% | 4.91% |
| ROIC (5Y Median) ⓘ | 6.26% | 7.70% |
| ROA (5Y Median) ⓘ | 3.61% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.28 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 8.11 | 0.95 |
| Net Debt / Assets ⓘ | 17.82% | 13.69% |
| EBITDA / Interest ⓘ | 1.40 | 12.34 |
| Operating Margin (Latest) ⓘ | -0.99% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 9.60% | 11.80% |
| Debt to Equity (Latest) ⓘ | 62.46% | 40.56% |
| Profit Margin (Latest) ⓘ | -3.13% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $120.30M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +32.11% | +68.89% |
| 12M Return (excl. last month) ⓘ | +7.45% | +30.21% |
| 6M Return ⓘ | -13.10% | -4.16% |
| Price vs. 200-Day MA ⓘ | -11.52% | -1.27% |
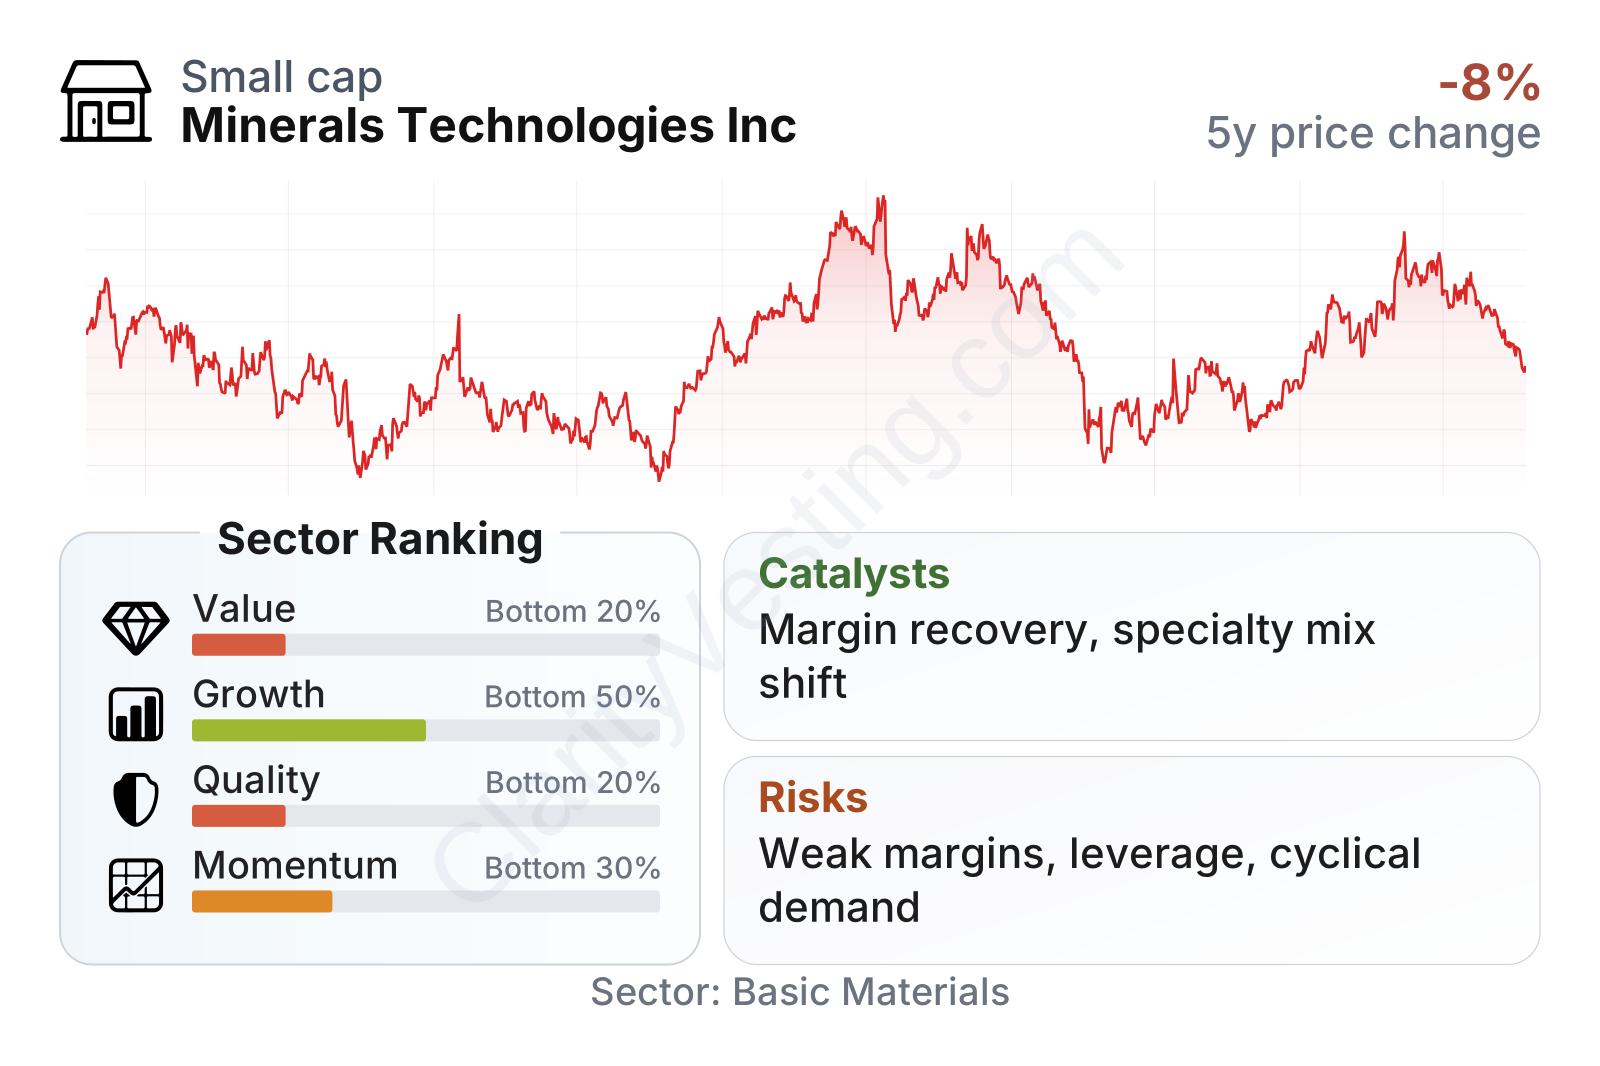
Minerals Technologies is a mid-sized company in the materials sector, with a share price that has been volatile but has largely recovered from its 2025 dip. The stock’s recent profile is mixed: valuation ratios based on book value and free cash flow are not stretched compared with sector norms, but profitability-based measures look weak because recent earnings quality has deteriorated. The company ranks in the lower part of the sector on value, quality, growth, and momentum, which reflects pressure on margins, leverage, and returns on capital more than a lack of scale or market presence.
Growth
Minerals Technologies operates in markets that are not fast-growing in the way software or biotechnology can be, but several of its end markets have durable long-term demand. Consumer absorbents, infrastructure-related solutions, environmental applications, and packaging-related mineral products are supported by ongoing basic needs rather than short-lived trends. That makes the company more of an industrial compounder candidate when execution is strong, rather than a pure high-growth name.
The company’s strategy has generally centered on technical product development, customer-specific systems, global plant networks, and acquisitions that broaden its specialty materials portfolio. This approach makes sense because many of its products are embedded in customer production processes. Once a mineral solution is qualified and integrated into a factory workflow, switching can be inconvenient and costly. That can create sticky commercial relationships, especially in specialty minerals and process-oriented applications.
Revenue growth has been uneven over the past few years. The company posted strong expansion in 2022, then moved through a softer period in 2024 and much of 2025 before returning to positive growth in early 2026. Recent year-over-year growth appears to have improved back into the low-to-mid single digits, with one stronger quarter above 10%, which suggests demand has stabilized after a difficult patch rather than entering a full acceleration phase.
Cash generation has held up better than earnings at several points in the cycle. Free cash flow has moved around sharply, but it remains positive on a trailing basis at roughly $120 million. That is an important support for the business because it gives the company room to keep investing, manage debt, and maintain its dividend even when reported earnings are pressured by charges or temporary weakness.
A notable recent opportunity is the company’s continued push toward higher-value specialty applications rather than commodity-style volume growth. Products tied to consumer, environmental, and engineered solutions tend to carry better strategic value than purely cyclical paper or heavy industrial exposure. If management continues shifting mix toward those categories, future results could become less volatile over time. The most significant near-term catalyst is therefore not a single breakthrough event, but a cleaner recovery in margins and volume across its specialty portfolio after a weak 2025 base.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


