Stock Analysis · Maravai Lifesciences Holdings Inc (MRVI)
Overview
Maravai LifeSciences Holdings is a biotechnology tools and life sciences supplier focused on products used to develop therapies, vaccines, and diagnostic tests. In simple terms, the company sells specialized ingredients and manufacturing inputs that other biotech and pharmaceutical companies need for research, clinical development, and commercial production. Maravai became especially visible during the COVID-19 period because some of its materials were used in mRNA vaccine programs, but the business is broader than pandemic demand.
The company mainly operates through nucleic acid production and biologics safety testing. Its most important products include highly modified nucleic acids such as CleanCap for mRNA manufacturing, custom DNA and RNA materials, and testing services that help biopharma customers check whether biological products are safe and free from contamination. The business model is largely business-to-business, with revenue tied to customer research activity, clinical programs, and manufacturing demand.
Based on the company’s recent annual reporting structure, revenue is mainly generated from the following sources:
- Nucleic Acid Production: approximately 75% to 85% of revenue in recent periods. This includes mRNA capping technology, custom RNA, plasmid DNA, oligonucleotides, and other nucleic acid-based inputs used in drug discovery, vaccines, and cell and gene therapy.
- Biologics Safety Testing: approximately 15% to 25% of revenue. This segment includes testing products and services used to detect contamination and support biologic drug development and manufacturing.
Revenue concentration has shifted since the pandemic peak. Earlier results were heavily supported by vaccine-related demand, while more recent performance reflects a reset toward a smaller base driven by research, biotech funding conditions, and non-COVID clinical programs. The long-term question is whether Maravai can rebuild growth from this normalized base rather than from one-time pandemic volume.
The financial flow over the last several years shows a sharp contrast between the exceptional profitability of 2021-2022 and the much weaker earnings profile that followed. Revenue fell dramatically after the pandemic surge, while operating costs remained too high for the smaller sales base, pushing margins into negative territory.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $2.80B | |
| Beta ⓘ | 0.54 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 25.42 |
| P/B Ratio ⓘ | 19.50 | 3.08 |
| FCF Yield ⓘ | -1.25% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | -9.34% | 0.56% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.50% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | -33.52% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | -15.45% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | -182.17% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | 29.06% | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -19.01% | 3.17% |
| ROA (Latest) ⓘ | -10.65% | 2.98% |
| ROIC (5Y Median) ⓘ | -14.77% | 4.56% |
| ROA (5Y Median) ⓘ | -6.31% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.04 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.00 |
| Net Debt / Assets ⓘ | 17.66% | 5.06% |
| EBITDA / Interest ⓘ | N/A | 9.55 |
| Operating Margin (Latest) ⓘ | -53.90% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 64.77% | 7.33% |
| Debt to Equity (Latest) ⓘ | 86.35% | 26.68% |
| Profit Margin (Latest) ⓘ | -37.07% | 3.34% |
| Free Cash Flow (Latest) ⓘ | -$35.11M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +6.16% | +51.61% |
| 12M Return (excl. last month) ⓘ | +171.27% | +19.90% |
| 6M Return ⓘ | +91.60% | +10.10% |
| Price vs. 200-Day MA ⓘ | +38.26% | +6.44% |
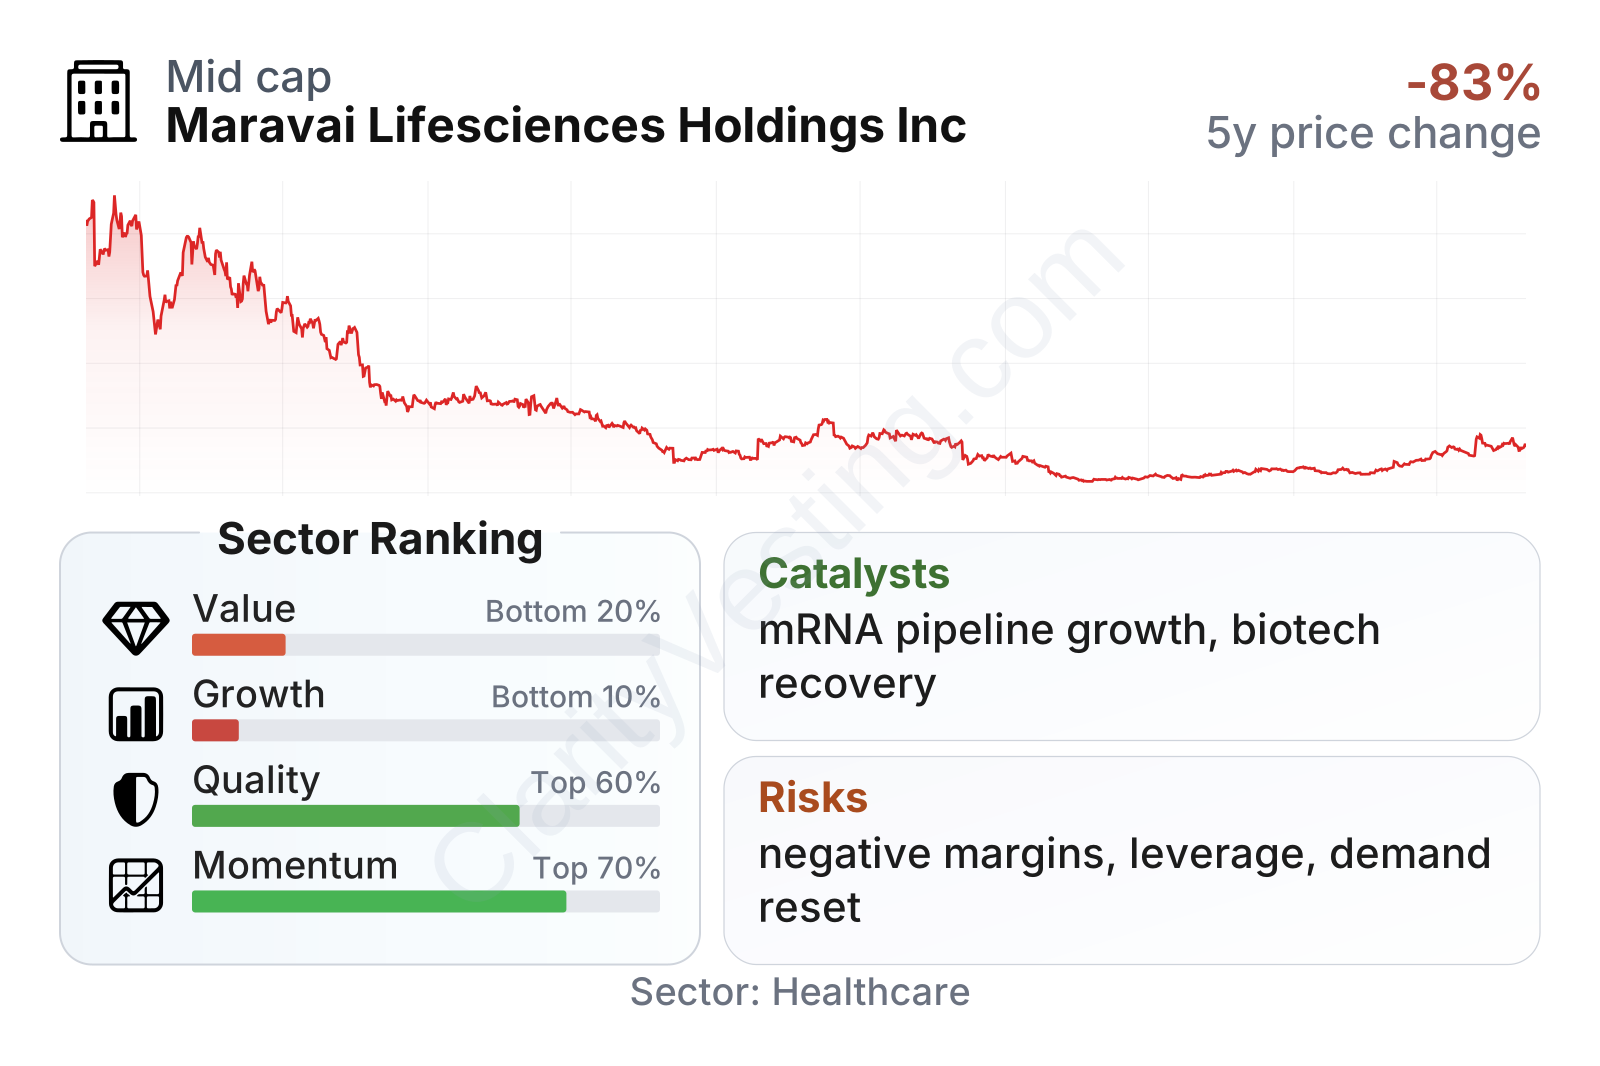
Maravai is now a mid-sized company by market value, and its share price history has been extremely volatile. The stock fell steeply from 2021 through early 2025, then rebounded strongly in the most recent year. That rebound has improved momentum, but the broader picture still reflects a business that is trying to recover from a major demand reset.
The metrics table points to a mixed profile. Recent share-price momentum is strong relative to much of the healthcare sector, but value and growth rankings remain weak. Profitability is still under pressure, free cash flow is negative, and the balance sheet carries more leverage than the sector median. In other words, the market has started to price in improvement, but the operating recovery is not yet fully visible in the fundamentals.
Growth
Maravai operates in areas with real long-term tailwinds. mRNA manufacturing, gene editing, cell therapy, and advanced biologics all require specialized nucleic acid materials and quality-control tools. These are not short-lived themes. If more RNA-based medicines and genetic therapies reach later-stage trials or commercialization, demand for high-quality inputs should expand over time.
The company’s strategy is logical for that market. It focuses on high-value components rather than trying to become a broad commodity supplier. Proprietary technologies such as CleanCap matter because customers often need consistent performance, regulatory support, and manufacturing reliability. That can create sticky customer relationships once a product is embedded in a development program.
Recent revenue trends suggest the business may be moving past the worst part of the post-pandemic collapse, even though the recovery is uneven. Year-over-year growth turned positive again in some recent quarters after an extended period of steep declines. That does not yet prove a durable upcycle, but it does indicate that comparisons are improving and that the business is no longer falling at the pace seen in 2023 and 2025.
Cash generation remains a key checkpoint. Free cash flow was strongly positive during the pandemic boom, then moved into negative territory as revenue contracted and margins weakened. A lasting recovery likely requires not just better sales growth, but also a clear return to healthier cash conversion.
One important catalyst is the broader normalization of biotech funding and clinical activity. When biotech companies raise capital and restart development programs, suppliers like Maravai usually benefit through higher order volumes. Another potential driver is the scaling of mRNA and next-generation nucleic acid medicines beyond infectious disease into oncology, rare disease, and personalized therapies. If that pipeline advances, Maravai’s core manufacturing inputs could see stronger demand.
Recent company communications have also emphasized operational restructuring, portfolio focus, and efforts to align costs with demand. If those actions improve efficiency while preserving the company’s technical position in nucleic acids, they could strengthen the earnings profile from a lower revenue base. The opportunity is meaningful, but it still depends on execution and on a broader recovery in customer activity.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


