Stock Analysis · MP Materials Corp (MP)
Overview
MP Materials Corp is a U.S. rare earth company centered on the Mountain Pass site in California, one of the largest rare earth deposits in the Western Hemisphere. Rare earth materials are used in permanent magnets, which are important for electric vehicles, wind turbines, robotics, electronics, and some defense applications. The company’s strategy is to move beyond mining and become a more complete domestic supplier, from raw material production to magnet manufacturing.
Today, the business is still mainly driven by rare earth concentrate sales, while newer activities such as separated rare earth products and downstream magnet production are intended to become more important over time. Based on recent company disclosures, revenue is largely tied to product sales from Mountain Pass, with pricing and volumes influenced by the rare earth market.
The main revenue sources can be summarized as follows:
- Rare earth concentrate sales: approximately 80% to 95% of recent revenue. This is the company’s traditional business, selling concentrate produced from ore mined and processed at Mountain Pass.
- Separated rare earth products and related sales: approximately 5% to 20% of recent revenue. This includes higher-value materials produced as MP expands processing capabilities, especially neodymium-praseodymium products used in magnet supply chains.
- Other revenue: currently minimal. This may include by-product or ancillary items, but it is not yet a major contributor compared with core rare earth sales.
That revenue mix remains in transition. The company is spending heavily to build a more integrated U.S. supply chain, so its current income statement does not yet fully reflect the end-state business model management is aiming for.
The long-term financial pattern shows how dependent MP has been on commodity pricing. Revenue and profitability surged in 2022, then weakened sharply as prices normalized and expansion costs increased. More recently, sales have started to recover, but margins remain far below earlier peak levels.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Industrial Metals & Mining | |
| Market Cap ⓘ | $6.95B | |
| Beta ⓘ | 1.99 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.92 |
| P/B Ratio ⓘ | 3.60 | 1.66 |
| FCF Yield ⓘ | -7.26% | 5.83% |
| Dividend Yield ⓘ | N/A | 2.07% |
| EBIT / EV ⓘ | -0.65% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 119.70% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | -6.80% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 27.55% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -89.39% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -1.32% | 9.59% |
| ROA (Latest) ⓘ | -1.61% | 4.92% |
| ROIC (5Y Median) ⓘ | 1.39% | 7.91% |
| ROA (5Y Median) ⓘ | 1.06% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.56 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 8.18 | 0.93 |
| Net Debt / Assets ⓘ | 13.56% | 13.69% |
| EBITDA / Interest ⓘ | 1.74 | 12.38 |
| Operating Margin (Latest) ⓘ | -17.31% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 15.12% | 11.82% |
| Debt to Equity (Latest) ⓘ | 47.75% | 40.30% |
| Profit Margin (Latest) ⓘ | -14.56% | 6.38% |
| Free Cash Flow (Latest) ⓘ | -$504.58M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +129.25% | +73.47% |
| 12M Return (excl. last month) ⓘ | -31.71% | +27.59% |
| 6M Return ⓘ | -39.93% | -4.02% |
| Price vs. 200-Day MA ⓘ | -29.51% | -0.65% |
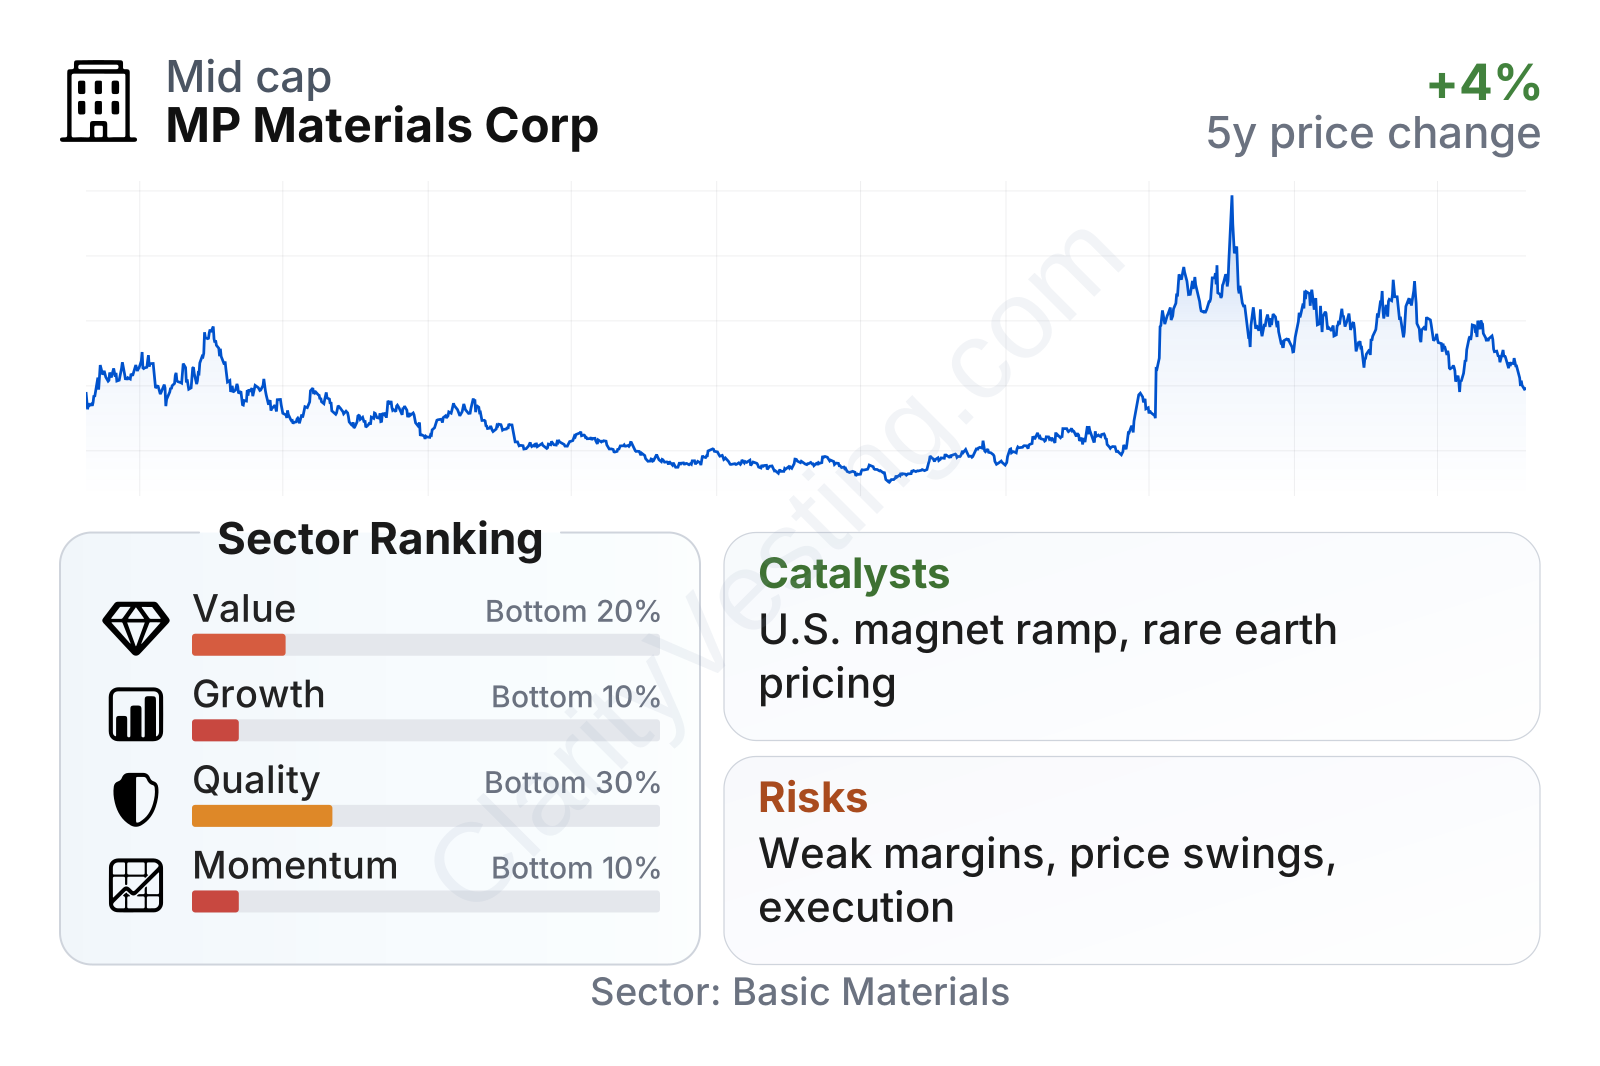
MP Materials is a mid-to-large-cap basic materials company with a stock that has been highly volatile, reflected in a beta close to 2. Across value, quality, growth, and momentum measures, the overall picture is mixed to weak. Revenue growth has recently rebounded strongly, but profitability, cash generation, and near-term market performance still lag most of the sector.
The share price history also highlights how cyclical and sentiment-driven the stock has been. After a powerful run earlier in the cycle, the stock fell materially and then rebounded sharply during 2025 before easing again in 2026. That pattern fits a business whose earnings outlook is closely linked to both rare earth prices and confidence in future downstream execution.
Growth
MP operates in a sector with clear long-term demand drivers. High-performance permanent magnets are increasingly important in electric vehicles, industrial automation, renewable energy equipment, and national-security-related applications. Governments in the U.S. and allied countries also want supply chains that are less dependent on China, which gives strategic value to domestic rare earth mining, processing, and magnet manufacturing capacity.
The company’s strategy broadly makes industrial sense. Mining alone can be profitable in strong pricing periods, but it leaves earnings exposed to volatile commodity markets. By adding separation, refining, and magnet production, MP is trying to move further into higher-value steps of the chain. If successful, this could improve revenue quality over time by reducing dependence on a single upstream product.
Recent sales growth has improved significantly after a difficult period in 2023 and 2024. That rebound suggests better volumes, pricing, or both. Even so, long-term growth has been uneven, and the business is still working through a transition rather than showing a smooth compounding pattern.
The main issue is that growth is currently consuming cash instead of producing it. Free cash flow has remained deeply negative as the company funds processing and manufacturing expansion. That is not unusual for an industrial buildout, but it means the growth plan still needs to prove that it can translate into durable returns.
A major catalyst is MP’s effort to establish domestic magnet production in the United States. If the company scales this successfully and secures large customer relationships, it could become much more than a mine operator. Public company communications have also emphasized support from U.S. industrial policy and the strategic importance of building a local rare earth ecosystem. In addition, any sustained improvement in neodymium-praseodymium pricing could have a meaningful effect on revenue and earnings power because the business remains highly exposed to those markets.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


