Stock Analysis · Monadelphous Group Ltd (MOPHY)
Overview
Monadelphous Group Ltd is an Australian engineering and maintenance contractor serving large industrial customers. Its work is concentrated in resources, energy, and infrastructure. In simple terms, the company helps build, maintain, and improve heavy industrial facilities such as mines, processing plants, energy assets, water systems, and transport infrastructure.
The business is organized around two main operating divisions, with a smaller contribution from related services and other activities. Based on the latest annual reporting, revenue is approximately split as follows:
- Engineering Construction: about 59% of revenue. This division delivers construction, fabrication, modularization, electrical and instrumentation work, and large project execution for mining, minerals processing, energy, and infrastructure customers.
- Maintenance and Industrial Services: about 41% of revenue. This includes shutdown services, ongoing maintenance, sustaining capital work, fixed plant maintenance, marine and industrial services, and asset support for existing operations.
That mix matters for long-term analysis. Construction work can lift revenue quickly when project activity rises, while maintenance tends to be steadier because customers must keep existing assets operating safely and efficiently. Geographically, the company is still primarily tied to Australia, although some projects and capabilities extend into nearby markets.
Another important point is the underlying economics of the business. Monadelphous operates on relatively thin margins, which is common in contracting, but it has recently translated higher activity levels into stronger profit and cash generation. Revenue has risen meaningfully since 2023, and earnings have improved even faster, showing that scale and execution have been working in its favor.
The recent progression shows a clear expansion in revenue, gross profit, operating income, and net income over the last several years. Costs remain high as a share of sales, which is normal for engineering and construction contractors, but the profit pool has widened rather than just growing in line with revenue. That suggests better project mix, improved execution, or both.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Engineering & Construction | |
| Market Cap ⓘ | $1.96B | |
| Beta ⓘ | 0.52 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 28.68 | 22.10 |
| P/B Ratio ⓘ | 3.48 | 1.97 |
| FCF Yield ⓘ | 14.37% | 6.38% |
| Dividend Yield ⓘ | 3.04% | 1.94% |
| EBIT / EV ⓘ | 11.92% | 4.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 19.20% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 9.33% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | 10.14% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 6.97% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | 1.20% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 18.45% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.84% |
| ROA (Latest) ⓘ | 19.99% | 5.41% |
| ROIC (5Y Median) ⓘ | 14.15% | 9.38% |
| ROA (5Y Median) ⓘ | 7.51% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | -0.88 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.20 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | -0.65 | 1.39 |
| Net Debt / Assets ⓘ | -18.00% | 19.28% |
| EBITDA / Interest ⓘ | 51.54 | 9.58 |
| Operating Margin (Latest) ⓘ | 5.10% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 4.68% | 10.29% |
| Debt to Equity (Latest) ⓘ | 12.65% | 65.48% |
| Profit Margin (Latest) ⓘ | 4.55% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $281.93M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +136.58% | +61.68% |
| 12M Return (excl. last month) ⓘ | +128.10% | +12.58% |
| 6M Return ⓘ | +2.22% | 0.00% |
| Price vs. 200-Day MA ⓘ | +24.82% | +0.02% |
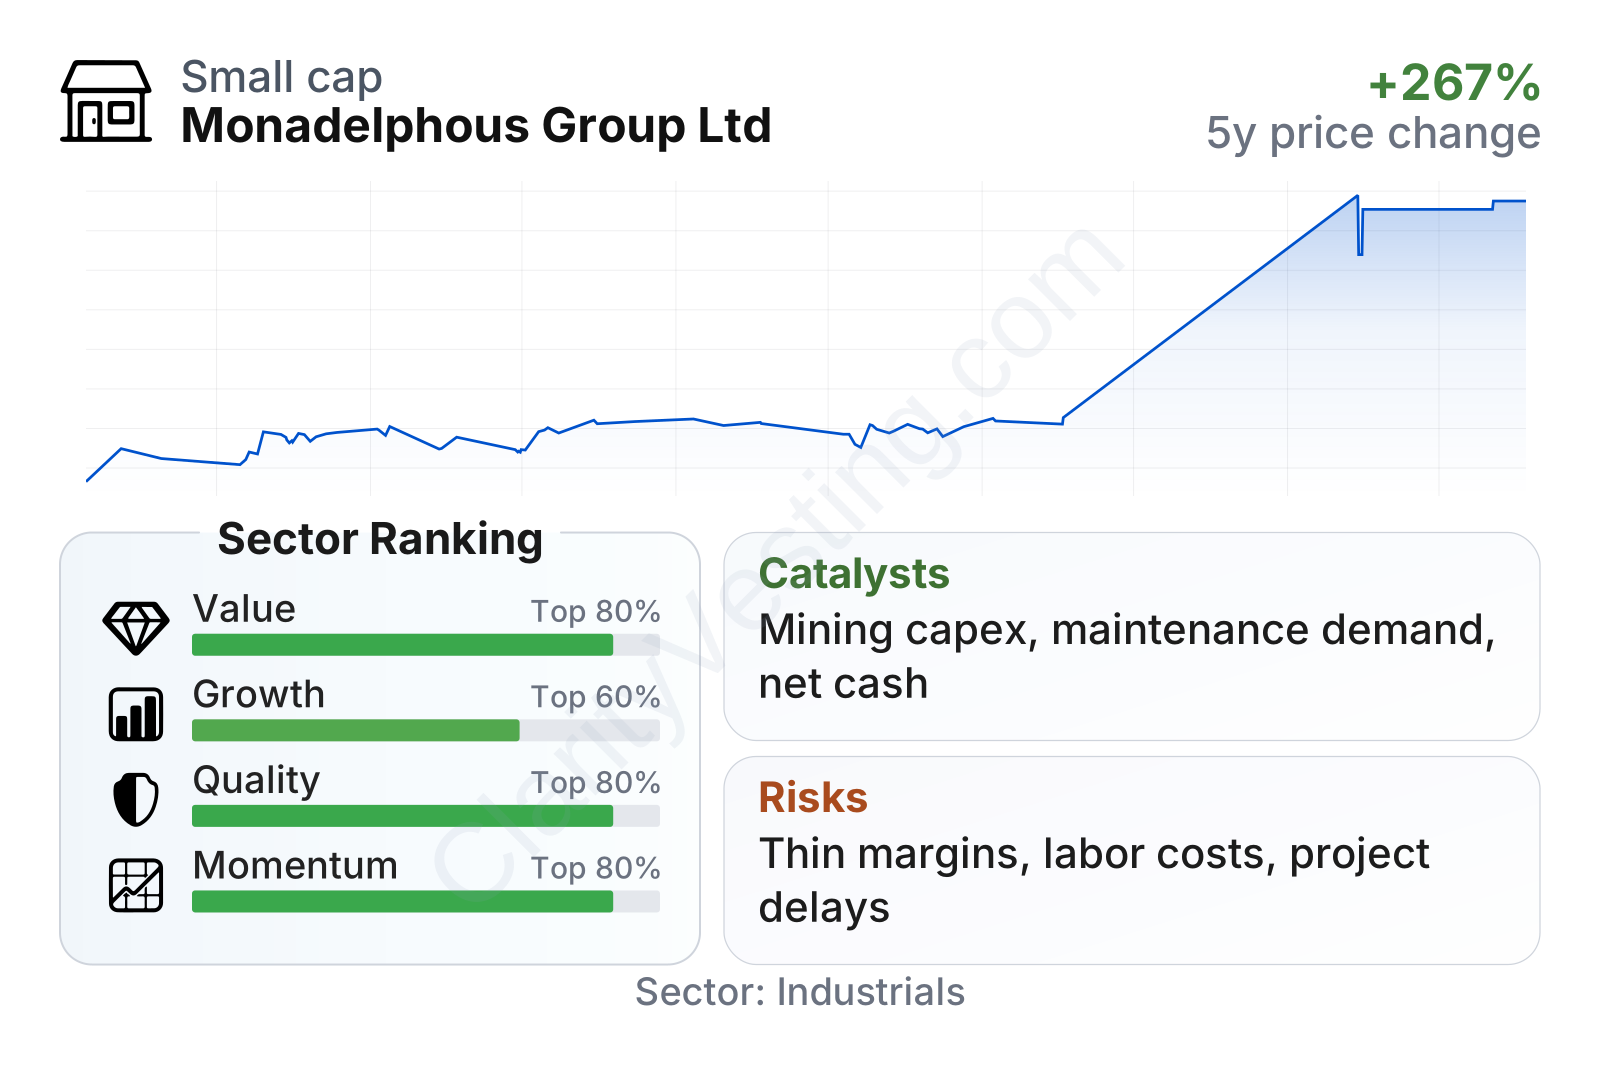
Monadelphous currently sits in the upper tier of its sector on value, quality, and momentum measures, with growth around the better half of the peer group. The most striking feature is balance-sheet strength: the company is in a net cash position rather than relying on heavy debt, and interest coverage is exceptionally strong. Profitability is solid in return terms, but operating margins remain below the sector median, which reflects the low-margin nature of contracting work. Cash generation has been notably strong, with free cash flow yield and shareholder distributions standing above typical sector levels.
The stock performance has also been powerful. Over the last three years, the share price has increased far more than the sector median, and recent trading has stayed well above the long-term average trend line. That strong market performance usually signals that investors have already recognized the company’s improving fundamentals.
Growth
Monadelphous operates in sectors with durable long-term spending needs. Mining and energy assets require constant maintenance, shutdowns, and life-extension work. On top of that, Australia continues to invest in minerals processing, gas infrastructure, water assets, renewables-related projects, and transport links. This creates a useful combination for the company: recurring support work from existing industrial facilities and periodic upside from new project awards.
The strategy also makes sense. Monadelphous is not trying to become a high-risk developer or a capital-intensive asset owner. Instead, it focuses on contract services where it already has technical capability, customer relationships, and workforce depth. That is usually a more disciplined path in engineering services, especially in cyclical markets. The company has also expanded through selective partnerships and acquisitions in adjacent capabilities, which can deepen customer access without changing the overall business model.
A major catalyst is continued capital spending tied to resources and energy transition themes. Australia’s role in iron ore, copper, lithium, gas, and other mineral supply chains supports ongoing engineering and maintenance demand. Even where commodity prices fluctuate, producing assets still require sustaining work. This tends to support baseline activity levels better than pure new-build contractors enjoy.
Recent company reporting also points to a healthy pipeline of opportunities, with stronger annual revenue and profit in the latest year. The improvement in 2026 revenue and earnings indicates that market demand has been converting into actual work, not just tender activity. If order intake remains healthy, the current platform gives Monadelphous room to keep scaling earnings without stressing the balance sheet.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


