Stock Analysis · Moog Inc (MOG-B)
Overview
Moog Inc is an aerospace and defense manufacturer focused on high-performance motion and control systems. In simple terms, the company makes the hardware and subsystems that help aircraft, satellites, missiles, launch vehicles, military vehicles, and industrial machines move precisely and reliably. Its products include flight controls, servo valves, actuators, avionics, motors, and related components used in applications where failure is not acceptable.
Moog’s business is diversified across commercial aerospace, military programs, space, and industrial markets. That mix matters because it gives the company exposure to long product cycles, recurring aftermarket demand, and government-backed defense and space spending, while still participating in more cyclical industrial markets.
Based on the latest annual reporting structure, the main revenue sources are approximately:
- Aircraft Controls: about 43% of revenue. This segment includes primary and secondary flight controls, avionics, and related systems for commercial and military aircraft.
- Space and Defense Controls: about 29% of revenue. This includes motion control products for satellites, launch vehicles, missiles, strategic defense systems, and military platforms.
- Industrial Systems: about 20% of revenue. This business serves industrial automation, simulation, medical, marine, and energy applications with precision motion products and systems.
- Medical Devices: about 8% of revenue. This segment mainly supports infusion therapy and enteral feeding products.
The broader financial flow shows a company that has been expanding revenue steadily over the last several years while also improving operating income and net income. Gross profit has risen meaningfully faster than sales, which suggests better mix, pricing, execution, or all three. One notable point is that research and development spending increased sharply more recently, which fits a company trying to deepen its position in technically demanding programs rather than simply managing for short-term margins.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Aerospace & Defense | |
| Market Cap ⓘ | $12.59B | |
| Beta ⓘ | 0.97 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 33.79 | 22.45 |
| P/B Ratio ⓘ | 5.59 | 1.98 |
| FCF Yield ⓘ | 1.94% | 6.31% |
| Dividend Yield ⓘ | 0.30% | 1.96% |
| EBIT / EV ⓘ | 3.95% | 4.81% |
| PEG ⓘ | 1.50 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 15.20% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 8.05% | 7.75% |
| EPS Growth (5Y CAGR) ⓘ | 14.55% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 9.40% | 6.22% |
| Margin Growth (5Y Trend) ⓘ | 1.63% | 0.72% |
| FCF Growth (5Y CAGR) ⓘ | -6.01% | 10.98% |
| DPS Growth (5Y CAGR) ⓘ | 3.38% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 13.80% | 10.92% |
| ROA (Latest) ⓘ | 8.20% | 5.41% |
| ROIC (5Y Median) ⓘ | 9.21% | 9.21% |
| ROA (5Y Median) ⓘ | 4.72% | 4.94% |
| Net Debt / EBIT (Latest) ⓘ | 2.14 | 2.07 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.84 | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | 1.76 | 1.43 |
| Net Debt / Assets ⓘ | 22.59% | 19.27% |
| EBITDA / Interest ⓘ | 9.26 | 9.53 |
| Operating Margin (Latest) ⓘ | 11.66% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 8.42% | 10.27% |
| Debt to Equity (Latest) ⓘ | 51.56% | 65.48% |
| Profit Margin (Latest) ⓘ | 8.73% | 6.62% |
| Free Cash Flow (Latest) ⓘ | $243.90M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +250.03% | +58.56% |
| 12M Return (excl. last month) ⓘ | +88.20% | +15.63% |
| 6M Return ⓘ | +31.79% | +4.19% |
| Price vs. 200-Day MA ⓘ | +22.41% | +0.93% |
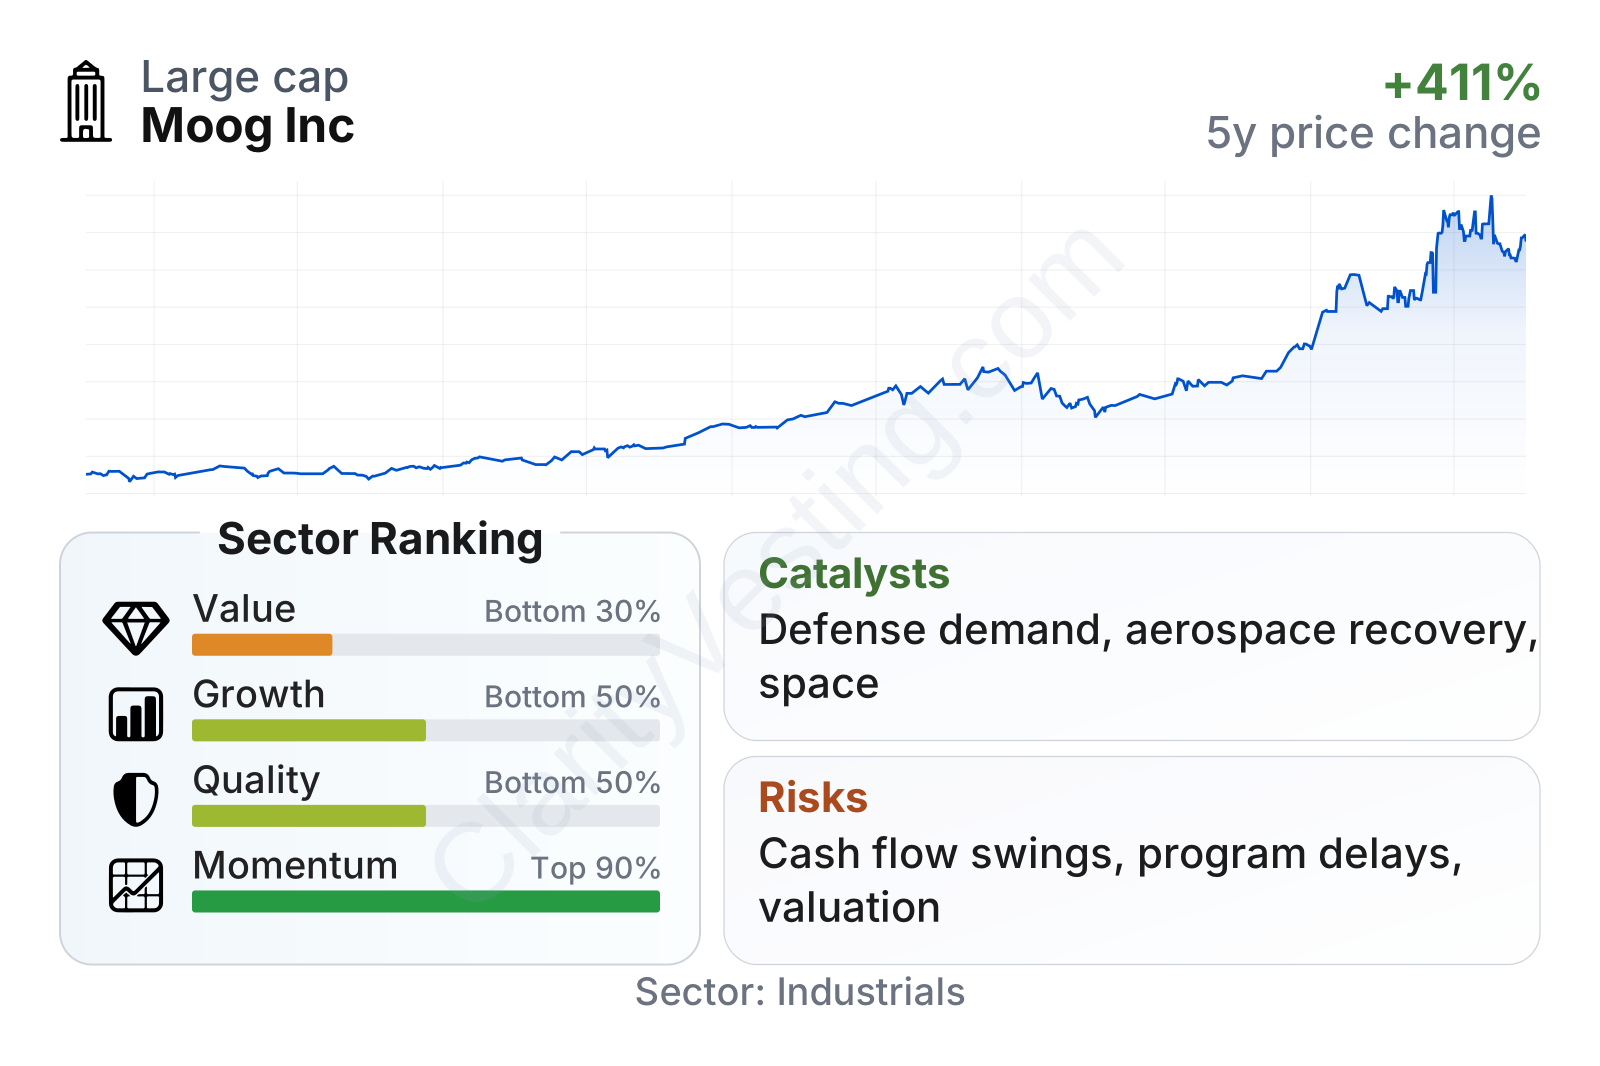
Moog sits in the large mid-cap range and its share price has been exceptionally strong over the last three years. The table points to a company with strong recent market momentum, decent profitability, and solid returns on capital, but also a richer valuation than much of the industrials sector. Revenue growth has been better than the sector median recently, while cash-flow-based valuation measures and dividend yield look less attractive. In other words, the market is giving Moog credit for improved business performance and future potential, not for being cheap.
Growth
Moog operates in markets with favorable long-term demand drivers. Commercial aerospace is benefiting from aircraft production recovery, fleet modernization, and a large installed base that needs replacement parts and service. Defense spending remains supported by global security tensions, rising demand for precision-guided systems, and the need to upgrade existing military platforms. Space is still a structurally attractive niche because satellites, launch systems, and national security space programs all require specialized, high-reliability components. These are not fast-changing consumer markets; they are long-cycle technical markets where certifications, mission-critical performance, and engineering reputation matter.
Moog’s strategy also fits those markets well. The company focuses on specialized subsystems rather than commodity hardware, and that usually supports better pricing power and sticky customer relationships. Its presence across commercial aviation, defense, and space creates more than one growth path at the same time. Management has also emphasized operational improvement and portfolio focus in recent years, which appears to be showing up in stronger margins and earnings growth.
Revenue growth has not been perfectly smooth, but the recent pattern is clearly stronger than it was a few years ago. The latest year-over-year pace is in the mid-teens, ahead of the sector median, and the last several reported periods show acceleration compared with the slower growth phase seen earlier in the cycle. That suggests current demand is being supported by both aerospace recovery and defense-related strength rather than a one-off event.
Cash generation has been more uneven than revenue. Free cash flow has moved from positive to negative and back again over the last few years, which is not unusual for a company exposed to program timing, working capital swings, and production ramps. The encouraging part is that trailing cash flow has rebounded into clearly positive territory again. For long-term business quality, that rebound matters, but the volatility is still something to watch because it shows that accounting earnings and cash conversion do not always move together in a straight line.
Recent company updates have reinforced the idea that Moog is participating in several favorable end markets at once: stronger commercial aircraft build activity, healthy defense demand, and continuing opportunities tied to space and military modernization. Those are meaningful catalysts because they tend to support multi-year order activity rather than only short bursts of demand.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


