Stock Analysis · Minth Group Limited (MNTHY)
Overview
Minth Group Limited is an auto parts manufacturer focused on the exterior and structural parts used in passenger vehicles. The company supplies global carmakers with products such as trim parts, body structural components, battery housings, and other metal and plastic parts that go into both traditional gasoline vehicles and electric vehicles. While the ADR ticker MNTHY trades in the U.S. over the counter, the operating business is centered mainly in China and serves a broad set of international original equipment manufacturers.
Its business mix has increasingly shifted toward products linked to vehicle lightweighting and electrification. That matters because carmakers are trying to reduce vehicle weight, improve energy efficiency, and develop dedicated electric vehicle platforms, all of which can increase demand for aluminum body parts and battery enclosure systems.
Public company materials indicate that revenue is mainly generated from automotive parts sold to OEM customers, with the following broad mix often highlighted in its reporting and investor communications:
- Automotive metal and trim products: historically the largest revenue source, roughly 50% to 60% of sales in recent years. This includes decorative trim, body components, and other exterior parts.
- Body structural parts and chassis-related components: roughly 20% to 30%. This category has benefited from demand for lighter, stronger vehicle structures.
- Battery housings and battery box systems for new energy vehicles: roughly 15% to 25%, with a rising importance as EV programs scale up.
- Other automotive parts and services: generally a small residual share, including additional plastic parts, tooling, and related supporting activities.
Geographically, China remains the core market, but Minth also manufactures and serves customers in Europe, North America, and other Asian markets. That international footprint is important because the company follows global vehicle platforms rather than relying on one local market alone.
The long-term operating picture is favorable: revenue has expanded strongly since 2021, gross profit has risen, and operating income improved sharply through 2024 before easing in 2025. Research and development spending has also climbed over time, showing that Minth continues to invest in newer vehicle architectures rather than simply defending an older trim-parts business.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Auto Parts | |
| Market Cap ⓘ | $3.49B | |
| Beta ⓘ | 1.29 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.61 | 16.89 |
| P/B Ratio ⓘ | 0.15 | 1.61 |
| FCF Yield ⓘ | 102.73% | 8.99% |
| Dividend Yield ⓘ | 3.27% | 2.73% |
| EBIT / EV ⓘ | N/A | 6.69% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 9.10% | 5.60% |
| RPS Growth (5Y CAGR) ⓘ | 15.79% | 8.91% |
| EPS Growth (5Y CAGR) ⓘ | -36.56% | -17.41% |
| BVPS Growth (5Y CAGR) ⓘ | 8.97% | 5.62% |
| Margin Growth (5Y Trend) ⓘ | 2.57% | -0.17% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.91% |
| DPS Growth (5Y CAGR) ⓘ | -8.47% | 9.86% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 12.38% |
| ROA (Latest) ⓘ | 11.17% | 5.49% |
| ROIC (5Y Median) ⓘ | 6.26% | 10.75% |
| ROA (5Y Median) ⓘ | 5.37% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 0.79 | 2.17 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.82 | 2.30 |
| Net Debt / EBITDA (Latest) ⓘ | 0.50 | 1.50 |
| Net Debt / Assets ⓘ | 9.12% | 21.57% |
| EBITDA / Interest ⓘ | N/A | 9.13 |
| Operating Margin (Latest) ⓘ | 11.24% | 9.10% |
| Operating Margin (5Y Median) ⓘ | 9.56% | 9.56% |
| Debt to Equity (Latest) ⓘ | 40.78% | 75.99% |
| Profit Margin (Latest) ⓘ | 10.61% | 5.31% |
| Free Cash Flow (Latest) ⓘ | $3.58B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +19.65% | +15.94% |
| 12M Return (excl. last month) ⓘ | -22.38% | -2.82% |
| 6M Return ⓘ | -38.82% | -1.58% |
| Price vs. 200-Day MA ⓘ | -28.66% | -3.31% |
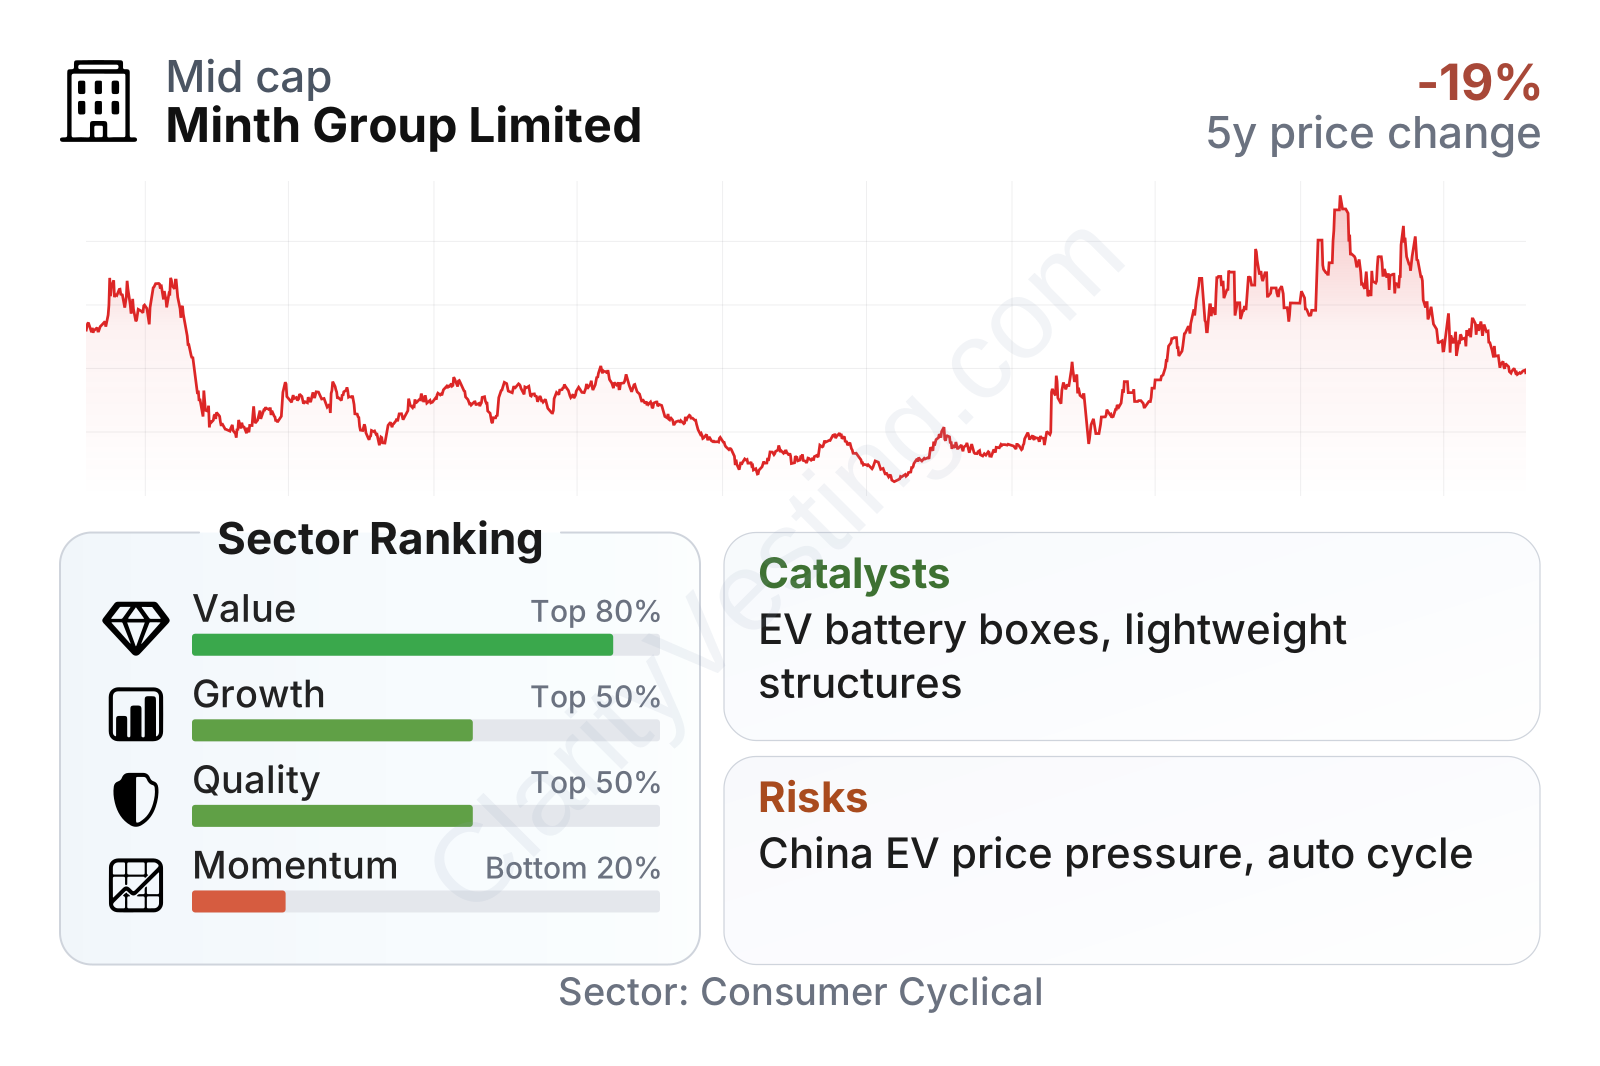
The valuation metrics appear inexpensive relative to much of the auto parts sector, with a low earnings multiple, a very low price-to-book ratio, and a free cash flow yield that stands far above the sector median. Profitability is better than many peers as well, with operating margin and net margin ahead of typical sector levels. Balance sheet leverage looks controlled: debt-to-equity is around 41%, and net debt relative to earnings is well below sector norms.
The mixed area is growth quality. Revenue has been advancing at a healthy pace, including stronger recent year-over-year growth than the sector median and a solid five-year rise in revenue per share. However, five-year earnings-per-share growth remains weak, which suggests that profit expansion has not been consistently smooth across the full cycle. Market performance has also been soft recently, with the shares falling noticeably over the last six to twelve months and trading well below their longer-term trend line despite a stronger multi-year record.
Growth
Minth operates in a part of the auto industry that is still evolving in ways that support its product lineup. The most important trends are electric vehicles, lightweight materials, and more complex body structures. Battery electric vehicles need battery housings, thermal and safety-related structural protection, and efficient use of aluminum and other lighter materials. Those trends can expand content per vehicle for suppliers that already have engineering and manufacturing scale in these categories.
The company’s strategy broadly makes sense for that environment. Minth has been moving from decorative trim into more technically demanding parts, especially aluminum body structures and battery enclosures. That shift can be meaningful because these products tend to be more integrated into vehicle platforms and can create longer program visibility once designed into a model.
Another constructive point is customer relevance. Minth supplies major global automakers, and that matters because EV adoption is not dependent on one single brand. If global manufacturers continue to launch new electric and hybrid platforms, suppliers with established qualification records can capture additional volume across multiple regions.
Recent corporate updates and annual reporting have emphasized expansion in battery housing systems, lightweight body products, and overseas manufacturing support for global customers. In practical terms, the opportunity is not just more vehicles being produced, but more Minth content embedded in each vehicle. That is often the better growth driver for parts makers than overall industry unit growth alone.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


